
Learn Why The Bull Case For Toast Stock Could Change Following Voice AI Integration
- Presto Phoenix, Inc. and Kung Fu Tea recently announced separate agreements with Toast, integrating Toast POS with Presto Voice AI and rolling out Toast hardware, software, and payments across more than 330 Kung Fu Tea locations in the United States.
- These deals show Toast embedding its platform deeper into quick-service and beverage chains, tying its payments, hardware, and AI-friendly infrastructure directly to day-to-day restaurant operations and staffing efficiency.
- We will examine how Toast's investment narrative is shaped by this deeper QSR integration, especially the Presto Voice AI link into its POS platform.
Scan the QSR and restaurant tech space beyond Toast by reviewing a curated short list of 16 high quality undiscovered gems that are already building the next wave of order automation and payments infrastructure.
Toast Investment Narrative Recap
To own Toast, you need to believe restaurants will keep upgrading from legacy systems to fully integrated platforms that tie together ordering, payments, and automation. The recent Presto Voice AI integration and the Kung Fu Tea rollout both reinforce that vision. They show Toast embedding deeper into operations rather than selling point tools, which supports its push toward higher ARPU and more recurring fintech revenue.
The near term swing factor is execution on large rollouts and new modules while keeping costs in check. Sales and marketing and hardware spending can squeeze margins if payback slows. Pressure from competitors and soft restaurant trends, including weaker same store sales and flat to lower gross payment volume per location, remain the clearest risks.
The Presto Voice AI partnership looks most relevant for Toast right now. It plugs automation directly into the Toast POS so AI captured drive thru orders flow straight into the kitchen, which can reduce errors and support throughput. That fits the broader push into labor saving tools that help restaurant customers handle staffing constraints and wage pressure with more automation rather than extra headcount.
Operationally, this kind of integration can strengthen Toast’s pitch to multi unit QSR brands that want a single platform for software, payments, and AI ready workflows. The upside is deeper stickiness and potential module expansion. The risk is that hardware and deployment costs rise faster than usage, or that rivals like Square and Clover respond with similar bundles that pressure pricing and acquisition costs.
Toast's analyst narrative points to US$11.2b in revenue and US$1.1b in earnings by 2029, based on an assumed 18.0% yearly revenue growth rate and an earnings increase of about US$614m from US$486.0m today.
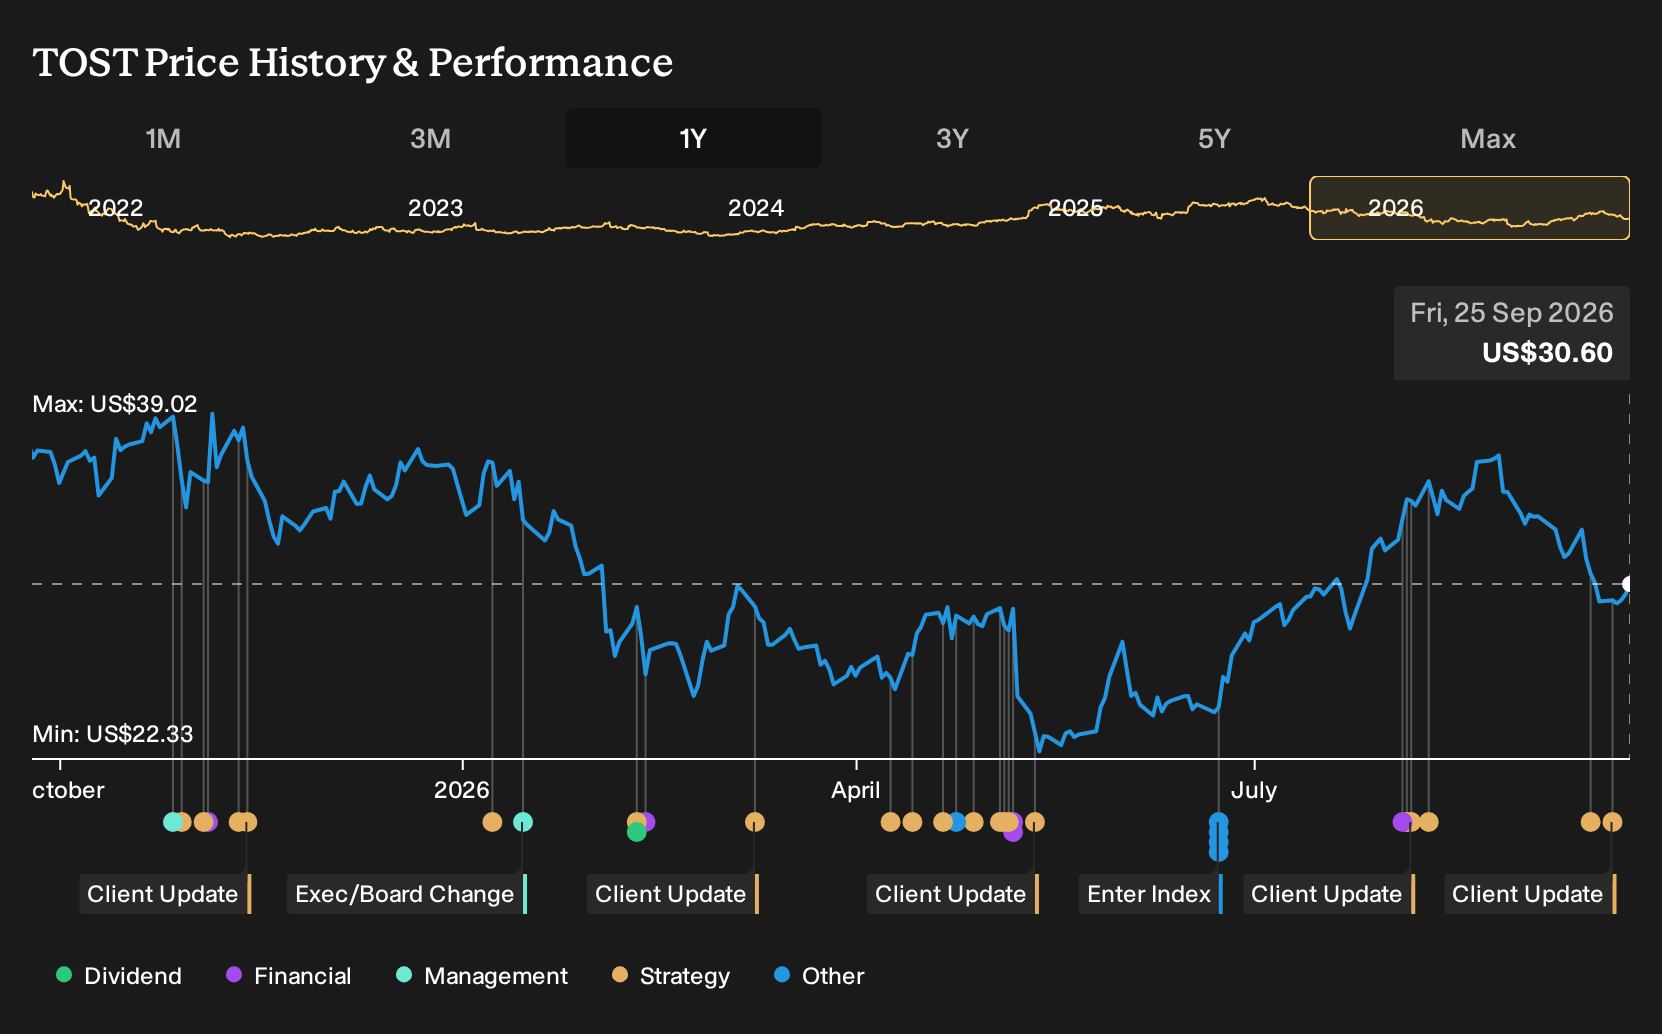
Uncover how Toast's fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can also look at Toast through the most cautious lens. The lowest analysts focus on saturation risk. They worried that pushing toward roughly US$11.0b in revenue and US$850.2m in earnings by 2029 might prove too ambitious. Those forecasts came before this Presto and Kung Fu Tea news, so their story could shift.
Explore 6 other Toast fair value estimates, including one that suggests it could be worth just $36.45.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toast research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Toast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toast's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toast?
If this Toast story has you thinking about where else automation, payments and strong balance sheets might create opportunity, it can help to widen the lens and compare it with other businesses that fit clear, data driven filters.
- For investors who want quality and value in the same place, start with a focused set of 32 high quality undervalued stocks that pair solid fundamentals with appealing P/S or P/E profiles.
- If capital preservation is your first priority, consider a basket of 30 resilient stocks with low risk scores that score well on balance sheet strength and volatility checks.
- For anyone who cares most about resilience in down cycles, review a list of solid balance sheet and fundamentals (24 results) to see which businesses carry lower debt and stronger cash positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com