
How Investors Are Reacting To Eastern Bankshares Stock After Mixed Earnings
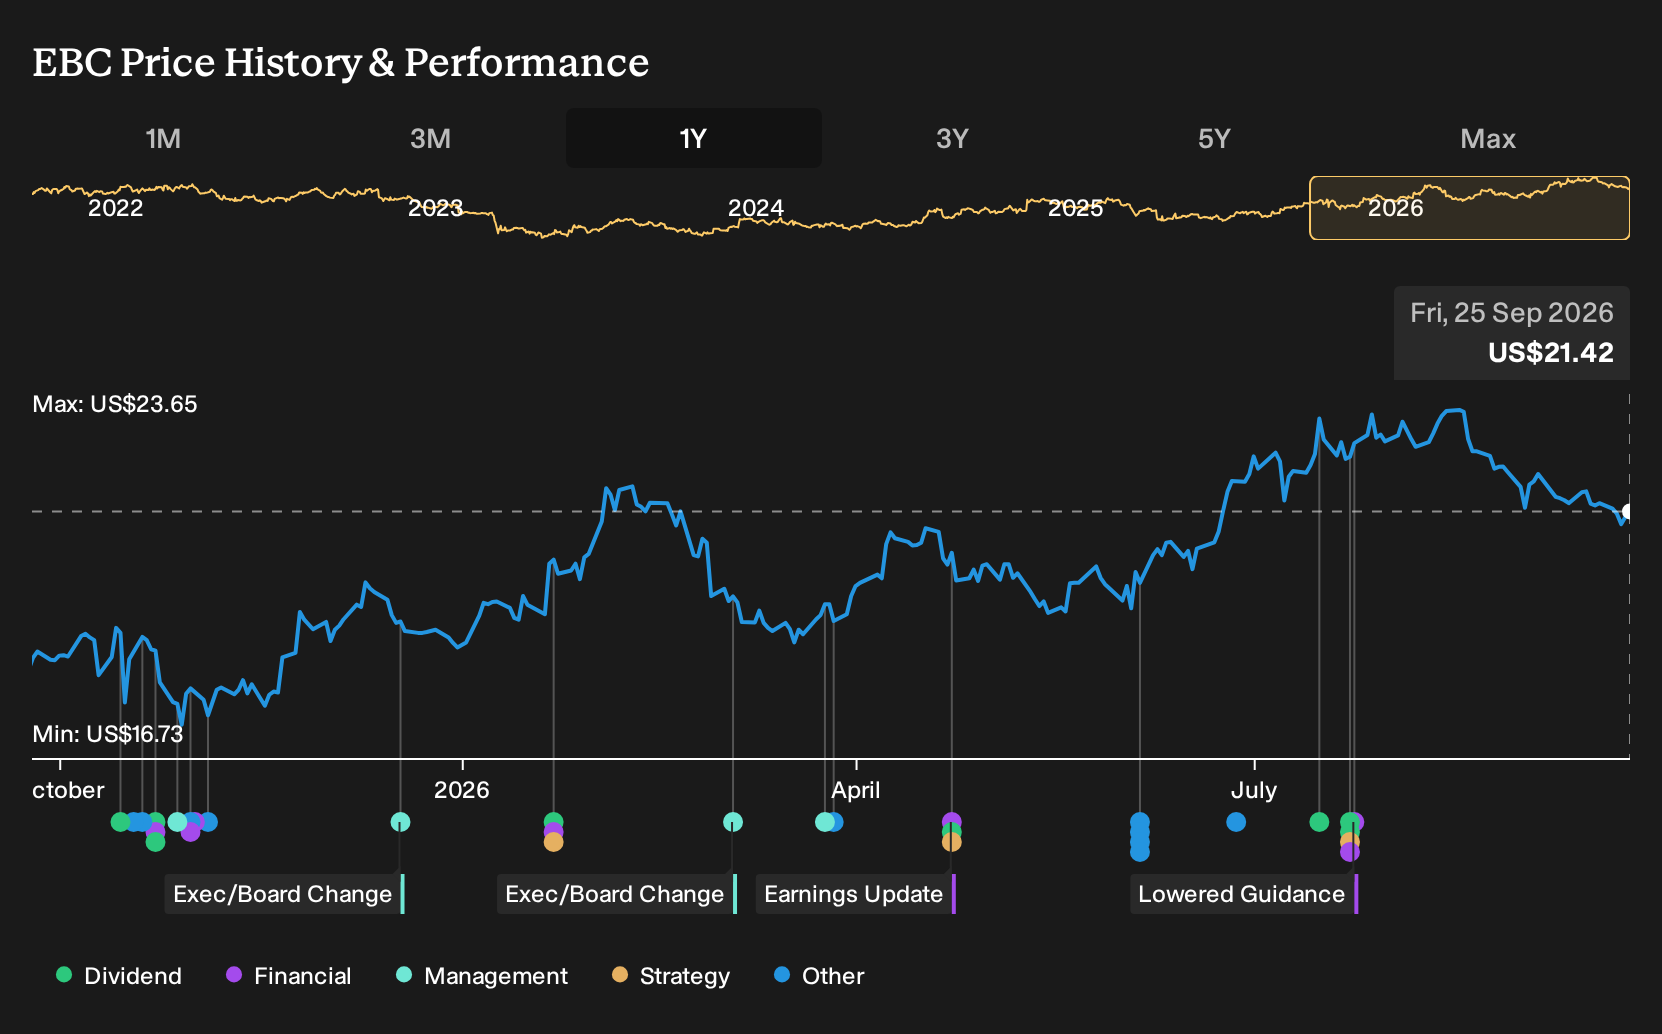
- Eastern Bankshares recently reported results, with revenue and tangible book value ahead of analyst expectations, while net interest income and several profitability metrics remained under pressure.
- The merger with Cambridge Trust and heavier digital banking investment now sit alongside declining tangible book value and a modest net interest margin. This combination highlights a tension between growth initiatives and current returns.
- Next, the focus turns to how Eastern Bankshares' mixed revenue and net interest income picture could reshape the broader investment narrative for the bank.
Compare Eastern Bankshares' valuation reset with other banks facing similar pressure on net interest income by scanning the 32 high quality undervalued stocks currently trading out of favour with the market.
Eastern Bankshares Investment Narrative Recap
To own Eastern Bankshares, you need to be comfortable with a story that trades near term pressure on net interest income and a modest 3.5% net interest margin for the potential benefits of a larger regional footprint and stronger digital offering. The recent revenue beat supports the idea that the enlarged franchise can still produce top line growth, even as tangible book value per share has eroded by 3.2% a year and return on equity stays muted.
The key short term swing factor is how quickly the merged bank can translate its bigger balance sheet and technology spend into steadier earnings without further hits to book value. The biggest risk remains asset quality and reserve intensity in commercial real estate and office loans, which can keep profitability under strain if loss expectations or problem credits worsen from here.
The most relevant piece of context for this earnings reaction is the completed merger with Cambridge Trust. That deal gives Eastern Bankshares more scale in Greater Boston, Eastern Massachusetts, and New Hampshire, along with a larger wealth management operation and an expanded online and mobile banking platform. The recent revenue outperformance lines up with a larger customer base and broader product set.
Where investors are now focused is execution. Integration costs have already contributed to a GAAP net loss in one quarter, reserves for commercial real estate are higher, and the sale of Cambridge’s investment portfolio removes some accretion income that analysts once counted on. For the stock, the real catalyst is whether management can wring stable, higher quality earnings from the combined bank while keeping credit issues contained.
What The Eastern Bankshares Forecasts Assume
Eastern Bankshares' current analyst storyline leans heavily on a meaningful ramp in both revenue and profits over the next few years, even as investors are still digesting merger noise and credit headlines. Consensus forecasts point to revenue expanding by 12.6% a year and earnings moving from $376.1 million today to $532.0 million by 2029, while profit margins edge slightly lower from 34.3% to 33.9%. That earnings path implies an increase of about $155.9 million from current levels, which is what needs to show up in the income statement to justify the current projections.
Eastern Bankshares' narrative projects US$1.6b revenue and US$532.0 million earnings by 2029. This requires 12.6% yearly revenue growth and about US$155.9 million earnings increase from US$376.1 million today.
Uncover why Eastern Bankshares' fair value indicates a 14% potential upside to its current price before other investors address that discount.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$24.44 and US$34.19, so some retail investors see Eastern Bankshares as materially mispriced in opposite directions. Set that against underwhelming returns, pressure on tangible book value, and commercial real estate risks, and you get sharply different opinions worth comparing.
Explore 2 other Eastern Bankshares fair value estimates, including one that suggests up to 60% potential upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eastern Bankshares research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eastern Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eastern Bankshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Eastern Bankshares?
Once you have formed a view on Eastern Bankshares, it can help to compare that thesis with other opportunities that share similar qualities or risks. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that actually matches your investing style.
- If you want income and resilience at the same time, shortlist higher yielding companies that look more defensible using the 8 dividend fortresses.
- For balance sheet strength and fewer financial red flags, focus on businesses screened from the list of solid balance sheet and fundamentals (24 results) to stress test your portfolio quality.
- Readers hunting for mispriced opportunities can scan the 16 high quality undiscovered gems that may be flying under the radar despite solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com