
Is Sparebanken Norge (OB:SBNOR) Fairly Valued Following Its Leadership Reshuffle?
Sparebanken Norge (OB:SBNOR) has reshaped its top team by creating a new Executive Vice President role for Asset Management and Corporate Social Responsibility and appointing veteran banker Eskild Stenhaug, while also reallocating responsibilities for major projects.
Recent trading has been supportive for Sparebanken Norge, with a 30 day share price return of 4.49% and a 90 day share price return of 16.12%, bringing the current share price to NOK 213.9.
Scan how Sparebanken Norge compares with other Nordic financial institutions by reviewing our hand picked list of solid balance sheet and fundamentals (202 results) in the same space.
Sparebanken Norge now sits on a strong recent share gain and a refreshed leadership focus on asset management and responsibility. Are investors paying for sentiment, or for what the underlying banking business is already delivering?
Price-to-Earnings of 13.3x: Is it justified?
Valuation on Sparebanken Norge today hinges on a P/E of 13.3x at a share price of NOK 213.9. This sits above both the Norwegian banks peer group and the sector average, while remaining only slightly below an estimated fair ratio.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors pay for each unit of profit. For a bank like Sparebanken Norge, where earnings quality is flagged as high and profits have grown 23.2% per year over five years, that yardstick is often used as a shorthand for what the market is willing to pay for the current earnings profile.
That willingness looks elevated. Sparebanken Norge trades on 13.3x earnings compared to 12.1x for the Norwegian banks industry and 11.3x for its direct peer set. This suggests investors are accepting a richer tag than for many local lenders. Even so, the ratio is close to an estimated fair P/E of 13.8x, which implies the crowd is not stretching far beyond a level the market could move towards if expectations hold.
Explore the SWS fair ratio for Sparebanken Norge.
Result: Price-to-Earnings of 13.3x (OVERVALUED)
Still, the story around Sparebanken Norge can change quickly if earnings momentum cools or if asset quality trends weaken and increase pressure on capital needs.
Find out about the key risks to this Sparebanken Norge narrative.
Another View on Sparebanken Norge’s Value
The P/E story presents Sparebanken Norge as slightly expensive, yet still close to a fair ratio. A different lens gives a sharper perspective. Our DCF model implies a future cash flow value of NOK 150.24 per share, which places the current NOK 213.9 quote in clearly overvalued territory.
That is a sizeable gap in kroner terms and it raises a practical question for any holder. Is the extra NOK 60 plus per share you are paying really for future earnings power, or mainly for recent momentum in the Sparebanken Norge share price?
Look into how the SWS DCF model arrives at its fair value.
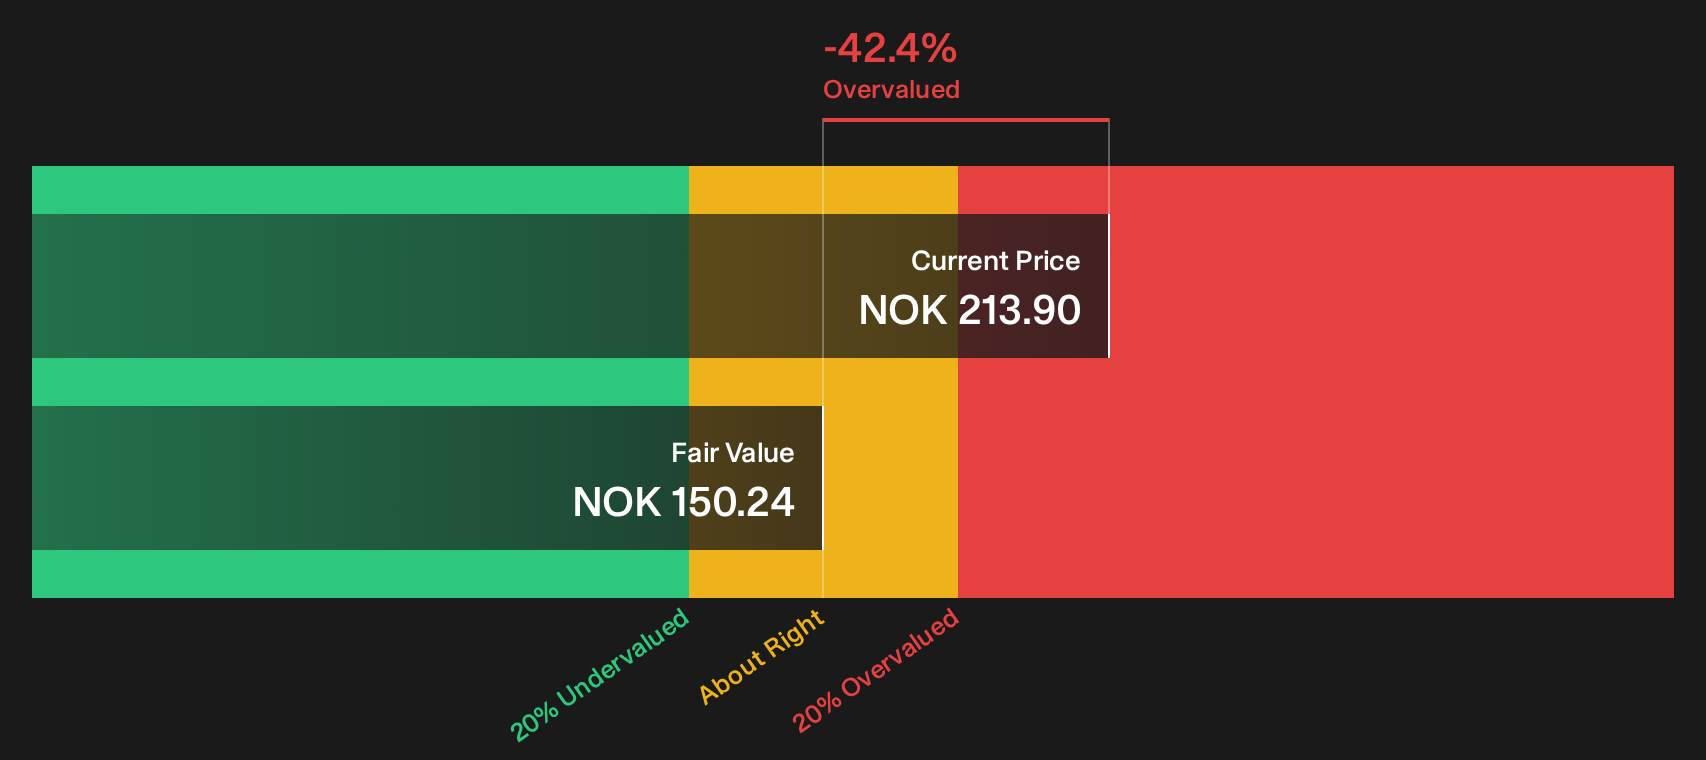
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sparebanken Norge for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around Sparebanken Norge point in different directions, so treat this as your prompt to move fast, review the numbers yourself, and weigh both sides. For a balanced view of what could go right and what could go wrong, start with our 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Sparebanken Norge?
If you stop with Sparebanken Norge, you risk missing other opportunities that better match your goals, time horizon, and appetite for volatility.
- Target resilience first and scan a curated 227 resilient stocks with low risk scores if you want companies where balance sheets and risk scores do more of the heavy lifting for you.
- Chase value with discipline and review a focused 182 high quality undervalued stocks when you want solid fundamentals without paying up for the latest story.
- Build income that works harder and assess a concentrated 162 dividend fortresses if reliable cash payouts are a core part of your long term plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com