
Is FTSE Index Removal Altering The Investment Case For Gartner Stock?
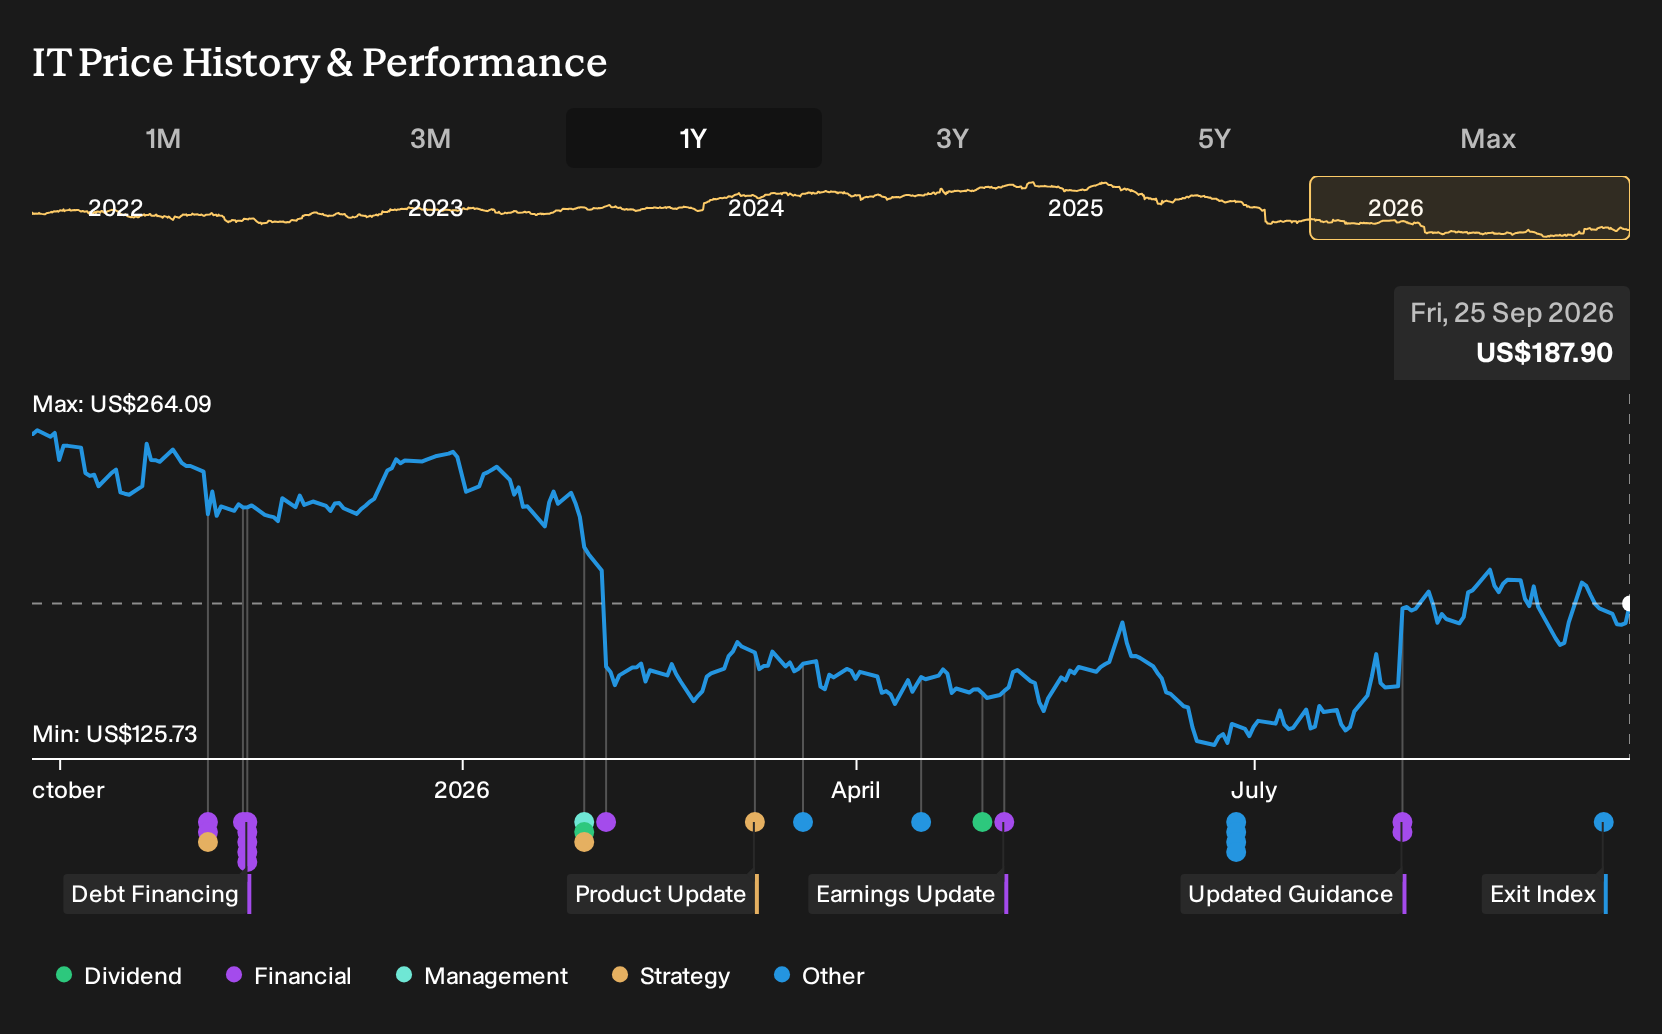
- Gartner, Inc. was removed from the FTSE All-World Index in September 2026, a change that can alter how index-linked investors hold the stock.
- This index exclusion brings fund flows and liquidity into focus for Gartner. The company relies heavily on recurring research subscriptions and long-term client contracts.
- This article will explore how Gartner's investment narrative is affected by its removal from the FTSE All-World Index and what that means for investors.
Compare Gartner's index exit with other potential opportunities by scanning a curated list of resilient companies in our 30 resilient stocks with low risk scores, which focuses on stability and lower risk profiles.
Gartner Investment Narrative Recap
To own Gartner, you need to believe its subscription research, conferences, and consulting stay essential as enterprises wrestle with AI, cybersecurity, and digital transformation decisions. The big swing factor in the near term is how well contract value holds up while clients scrutinize budgets and renewals. The FTSE All World index exit looks more like a technical event than a change in that operating thesis.
The sharper risk is on the demand and pricing side. Generative AI and cheaper open source tools could chip away at perceived value in Gartner reports. Profit margins already sit below last year and the business carries meaningful debt, so any slowdown in renewals or new business could pressure earnings and limit flexibility.
There are no new operational announcements tied directly to the FTSE All World removal. The most relevant signal for this catalyst comes from existing data points. Gartner generates the bulk of its US$6.5b revenue from the Insights segment, with Conferences and Consulting much smaller but still meaningful. That mix keeps the focus firmly on subscription stability whenever index driven fund flows move around.
Equity research currently highlights AskGartner and broader AI related offerings as important tools for keeping the research service sticky. Those products aim to make the content library more usable and time efficient for clients, which matters when approval cycles stretch and cheaper data sources are everywhere. For you as a shareholder or prospective investor, the key question is whether these efforts offset pressure from cost cutting, client consolidation, and rising alternatives.
Gartner's current narrative focuses on analysts expecting revenue of US$7.1b and earnings of US$1.1b by 2029, which implies 3.0% yearly revenue growth and an earnings increase of about US$324.6m from US$775.4m today.
Uncover why Gartner's fair value is essentially consistent with its current price.
Exploring Other Perspectives
One contrasting angle is the bullish view that Gartner’s AI tools act as a fresh catalyst, not a threat. The most optimistic analysts were pencilling in revenue of about US$7.4b and earnings of roughly US$1.2b by 2029. Those forecasts came before the FTSE All World exit, so you may see those narratives shift as this index change plays through.
Explore 4 other Gartner fair value estimates, including one that suggests as much as 55% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Gartner research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gartner. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gartner's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gartner?
Once you have a view on Gartner, it can help to set it beside other listed businesses with different risk and return profiles. A few targeted screens can quickly surface alternatives that better match your goals on income, resilience, or upside potential.
- For investors who want stability first, filter for companies with stronger balance sheets and resilient fundamentals using the list of solid balance sheet and fundamentals (24 results).
- If income is your priority, focus on stocks with higher yields and sturdier payout records by running the 8 dividend fortresses.
- To hunt for mispriced opportunities with solid underlying quality, scan the 32 high quality undervalued stocks and compare those candidates to your current watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com