
Is Earnings Beat Altering The Investment Case For Williams Sonoma Stock (WSM)?
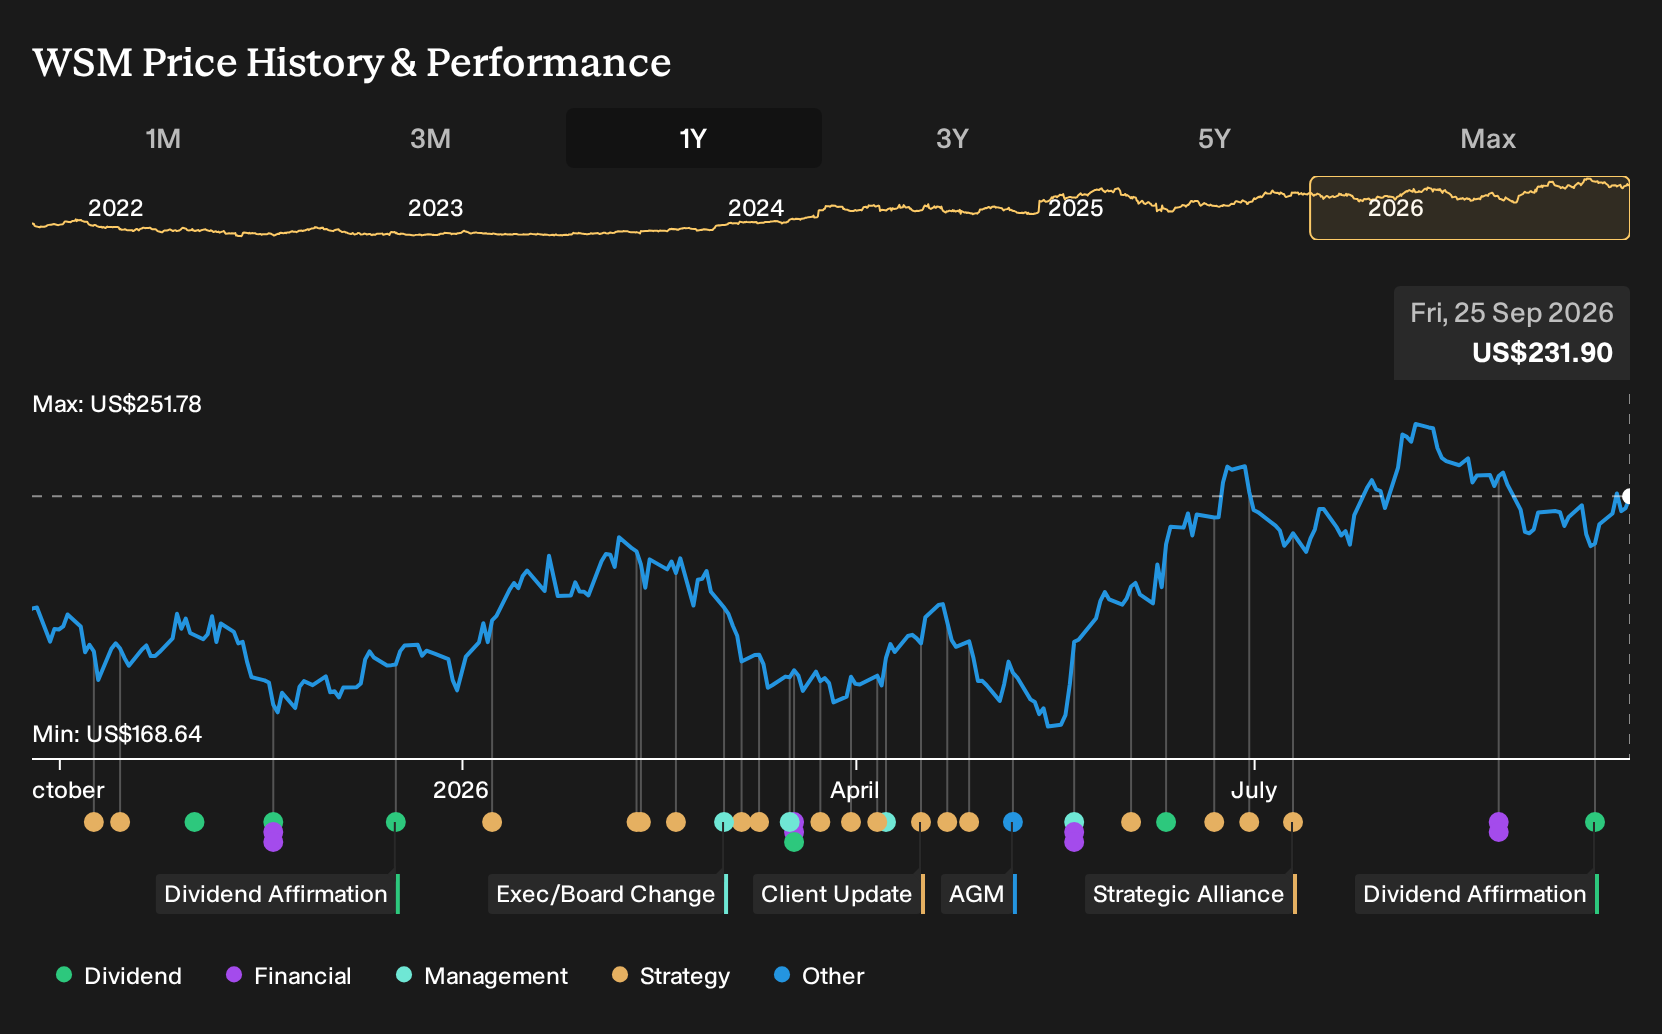
- Williams-Sonoma announced that its board declared a quarterly cash dividend of US$0.76 per share, payable on November 20, 2026 to shareholders of record as of October 16, 2026, reinforcing its pattern of regular cash returns to investors.
- The latest quarterly report showed adjusted earnings and revenue above analyst estimates, and management raised full year targets for both revenue growth and operating margin despite ongoing cost pressures from tariffs and higher oil prices, which highlights how execution and cost management sit at the center of the Williams-Sonoma story.
- We will now look at how Williams-Sonoma's raised full year guidance could influence the existing investment narrative around the retailer.
Williams-Sonoma Investment Narrative Recap
To own Williams-Sonoma, you need to believe the business can keep pairing premium home products with tight execution in areas like sourcing, digital, and inventory. The raised full year guidance leans on that belief. It points to management seeing enough demand and cost control to support higher revenue and operating margin targets despite tariff and oil headwinds.
The near term swing factor remains how effectively Williams-Sonoma can offset input cost pressure through pricing, product mix, and supply chain optimization. Tariffs and any soft patch in big ticket home spending still sit as the main risk to margins. The latest update does not remove that risk, but it does suggest it is currently being managed.
The fresh US$0.76 quarterly dividend declaration is the clearest operational signal tied to this news cycle. Regular cash returns rely on durable cash generation. For a retailer exposed to tariffs and housing sensitive categories, a maintained payout indicates the board sees the current earnings and cash profile as sufficient to support ongoing distributions.
For you as a shareholder, the dividend intersects directly with the main catalysts. Continued progress in AI driven digital tools, B2B expansion, and supply chain efficiency needs to support both capital returns and reinvestment. If tariff costs or weaker housing demand start to pressure cash flow, the trade off between funding growth projects and keeping that dividend level could become more visible.
Williams-Sonoma's current analyst narrative points to revenues of US$9.1b and earnings of US$1.3b by 2029, based on forecast annual top line growth of 4.8% and a projected increase in earnings of about US$0.2b from the current US$1.1b level.
Uncover why Williams-Sonoma's fair value indicates an 8% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Williams-Sonoma story around market share gains in a flat home category rather than tariff risk. Before this dividend news, the bullish camp was already modeling about US$9.6b of revenue and US$1.4b of earnings by 2029. That is a more upbeat script. It is worth comparing those assumptions with your own and considering how this dividend update might shift any of these pre news narratives.
Explore 2 other Williams-Sonoma fair value estimates, including one that suggests up to 8% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Williams-Sonoma research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Williams-Sonoma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams-Sonoma's overall financial health at a glance.
Looking for more investment ideas beyond Williams-Sonoma?
Once you have a view on Williams-Sonoma, it can help to compare it with other businesses that fit different risk and income profiles. The Simply Wall St screener makes this much easier by filtering for specific traits that matter to you, from income stability to balance sheet strength.
- If you want income plus resilience, start with a set of businesses that combine sizeable payouts with robust financial footing using the 8 dividend fortresses.
- If value is your focus, scan a curated pool of companies that pair solid fundamentals with prices that may not fully reflect their quality through the 32 high quality undervalued stocks.
- If capital preservation ranks high on your list, focus on sturdier balance sheets and cleaner fundamentals by running a list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com