
Learn Why The Bull Case For Grindr Stock Could Change Following Analyst Valuation Debate
- Grindr presented at the Clinton Global Initiative 2026 Annual Meeting in New York, where CEO George Arison outlined the platform’s role in LGBTQ community engagement and its reliance on recurring digital services such as ads and premium subscriptions.
- Analyst commentary has focused on Grindr’s premium valuation and its dependence on converting recurring in-app activity into earnings, placing greater attention on execution in monetization and cost control.
- This analysis will examine how the debate around Grindr's premium valuation, centered on the conversion of recurring in-app activity into earnings, shapes its broader investment narrative.
Scan beyond Grindr by reviewing hand picked 16 high quality undiscovered gems that also lean on recurring digital revenue and premium pricing power.
Grindr Investment Narrative Recap
To own Grindr, you need to believe the app can keep turning a focused LGBTQ community into steady digital revenue through ads and paid tiers. The near term hinges on how effectively recurring in app activity converts into earnings. The CGI appearance keeps Grindr visible but does not materially change that core earnings conversion story.
The biggest swing factor still sits in execution. Product and AI investments need to justify their cost, while ad monetization and premium tiers carry the load. On the risk side, high operating expenses, brand safety concerns, and reliance on a niche audience remain the key pressure points to watch.
The recent presentation at the Clinton Global Initiative is the clearest operational signal related to this news. Grindr put its community role and recurring digital services in front of a policy heavy and corporate audience. That matters for perception around brand safety, partnerships, and long run monetization efforts.
For you as an investor, the relevance ties back to catalysts already on the table. Better quality ad deals, new premium features, and expansion into new markets all rely on trust and engagement. Any improvement in Grindr's profile with institutions and advertisers could support those efforts, even if the event itself is not a direct earnings catalyst.
Grindr's current analyst narrative points to revenues of $794.3 million and earnings of $166.1 million by 2029. That profile is built on projected yearly revenue growth of 15.9% and an earnings increase of about $80.4 million from $85.7 million today.
Uncover why Grindr's fair value indicates a 32% potential upside to its current price, which could narrow quickly.
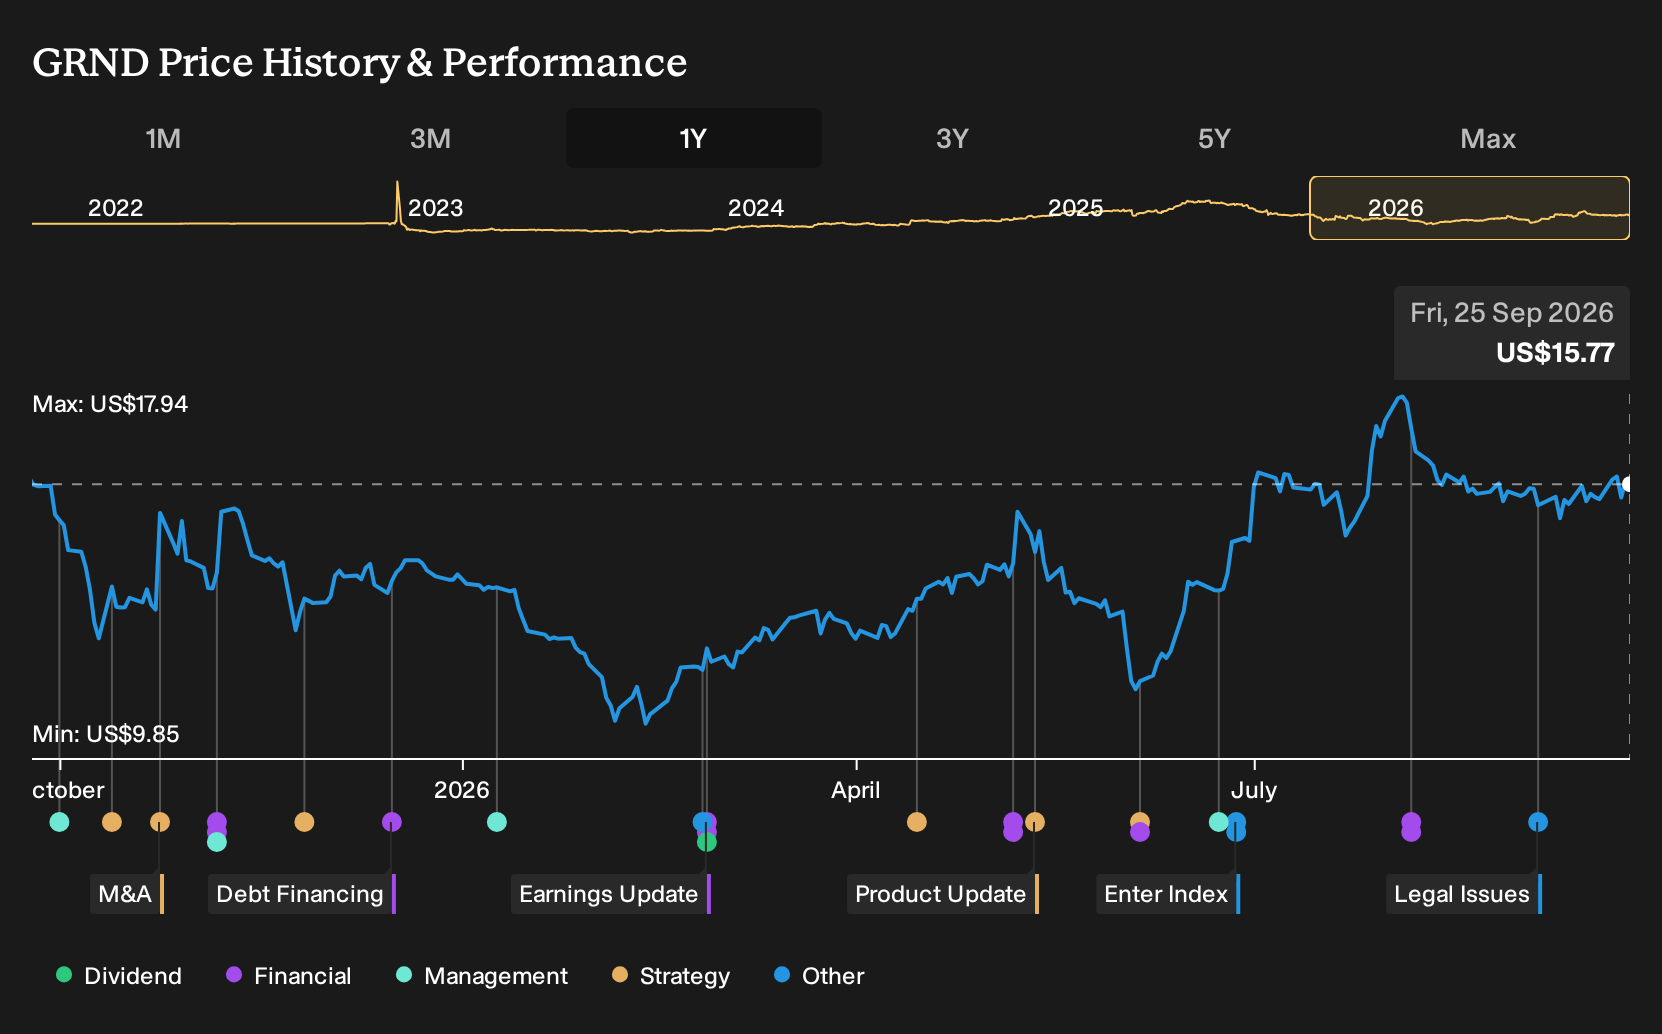
Exploring Other Perspectives
One alternate view focuses on subscription pricing as a potential catalyst that the CGI spotlight might eventually amplify. The most optimistic analysts were already sketching in revenue of about $718.5 million and earnings near $198.3 million by 2029, well above consensus. Those estimates were set before this event, so opinions may change as new information becomes available.
Explore 4 other Grindr fair value estimates, including one that suggests as much as 66830% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own well-researched perspective.
- A great starting point for your Grindr research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Grindr. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grindr's overall financial health at a glance.
Looking for more Grindr style investment ideas?
If the Grindr story has you thinking about recurring revenue and differentiated pricing power, it can be useful to widen the lens and compare it with other stocks that share some of those traits, but with very different risk profiles.
- For investors who care most about resilience and capital protection, review a curated set of companies with steadier profiles using our 30 resilient stocks with low risk scores.
- If balance sheet strength is your first filter, start with a list of solid balance sheet and fundamentals (24 results) that already clear basic leverage and liquidity checks.
- Prefer to hunt for under-the-radar opportunities, rather than well covered giants? Scan a 16 high quality undiscovered gems that combine quality metrics with lighter analyst coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com