
Does Index Removal Change The Bull Case For Qorvo Stock (QRVO)?
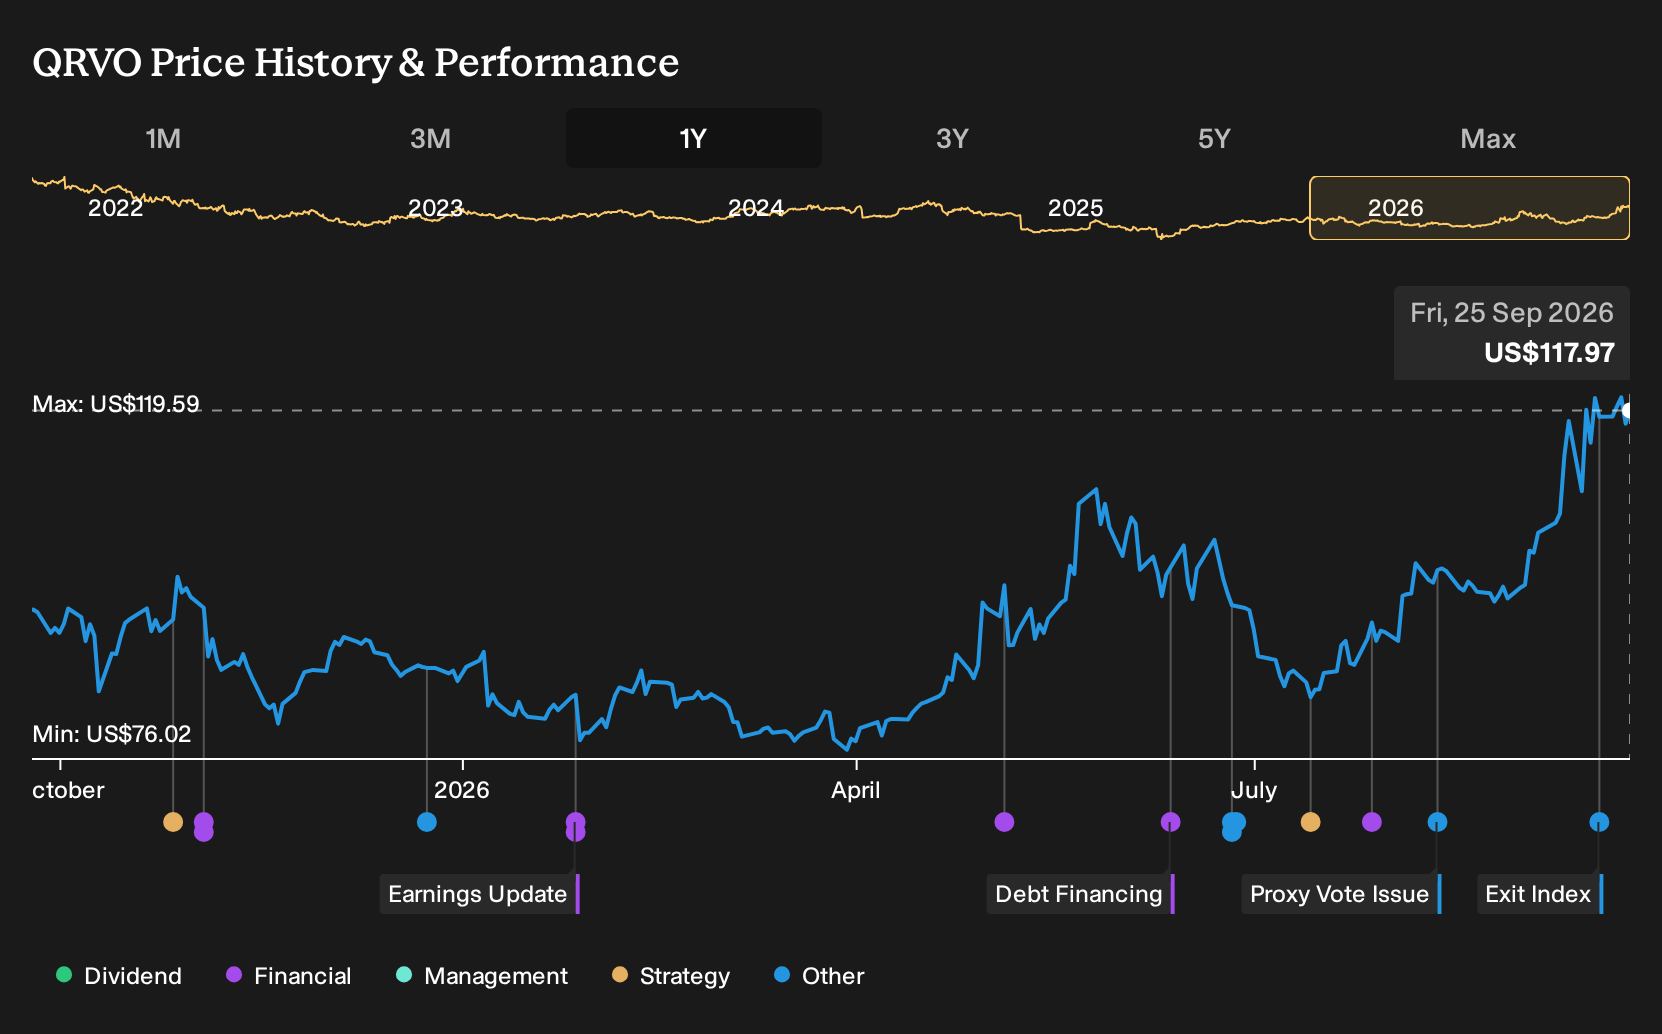
- Qorvo, Inc. was removed from the PHLX Semiconductor Sector Index on 18 September 2026, reflecting a change in that benchmark’s semiconductor roster.
- The removal highlights how Qorvo’s role within benchmarked semiconductor portfolios can shift, with potential implications for index-linked ownership and liquidity.
- We will examine how Qorvo's investment narrative around diversification and margins is tested by its recent removal from the PHLX index.
Scan how other semiconductor plays are handling index changes and capital flows by reviewing the 32 high quality undervalued stocks, which may be positioned for stronger benchmark support over time.
Qorvo Investment Narrative Recap
To own Qorvo, you need to be comfortable with a focused RF business that is trying to shift its center of gravity toward higher margin segments such as defense, infrastructure, and premium smartphones. The key near term catalyst remains execution on that diversification, including content gains in 5G, Wi-Fi 7 and emerging IoT use cases, while keeping cost discipline intact.
The biggest operational risk is still customer and product concentration, particularly with one buyer at 41% of revenue and the ongoing exit from low margin Android 5G. Removal from the PHLX Semiconductor Sector Index may influence some flows, but it does not change these core business drivers in a material way.
There are no fresh operational announcements tied directly to the PHLX removal. The most relevant reference point remains Qorvo’s previously outlined plan to consolidate manufacturing and exit lower margin Android content. That footprint reshaping connects closely to the index story because it influences how the market views the quality and durability of earnings.
For catalysts, the consolidation plan, closure of certain sites and relocation of SAW filter production are central. Clean execution could allow the business to support higher margins and a more balanced mix across HPA, CSG and ACG over time. By contrast, delays, cost overruns or product disruptions could amplify the concentration and earnings quality risks that investors are already watching.
Qorvo consensus expectations behind the index story
The analyst playbook around Qorvo is clear enough on the numbers, even if the PHLX removal has grabbed the headlines. Consensus assumes that revenue grows by 2.5% a year over the next few years, with earnings today at US$339.0 million stepping up to US$597.6 million by 2029 as margins move from 9.2% to 15.1%.
That forecast implies earnings need to rise by about US$258.6 million from current levels, which is close to a 1.8x move on today's profit base. Forecasts are tightly clustered, so the story investors are being asked to underwrite is relatively well defined rather than a wide guessing range around Qorvo's future.
On the top line, analysts are effectively tying Qorvo's execution on higher margin RF content and manufacturing consolidation to a 2029 revenue figure of US$4.0b. The same models that support that US$4.0b and US$597.6 million profile are also assuming a P/E of 16.2x in 2029, down from 22.7x today and well below the 65.3x multiple quoted for the broader US semiconductor peer group.
Price targets cluster around US$91.46 per share, compared with a spot price of US$87.13, with the most optimistic analyst at US$120.0 and the lowest at US$66.0. That relatively tight gap between current trading levels and the consensus target suggests analysts are not treating the PHLX index exit as a thesis breaker for Qorvo. Instead, they appear to frame it as a capital flows event layered on top of an earnings and margin story that still rests on the same set of 2029 assumptions.
Qorvo's narrative projects US$4.0b revenue and US$597.6 million earnings by 2029. This calls for 2.5% yearly revenue growth and an earnings increase of about US$258.6 million from the current US$339.0 million base.
Uncover why Qorvo's fair value indicates a 22% potential downside to its current price, representing a premium that may not hold.
Exploring Other Perspectives
The bearish narrative around Qorvo leans hard on customer in sourcing as the key risk. The lowest analysts were already assuming a flatter top line near US$3.5b by 2029 and earnings of about US$541.5 million before this index exit. You should treat today’s removal as a fresh data point that could either reinforce or weaken those views, and compare several narratives before deciding what feels reasonable to you.
Explore 3 other Qorvo fair value estimates, including one that suggests as much as 26% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Qorvo research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qorvo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qorvo's overall financial health at a glance.
Looking For More Ideas Beyond Qorvo?
If the Qorvo story has sharpened your thinking about risk, valuation and future potential, it can be useful to line it up against a broader watchlist of candidates that fit clear, rules based criteria. The Simply Wall St Screener lets you shift from reacting to headlines to filtering for stocks that match the kind of quality, resilience or income profile you want to focus on next.
- For investors who care most about resilient balance sheets and solid fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can help you narrow the field to financially sturdier businesses.
- If downside risk control matters more to you than chasing the highest upside, scan through a 30 resilient stocks with low risk scores and concentrate on companies with more measured risk profiles.
- Prefer to fish where fewer people are looking, but still want fundamental strength, then cast a wider net across a 16 high quality undiscovered gems that might deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com