
Blue Bell Launch Could Be A Big Test For Kontoor Brands Stock
- Kontoor Brands, through its Wrangler label, recently introduced the premium Blue Bell Collection, a limited-run capsule featuring archival western silhouettes reworked with raw Japanese selvedge denim, full-grain suede, plush shearling, and prices between $399.99 and $1,399.99.
- This move pushes Kontoor Brands further into premium heritage apparel, where higher unit economics, a focus on craftsmanship, and collector appeal can reshape how its core Wrangler franchise competes for wallet share.
- We will now examine how Kontoor Brands' investment narrative could be influenced by Wrangler's new premium Blue Bell capsule collection launch.
Kontoor Brands Investment Narrative Recap
For Kontoor Brands, the core belief is that heritage labels like Wrangler and Lee can still earn their place in modern wardrobes through product refreshes, better mix, and stronger direct engagement. The near term story is about protecting earnings while analysts expect revenue to decline each year, set against a backdrop of higher debt and an uneven dividend track record.
The key catalyst many shareholders watch is execution on product elevation and digital growth, which ties directly to margin resilience. The biggest risk remains that core denim volumes soften faster than Kontoor Brands can grow premium capsules or newer channels. The recent announcements do not materially change that near term equation.
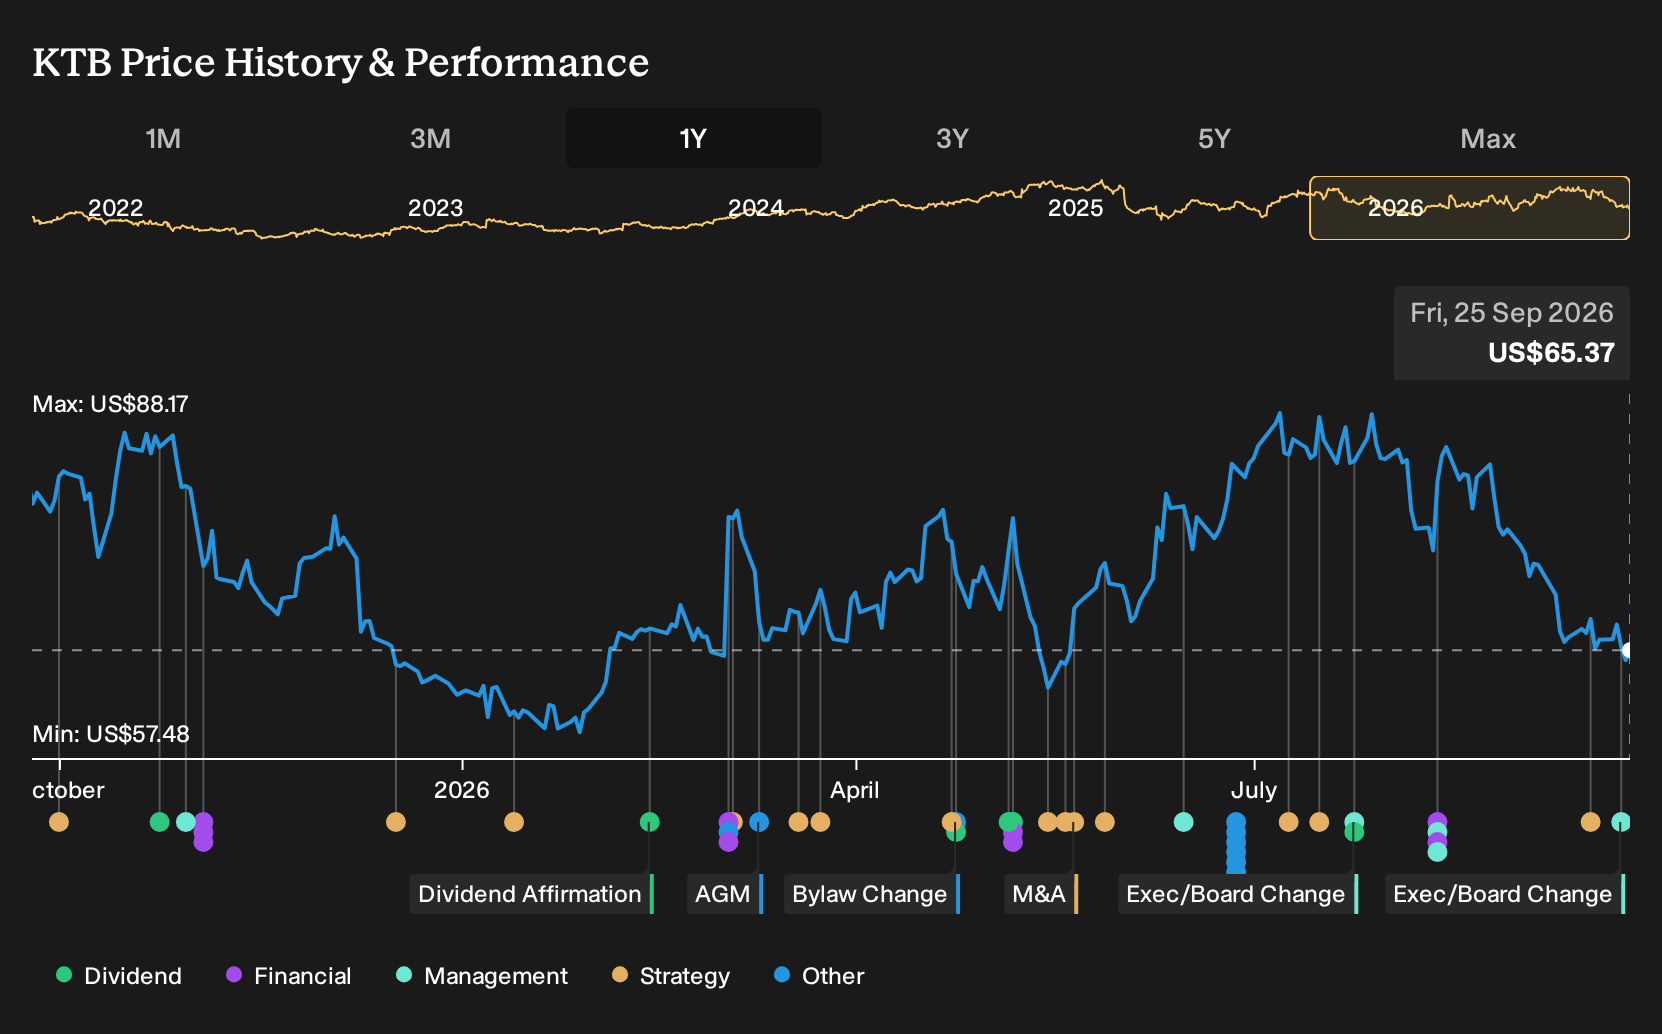
The board refresh on 23 September 2026 looks most relevant here. Kontoor Brands added Jamie Caulfield, former PepsiCo CFO, and Michael Skipworth, Wingstop CEO, to the board, with both joining the Audit Committee and Caulfield also on Nominating & Governance. This brings fresh finance and operator experience into oversight while analysts are split on medium term earnings paths.
For you as an investor, the question is whether a more seasoned board can help management balance premium initiatives like Blue Bell, the Helly Hansen integration, and digital investment against high leverage and cost pressures. Better committee depth may support capital allocation and risk management, but execution on product, channel mix, and international growth still drives the central catalysts.
Kontoor Brands' narrative projects US$2.7b revenue and US$393.2m earnings by 2029. This assumes revenue declines of 7.7% per year and an increase in earnings of about US$116.6m from current earnings of US$276.6m.
Discover why Kontoor Brands' fair value points to a 47% potential upside from its current price, a gap that could close quickly.
Exploring Other Perspectives
For Kontoor Brands, the most optimistic analysts hang their hat on a different catalyst. They lean into Helly Hansen and Project Jeanius efficiencies, with some expecting about US$2.9b of revenue and US$392.0m of earnings by 2029. That is far more upbeat than consensus, and both views were set before the board and Blue Bell news, so opinions may evolve.
Explore 3 other Kontoor Brands fair value estimates, including one that suggests potential upside of as much as 72% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kontoor Brands research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kontoor Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Kontoor Brands' overall financial position at a glance.
Looking For More Investment Ideas Beyond Kontoor Brands?
If the Kontoor Brands story has sharpened your thinking about quality, pricing power, and balance sheet strength, it can be useful to compare it with other listed businesses on those same dimensions. The Simply Wall St Screener lets you quickly filter the market by fundamentals so you can build a watchlist that matches your own risk tolerance and income needs.
- For investors who want potential value with quality fundamentals, scan a focused set of 16 high quality undiscovered gems that already clear key financial hurdles.
- If resilience matters more than rapid growth, filter for companies with steadier profiles using a 30 resilient stocks with low risk scores that prioritizes lower risk scores.
- Income seekers can zero in on cash return potential by reviewing a curated group of 8 dividend fortresses with yields above 5%.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com