
F5 (FFIV) Following Its Q3 Beat And Outlook Lift, Is The Valuation Already Priced In?
F5 (FFIV) returned to investor watchlists after reporting Q3 2026 revenue and adjusted EPS ahead of expectations, prompting management to lift its full year revenue growth outlook once again.
The Q3 surprise lands on top of strong price momentum, with F5’s share price up 10.88% over the past month and 72.65% year to date, while total shareholder return of 36.38% over one year and 174.95% over three years points to sustained enthusiasm that recent product updates and partnerships are helping to extend, rather than reverse.
Scan beyond F5 and line up other security and application-delivery players showing strong momentum with our hand picked 87 AI infrastructure stocks.
After a near-vertical run and a revenue outlook that keeps inching higher, F5 now asks a harder question of buyers. Does the current valuation still compensate you for the risks from here?
Most Popular Narrative: 2% Overvalued
F5 closed at $443.06, while the most followed valuation narrative pegs fair value at $436.10. This frames the stock as slightly ahead of that estimate and emphasizes specific growth drivers to explain the gap.
Expanding AI related use cases, including roughly US$50 million of direct AI bookings in the first half of FY26 and multi million dollar deals around AI data delivery, runtime security and AI factory load balancing, together with indirect AI driven traffic on existing estates, can support continued growth in systems and security revenue.
See why 18 investors see F5 as 2% overvalued.
Result: Fair Value of $436.10 (OVERVALUED)
Still, the F5 story can wobble if recurring revenue stays sluggish or if higher component costs keep squeezing the rich gross margin profile that analysts are banking on.
Find out about the key risks to this F5 narrative.
Another View On F5’s Valuation
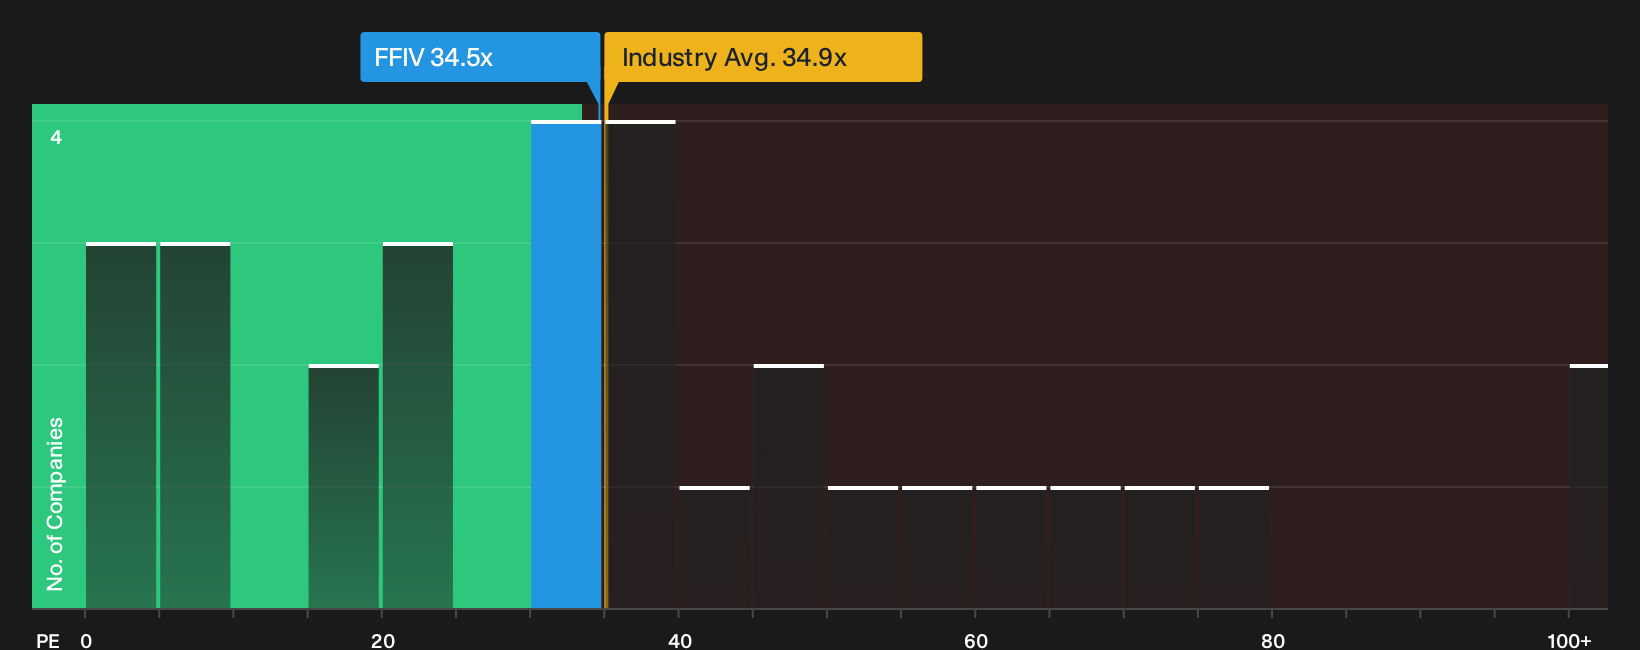
On simple P/E maths, F5 looks more expensive than its own fair ratio suggests. The stock trades around 34.5x earnings, while the estimated fair ratio sits closer to 28x. That gap points to less margin for error if earnings or sentiment cool.
The same P/E comparison paints a mixed picture. F5’s 34.5x multiple is slightly below the wider US Communications sector at 35x and well under the 52.3x peer average. This limits how stretched it looks against alternatives and raises the question of whether the price leans rich or just fully loaded for its quality story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on F5 so far. If that tension between enthusiasm and caution feels familiar, move quickly and consider both perspectives by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond F5?
If F5 has you rethinking your watchlist, do not stop with a single ticker. Spread your research so one story does not dominate your whole plan.
- Target resilience first by scanning companies that pass strict balance sheet and fundamentals checks with our list of solid balance sheet and fundamentals (24 results).
- Hunt for value opportunities by reviewing a curated 32 high quality undervalued stocks before enthusiasm in the market prices them more fully.
- Prioritize sleep at night potential by focusing on a 30 resilient stocks with low risk scores that filters for businesses with more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com