
Is Kobe Steel (TSE:5406) Undervalued After Its Malta Alliance?
Why Kobe Steel's Malta alliance matters for investors
Kobe Steel (TSE:5406) is back in focus after Malta Inc. announced a capital and business alliance that incorporates Kobe Steel into its investor group and technology roadmap.
The partnership links Malta's ultra high temperature heat pump systems with Kobe Steel's compression expertise, targeting industrial energy costs, process reliability, decarbonization, waste heat recovery and storage. These initiatives are tied to Kobe Steel's "KOBELCO-X" green transformation plan.
Recent trading has been quietly constructive for Kobe Steel, with the share price at ¥2,080 and a 90-day share price return of 10.87%, even though the year-to-date share price is down 0.93%. That near term momentum sits alongside a 1-year total shareholder return of 19.38% and a very large 5-year total shareholder return approaching 3x, which suggests the Malta alliance is landing on a stock where long haul holders have already seen substantial value creation priced in over time.
Scan other industrial decarbonization plays showing similar momentum by reviewing the hand picked 19 nuclear energy infrastructure stocks alongside Kobe Steel's latest move with Malta.
Kobe Steel now has Malta in its corner and a long run of strong multi year returns behind it. The valuation question is whether that history already captures most of the upside or still leaves meaningful room ahead.
Price-to-Earnings of 12.2x for Kobe Steel: Is it justified?
Kobe Steel trades on a P/E of 12.2x at a share price of ¥2,080, which puts the stock on a lower multiple than the broader JP market but slightly above the Metals and Mining group.
The P/E ratio compares the current share price to earnings per share and gives a shorthand view of how much investors are paying for each unit of profit. For a diversified industrials and materials business like Kobe Steel, this yardstick connects directly to how the market weighs its profit cycle, balance sheet risks and exposure to projects such as Malta's heat pump build out.
Against peers, the picture is mixed. The 12.2x P/E sits below the wider JP market at 14.1x, which points to more cautious expectations, yet it is higher than the JP Metals and Mining average of 11.2x, which signals investors are paying a premium relative to the sector. That sits alongside an estimated fair P/E of 16.2x, so the current multiple is clearly below the level the fair ratio suggests the market could move toward if sentiment or fundamentals line up.
Explore the SWS fair ratio for Kobe Steel.
Result: Preferred multiple of 12.2x P/E (ABOUT RIGHT)
Still, the narrative can break if Kobe Steel faces execution setbacks on Malta's heat projects, or if its sizable construction machinery and steel exposure encounters cyclical headwinds.
Find out about the key risks to this Kobe Steel narrative.
Another view on Kobe Steel's value
The P/E story leans toward Kobe Steel looking reasonable, yet the SWS DCF model paints a tougher picture. At ¥2,080, the share price sits above an estimated future cash flow value of ¥1,464.46, which implies the stock could be overvalued on that lens. Which signal do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
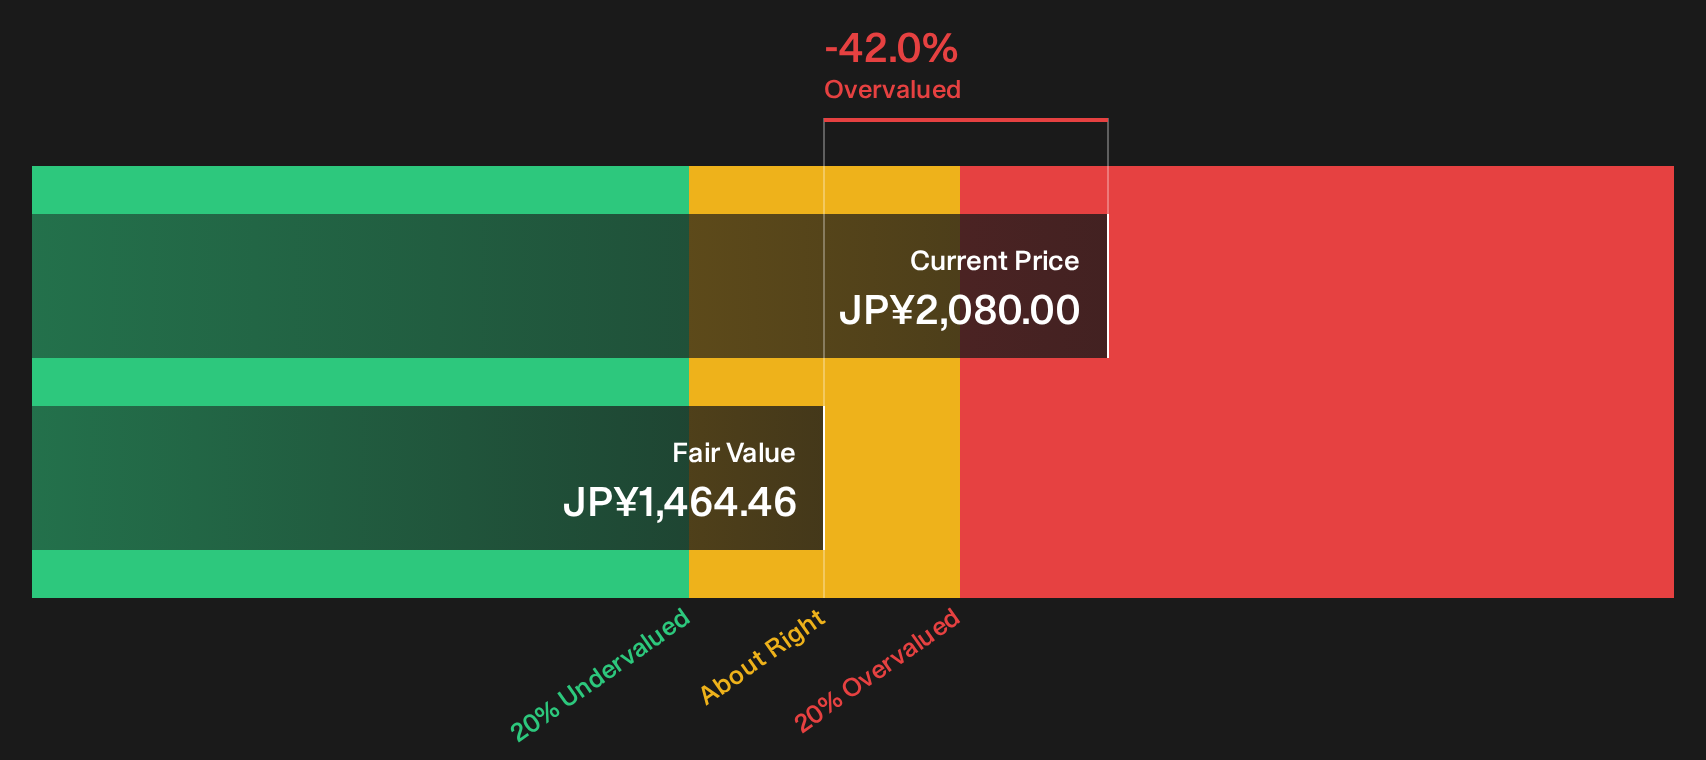
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kobe Steel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Kobe Steel's story around Malta, valuation signals and sentiment cuts both ways, so move quickly, review the full data set yourself and weigh the 2 key rewards and 3 important warning signs.
Looking for more Kobe Steel sized ideas?
If Kobe Steel has you rethinking your watchlist, do not stop here. The next opportunity could already be screening clean numbers while you wait.
- Target mispriced quality and see which companies combine strong fundamentals with room for re rating via the 18 high quality undervalued stocks.
- Build a steadier income stream by hunting for robust payout profiles through the 14 dividend fortresses.
- Prioritise resilience and sleep easier at night by focusing on companies flagged in the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com