
Sumitomo (TSE:8053) Draws Fresh Interest On Buy Upgrade And Value Debate
Analyst upgrade puts Sumitomo in focus
Analyst optimism has shifted toward Sumitomo (TSE:8053) after a rating upgrade to Buy, which highlighted improving earnings expectations and relatively low P/E, P/B, P/S and P/CF ratios compared with the broader industry.
The latest move puts Sumitomo’s share price at ¥1,798, after a 1-day share price return of 1.67% and a 90-day share price return of 15.98%. The 1-year total shareholder return of 68.89% and 5-year total shareholder return of about 4.7x suggest momentum has been building over multiple timeframes as investors respond to the upgraded rating and value-focused commentary.
Compare Sumitomo’s value-focused re‑rating with other potential opportunities, and scan a curated 18 high quality undervalued stocks that traders are watching for the next valuation reset.
Sumitomo now has a bullish rating and a strong multi segment business behind it. The real question is whether that story is already fully reflected in a ¥1,798 share price.
Preferred P/E of 13.8x for Sumitomo: Is it justified?
On valuation, Sumitomo is being framed as good value relative to some peers, even though one industry check flags the stock as expensive. The share price of ¥1,798 anchors that debate, so the P/E of 13.8x becomes the key number to watch.
The P/E ratio compares the price investors pay today with the earnings generated over the past year. For a diversified trading group like Sumitomo, which spans steel, automotive, mineral resources, chemicals, consumer businesses and more, that figure helps show how much the market is paying for each unit of profit across a broad earnings base.
Relative to the JP Trade Distributors industry average of 10.8x, the stock is described as expensive, which suggests the market is willing to pay a premium compared to sector peers. In contrast, against a peer average of 15.8x and an estimated fair P/E of 22.7x, the same 13.8x is framed as good value, indicating the current multiple sits well below where some models suggest valuations could shift if sentiment or fundamentals change.
Explore the SWS fair ratio for Sumitomo.
Result: Price-to-Earnings of 13.8x (ABOUT RIGHT)
Still, Sumitomo’s broad mix across steel, autos and resources ties the story to swings in global demand and commodity pricing that could quickly shift sentiment.
Find out about the key risks to this Sumitomo narrative.
Another view on Sumitomo’s value
P/E tells one story for Sumitomo, but the SWS DCF model tells another. On that cash flow view, the shares at ¥1,798 sit about 16.8% below an estimated value of ¥2,162.34, which suggests the market price could be lagging the underlying cash generation.
That gap can close in different ways. The question for you is whether the path from here is driven more by earnings multiples or by the cash flows the business is expected to produce.
Look into how the SWS DCF model arrives at its fair value.
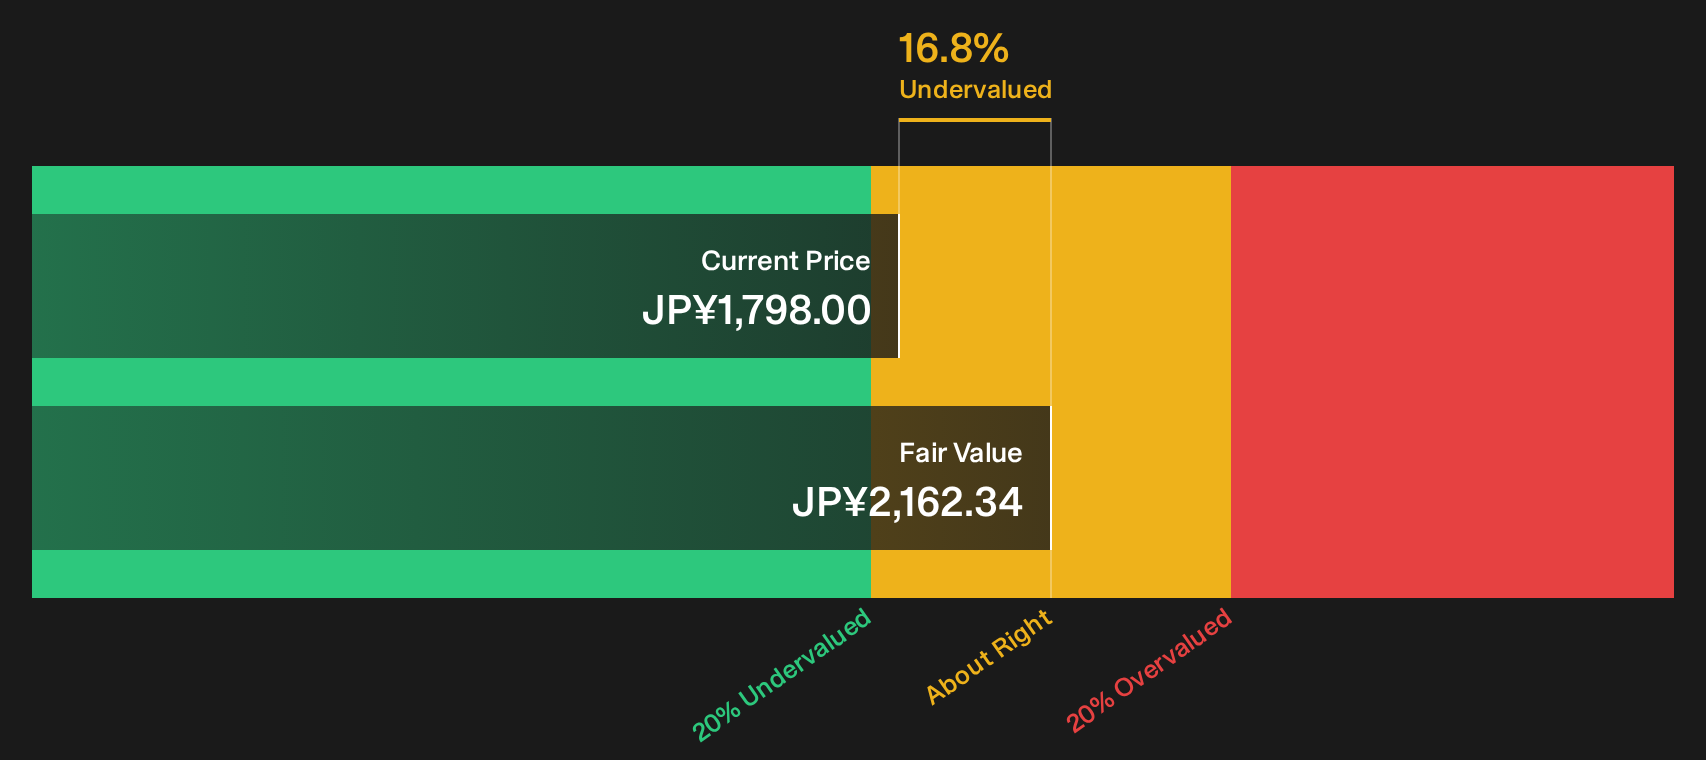
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sumitomo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sumitomo can be a strength if you use them well. Move quickly on the data, weigh both sides, and ground your own view in the 3 key rewards and 2 important warning signs.
Looking for more Sumitomo-sized opportunities?
If Sumitomo has sharpened your focus on value, do not stop here. A broader watchlist gives you options when sentiment, pricing or quality shifts.
- Target potential mispricings by scanning companies that combine solid fundamentals with compressed valuations using the 18 high quality undervalued stocks.
- Build a steadier income stream by assessing businesses with robust payouts in the 14 dividend fortresses.
- Prioritise resilience by filtering for strong balance sheets and durable financial profiles through the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com