
Why Oceaneering International (OII) Is Back In The Spotlight
Oceaneering International’s ROV exposure comes into focus
Fresh coverage of the global remote operated vehicle market has put Oceaneering International (OII) back in the spotlight, as analysts highlight projected industry expansion supported by offshore energy investment and advanced subsea technology demand.
At a share price of US$46.26, Oceaneering International has seen short term momentum cool, with the 30 day share price return down 6.8%, even as the 90 day share price return is up 15.6% and the 1 year total shareholder return sits at 80.3%. This signals that investors are reassessing how much future ROV demand is already reflected in the stock.
Compare Oceaneering International’s subsea robotics story with a hand picked line up of robotics and automation peers in the 93 robotics and automation stocks to see how the theme plays out across the sector.
Oceaneering International now trades almost in line with analyst targets, even after a sharp run and a recent pause. Is that a reasonable safety margin, or a sign the market is underpricing its ROV exposure?
Most Popular Narrative: 1% Overvalued
Oceaneering International’s most followed valuation narrative now pegs fair value at $46.00, almost level with the last close at $46.26. This puts the focus squarely on how durable the ROV and offshore upcycle really is.
The ongoing global energy transition and intensifying decarbonization efforts continue to limit new offshore oil & gas developments, which threatens Oceaneering's long-term project backlog and could ultimately reduce future revenue growth as the addressable market gradually contracts. Investors may be overestimating the durability of subsea offshore demand, as advancements in the cost and scale of renewable energy sources could accelerate a decline in demand for deepwater oilfield services and subsea solutions, dampening the relevance and growth potential of Oceaneering's legacy offerings, and putting long-term revenue at risk.
See why 12 investors see Oceaneering International as 1% overvalued.
Result: Fair Value of $46.00 (OVERVALUED)
Still, if Oceaneering International’s aerospace and defense work scales faster, or if high margin connectors and robotics gain traction, that could pressure the cautious valuation story.
Find out about the key risks to this Oceaneering International narrative.
Another View on Oceaneering International’s value
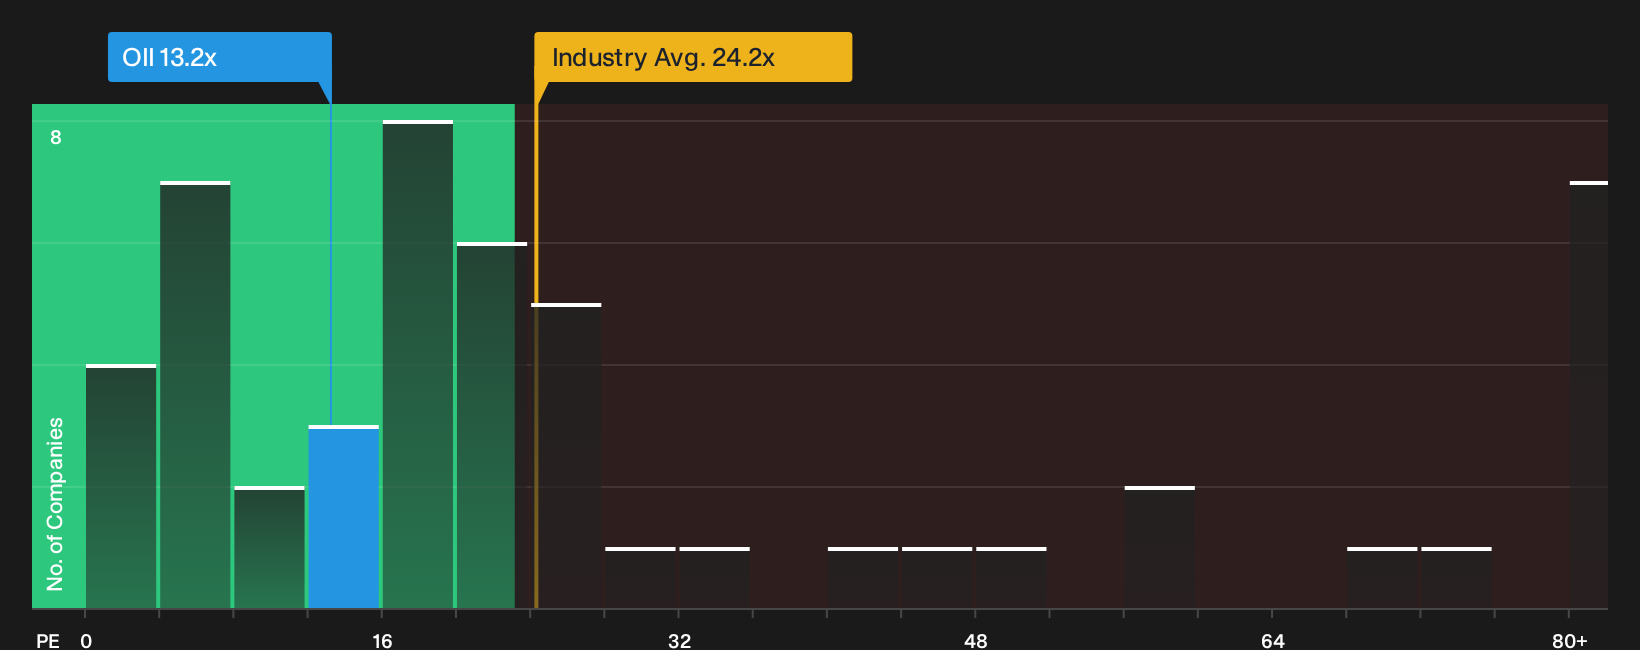
That cautious fair value narrative leans heavily on long term earnings forecasts and future P/E assumptions. The market today is also weighing a simpler yardstick. At a P/E of 13.2x, Oceaneering International trades well below the US Energy Services industry on 24x and its peer group on 63.6x, yet above a fair ratio estimate of 6.6x that the market could eventually move toward.
For an investor, that spread highlights two very different paths: either the stock converges upward toward richer sector multiples, or the valuation backs off toward the fair ratio. Which scenario do you think current ROV and defense momentum really supports?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Oceaneering International’s valuation story are clear enough, so treat this as your cue to move fast, interrogate the numbers, and pressure test the narrative for yourself. To weigh the upside optimism against the concerns already on the radar, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Oceaneering International?
Do not stop at one story. Use the Simply Wall St screener to compare themes, test your thesis, and keep fresh opportunities on your radar before others notice.
- Hunt for mispriced quality by scanning the market for companies that look cheaper than their fundamentals suggest with the 32 high quality undervalued stocks.
- Build a sturdier portfolio by focusing on businesses with stronger finances when you work through the list of solid balance sheet and fundamentals (24 results).
- Spot potential future standouts early by reviewing a curated pool of underfollowed opportunities through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com