
Kulicke And Soffa Industries (KLIC) Profitability Turnaround Keeps Valuation In Focus
Fresh commentary from Tributary Capital Management has put Kulicke and Soffa Industries (KLIC) back on investor screens, citing an inflection in profitability, stronger AI packaging demand, and rising hedge fund ownership.
Recent trading has been volatile. Kulicke and Soffa Industries has a 7 day share price return of 9.67% and a year to date share price return of 88.58%. However, the 90 day share price return declined 27.18% as investors reassess AI packaging potential and changing risk views around profitability inflection.
Compare Kulicke and Soffa Industries with a curated group of peers benefiting from AI-related demand by scanning the 87 AI infrastructure stocks for potential next-stage beneficiaries of chip packaging and compute buildout.
Kulicke and Soffa Industries now sits between a bullish story built on profitability inflection and AI packaging, and a bearish read on recent share price swings. Which case do the current valuation markers lean toward?
Most Popular Narrative: 14.5% Undervalued
The most followed valuation narrative places Kulicke and Soffa Industries' fair value at about $106.67, compared with the latest close of $91.18. That gap reflects a view that the Advanced Solutions build out and packaging tools could lift earnings power over the coming years.
Management is preparing for a production ramp in Fluxless thermocompression and vertical wire into fiscal 2026, yet both are still in early phases with first HBM system shipments and initial vertical wire qualifications. Any delay or slower adoption in high bandwidth memory or on device AI could pressure the anticipated contribution to revenue growth and limit margin expansion.
See why 6 investors see Kulicke and Soffa Industries as 15% undervalued.
The narrative uses a discount rate of 10.85% to bring those long term cash flows back to today, which is a relatively robust hurdle for a hardware supplier tied to semiconductor cycles. Analysts in that framework are also pairing a revenue growth outlook with a higher profit margin profile and a future P/E that is lower than current sector levels. Together, these factors help support the fair value estimate of $106.67 against Kulicke and Soffa Industries' current share price.
Result: Fair Value of $106.67 (UNDERVALUED)
Still, the bullish Kulicke and Soffa Industries case depends on smooth ramps in thermocompression and advanced packaging, where slower customer qualifications or lumpier orders could quickly challenge these valuation assumptions.
Find out about the key risks to this Kulicke and Soffa Industries narrative.
Another View: Kulicke and Soffa Industries Through The P/E Lens
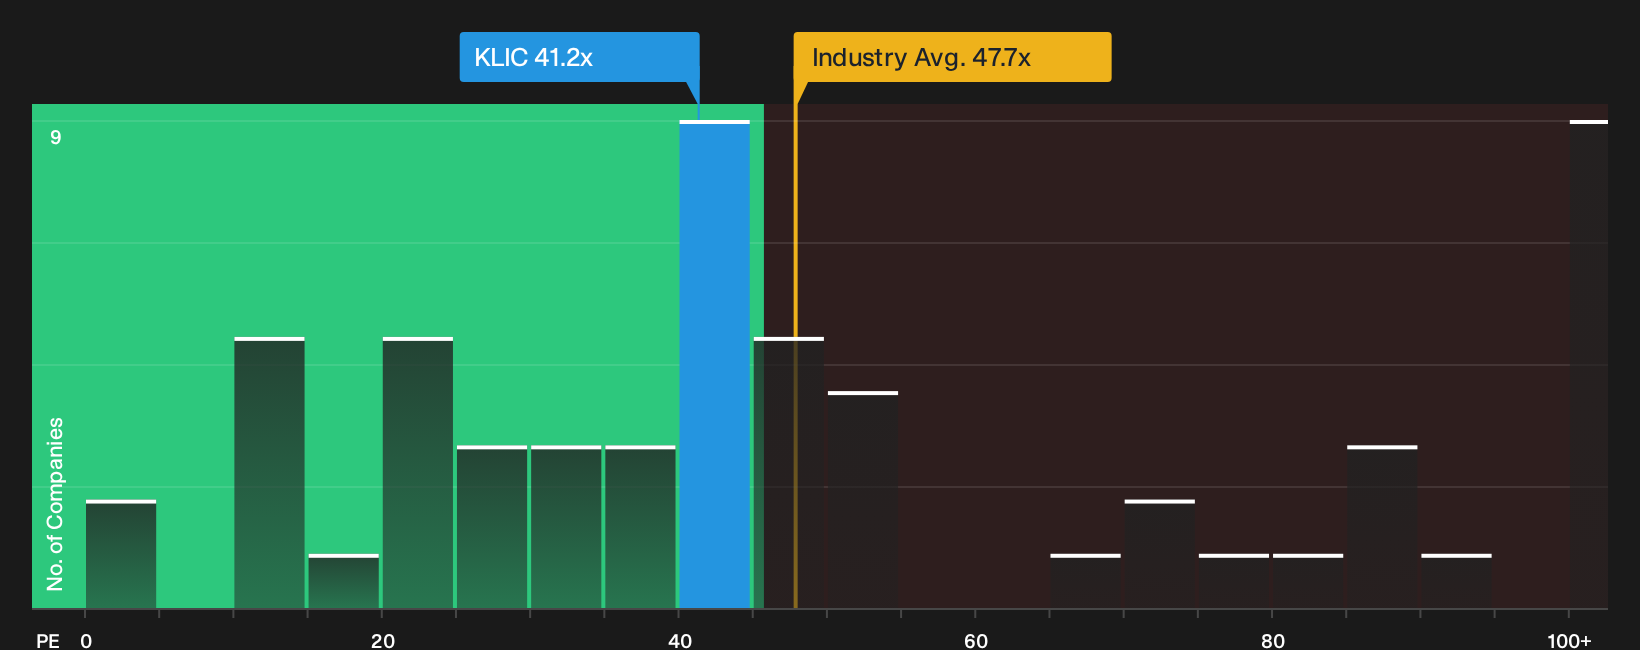
A very different picture of Kulicke and Soffa Industries appears when the focus shifts from fair value models to plain P/E math. The stock trades on 41.2x earnings, which is cheaper than the US Semiconductor industry at 47.3x and below peers at 59.8x, yet above its own fair ratio of 35.4x. That mix points to some valuation risk if the market leans closer to the fair ratio instead of peer levels. Which anchor do you think is more realistic?
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Kulicke and Soffa Industries valuation and risk reward profile can be healthy, as long as you use them as prompts rather than conclusions. Act quickly, stress test both the bullish and cautious cases against the data, then weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Kulicke and Soffa Industries?
Do not stop with a single ticker. Use high quality screeners to surface fresh opportunities that match your risk appetite and keep your watchlist working harder.
- Target resilient cash generators with strong finances by scanning a list of solid balance sheet and fundamentals (24 results) that filters for firms combining sturdy balance sheets with solid fundamentals.
- Hunt for potential mispricings by reviewing a 32 high quality undervalued stocks that focuses on quality businesses trading below their estimated worth.
- Lock in income ideas by checking a 8 dividend fortresses that highlights companies offering higher yields while aiming to maintain payout strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com