
McDonald's (MCD) Lifts Dividend As The Market Questions Whether The Stock Is Fully Valued
McDonald's (MCD) just raised its quarterly dividend to $1.93 per share, a 4% bump that takes the annual payout to $7.72. That move hits investors’ radar immediately.
McDonald's shareholders have watched the stock give up ground this year, with the share price down 22.01% year to date and about 11.40% over the past month, even as management laid out its McDonald's > NEXT plan, announced an $8.5b restaurant overhaul, and moved to refresh the menu with higher protein options. That short term share price pressure contrasts with a positive 5 year total shareholder return of 9.38%, which indicates that momentum has cooled recently even though longer term holders still sit on gains.
Compare how McDonald's dividend move stacks up against other mature, cash-generative businesses by scanning our hand picked 32 high quality undervalued stocks for potential income and value ideas.
McDonald's just lifted its payout while the share price has been sliding, which puts you at a crossroads. Should you lean into the reset now, or wait to see if the market pushes valuations even lower first?
Most Popular Narrative: 1% Overvalued
McDonald's last closed at $236.50, while the most followed narrative pegs fair value at $233.67 using an 8.52% discount rate. This puts that framework almost in line with where the market is pricing the stock after the recent sell off.
So, in summary, I forecast that McDonald's will expand its margins through an increase in efficiency of its operations (probably with the aid of AI) but will also see its revenue growth slow down, probably below the economy growth rate given the maturity of the business and the decrease of consumer spending.
See why 44 investors see McDonald's as 1% overvalued.
Result: Fair Value of $233.67 (ABOUT RIGHT)
Still, McDonald's narrative could be knocked off course if consumer health preferences tighten further or if its large reinvestment program delivers weaker returns than expected.
Find out about the key risks to this McDonald's narrative.
Another View On McDonald's Valuation
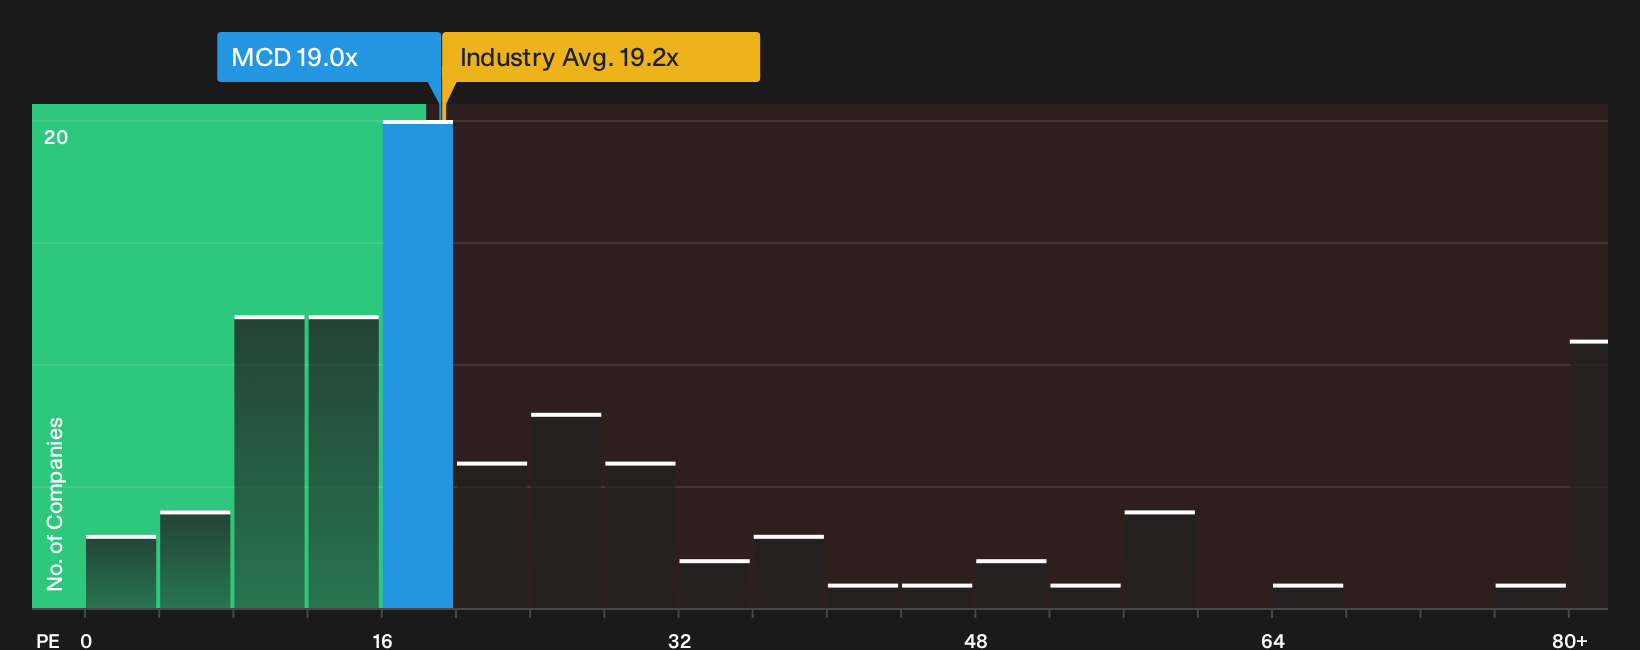
That narrative led fair value of $233.67 leans on detailed owner estimates, but the market is also quietly sending a different signal through the P/E ratio. McDonald's trades on 19x earnings, while the wider US Hospitality group averages 19.2x and the fair ratio points closer to 25.5x.
In practice, that means the stock is priced slightly below peers and well below where the fair ratio suggests the multiple could drift over time. This reduces valuation risk for holders but also raises a question: is the narrative right to call McDonald's about fully priced, or is the market implying more headroom in the earnings multiple than that story allows for?
To weigh that gap properly, take a closer look at how the current P/E stacks up against both peers and the fair ratio. Then ask whether your own expectations line up with the numbers by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on McDonald's so far, or leaning one way already? Take a moment to test that gut feeling against the full picture of 6 key rewards and 1 important warning sign.
Looking for more McDonald's sized investment ideas?
Do not stop your work at McDonald's. Broaden your watchlist with fresh ideas sourced directly from data driven screeners that highlight different ways to put capital to work.
- Target dependable income by focusing on companies that screen for resilient payouts and payout ratios using our 8 dividend fortresses.
- Hunt for missed opportunities where strong balance sheets and healthy fundamentals quietly support future options through the list of solid balance sheet and fundamentals (24 results).
- Spot under the radar prospects with solid numbers before the crowd catches on by scanning the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com