
Is Siemens Energy (XTRA:ENR) Cheap Following Its $1.3b Pickering Nuclear Contract?
Why the Pickering contract matters for Siemens Energy stock
Siemens Energy (XTRA:ENR) just picked up fresh attention after its consortium with Aecon secured a $1.3b Turbine Generator Replacement contract at Ontario Power Generation’s Pickering Nuclear Generating Station.
The deal ties Siemens Energy more closely to long-term nuclear refurbishment work that supports Ontario’s clean power goals. This gives investors a concrete project to weigh alongside the company’s broader energy technology portfolio.
Recent trading has been mixed for Siemens Energy, with a 1-day share price return of 0.35% and a 7-day gain of 1.71% set against a 30-day decline of 5.63% and a 90-day drop of 7.35% from the current €142.6 level.
Even with that softer near term momentum, long term holders have seen a very large 3-year total shareholder return above 10x and a 5-year total shareholder return of more than 5x. The 1-year total shareholder return of 45.06% and year-to-date share price return of 16.12% indicate that sentiment has improved as contracts like Pickering highlight demand for Siemens Energy’s infrastructure capabilities.
Spot opportunities beyond Siemens Energy by scanning a curated 40 power grid technology and infrastructure stocks that is positioned to benefit from long-term demand for grid and nuclear refurbishment projects.Siemens Energy now trades at a clear discount to both analyst targets and some intrinsic value estimates after the Pickering news lift. Is that gap a sign of warranted caution, or an opening the market is mispricing?
Most Popular Narrative: 28% Undervalued
Against the last close at €142.6, the most followed valuation narrative pegs Siemens Energy’s fair value closer to €199. This frames the current discount as a question of execution rather than story quality.
High current backlog and order intake may create the impression of long-term revenue visibility and strong future free cash flow. This overlooks risks like supply chain constraints, capacity bottlenecks, and large working capital requirements to deliver on these orders, which could compress free cash flow and profitability if execution difficulties arise.
See why 119 investors see Siemens Energy as 28% undervalued.
On these narrative assumptions, analysts apply a 7.15% discount rate and arrive at a fair value of about €199 per share, roughly 28% above the current level and noticeably closer to their consensus target of €196.32. That gap reflects a view that Siemens Energy’s €41.8b in revenue and €2.7b in net income are supported by a sizeable order book across gas services, grids, wind and industrial solutions, yet still carry meaningful delivery and policy risk.
For you as an investor, the key question is whether that order backlog, forecast revenue growth of 12.2% per year and expected earnings expansion of 25.8% a year are enough to offset concerns about factors like wind segment volatility, working capital swings and higher risk funding that is fully reliant on external borrowing.
Result: Fair Value of €199.08 (UNDERVALUED)
Still, that upbeat Siemens Energy narrative can crack if supply chain bottlenecks force costly delays or if the Siemens Gamesa wind unit struggles longer than analysts expect.
Find out about the key risks to this Siemens Energy narrative.
Another View on Siemens Energy valuation
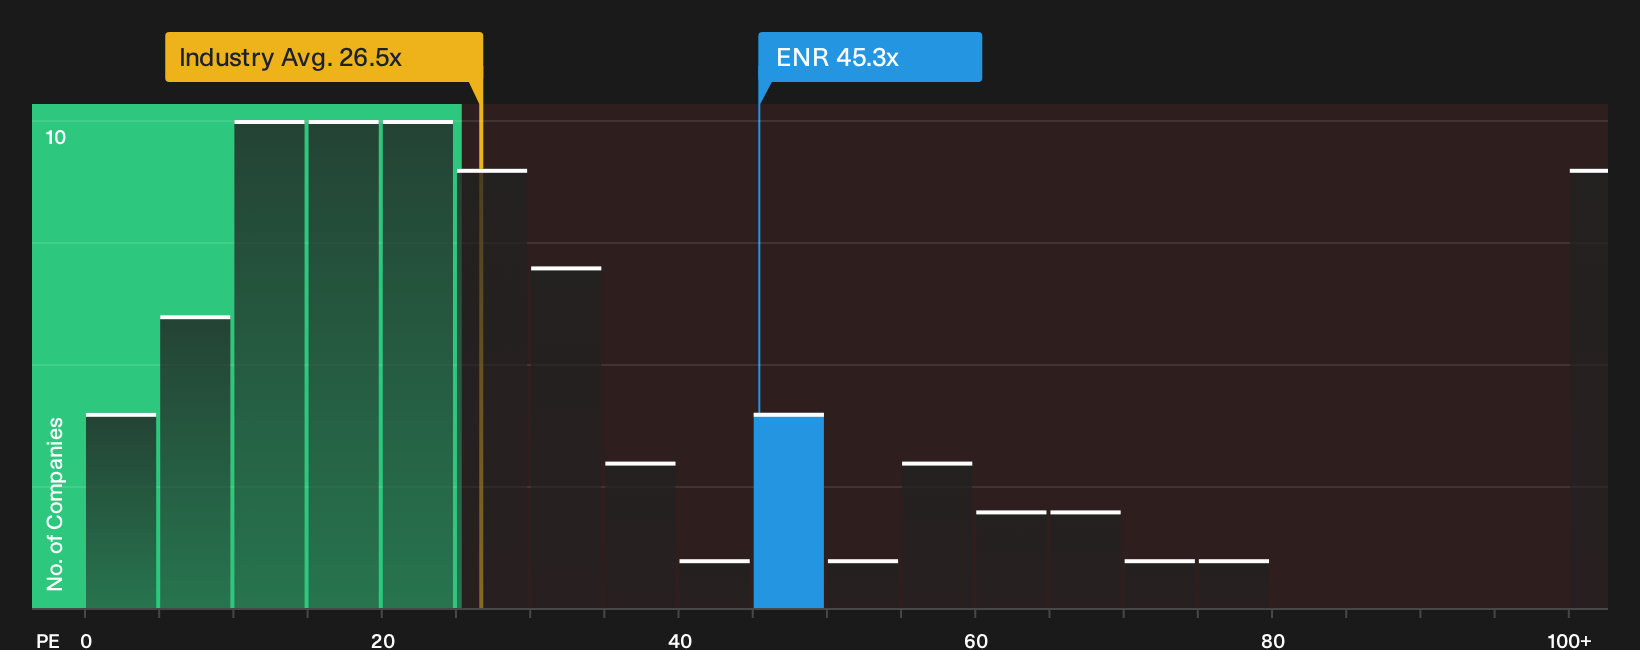
That €199 fair value comes from analysts and a narrative model. A different lens looks at the simple P/E. Siemens Energy trades on about 45.3x earnings versus 26.5x for the wider European Electrical sector and 37.7x for peers, even though the fair ratio sits nearer 46.9x.
So the market prices Siemens Energy above its sector and peer averages, yet roughly in line with that fair ratio. This puts more of the debate on how much valuation risk you are willing to take if growth or margins do not track the current script.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Siemens Energy story feels optimistic, consider acting quickly and reviewing the numbers yourself before sentiment shifts again. To see what is driving the optimism, review the 3 key rewards.
Looking for more investment ideas beyond Siemens Energy?
You do not need to stop with Siemens Energy. Use this momentum to widen your watchlist and test your thesis against other opportunities on the market.
- Target resilient balance sheets and steady fundamentals by reviewing a curated list of solid balance sheet and fundamentals (202 results). This can help you avoid fragile business models before the next shock hits.
- Hunt for mispriced quality by scanning the 182 high quality undervalued stocks. It filters for stronger cash flows and cleaner balance sheets than the market might be recognizing yet.
- Stack potential income streams by reviewing a focused 162 dividend fortresses that is built around higher yields while still keeping financial strength in view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com