
Did Credit Line Extension Just Shift Bunge Global (BG) Investment Narrative?
- Bunge Global and its wholly owned finance subsidiaries recently agreed with creditors to extend three unsecured revolving credit facilities, including a $4,200 million 5-year line and a $3,500 million 3-year facility, by 12 months each.
- The longer maturities on these large revolving facilities give Bunge Global more predictable access to funding for working capital, integration spend and capex, which matters for a business that buys, stores and processes agricultural commodities at scale.
- We now look at how Bunge Global's investment narrative could be influenced by this extension of major revolving credit lines.
Scan how Bunge Global's funding extension compares to other balance sheet focused plays by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
Bunge Global Investment Narrative Recap
Bunge Global asks you to believe that a larger, integrated agribusiness can turn its global footprint in oilseeds, grains and milling into steadier, higher quality earnings over time. The extended revolving credit lines do not change that core thesis. They mostly tidy up funding for day to day working capital, the Viterra integration and ongoing capex.
In the short term, the key swing factor still sits in how quickly processing, crush expansions and specialty products offset weakness in refined oils and merchandising. The biggest risk remains cash generation and leverage. Softer Grain Merchandising and Milling, thin 1.1% net margins and debt that is not well covered by operating cash flow keep financial flexibility in focus.
The credit facility extension connects most clearly to the risk around funding, not to a new growth trigger. Management now has committed access to multi billion dollar liquidity out to 2027, 2029 and 2031, which can help the group handle inventory swings and integration spend without relying on short notice refinancing.
This matters if earnings stay pressured by segment softness or if free cash flow remains tight while large projects ramp. For you as a shareholder or prospective investor, the key question is execution. Can Bunge Global convert the enlarged platform and renewable fuel exposure into stronger returns before higher leverage and uneven merchandising results start to constrain optionality on dividends, buybacks and future investment?
What The Forecasts Assume For Bunge Global
Bunge Global's narrative projects US$95.3b in revenue and US$3.4b in earnings by 2029. That path lines up with analysts building in 1.2% yearly revenue growth and an earnings increase of about US$2.4b from US$1.0b today.
Uncover why Bunge Global's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
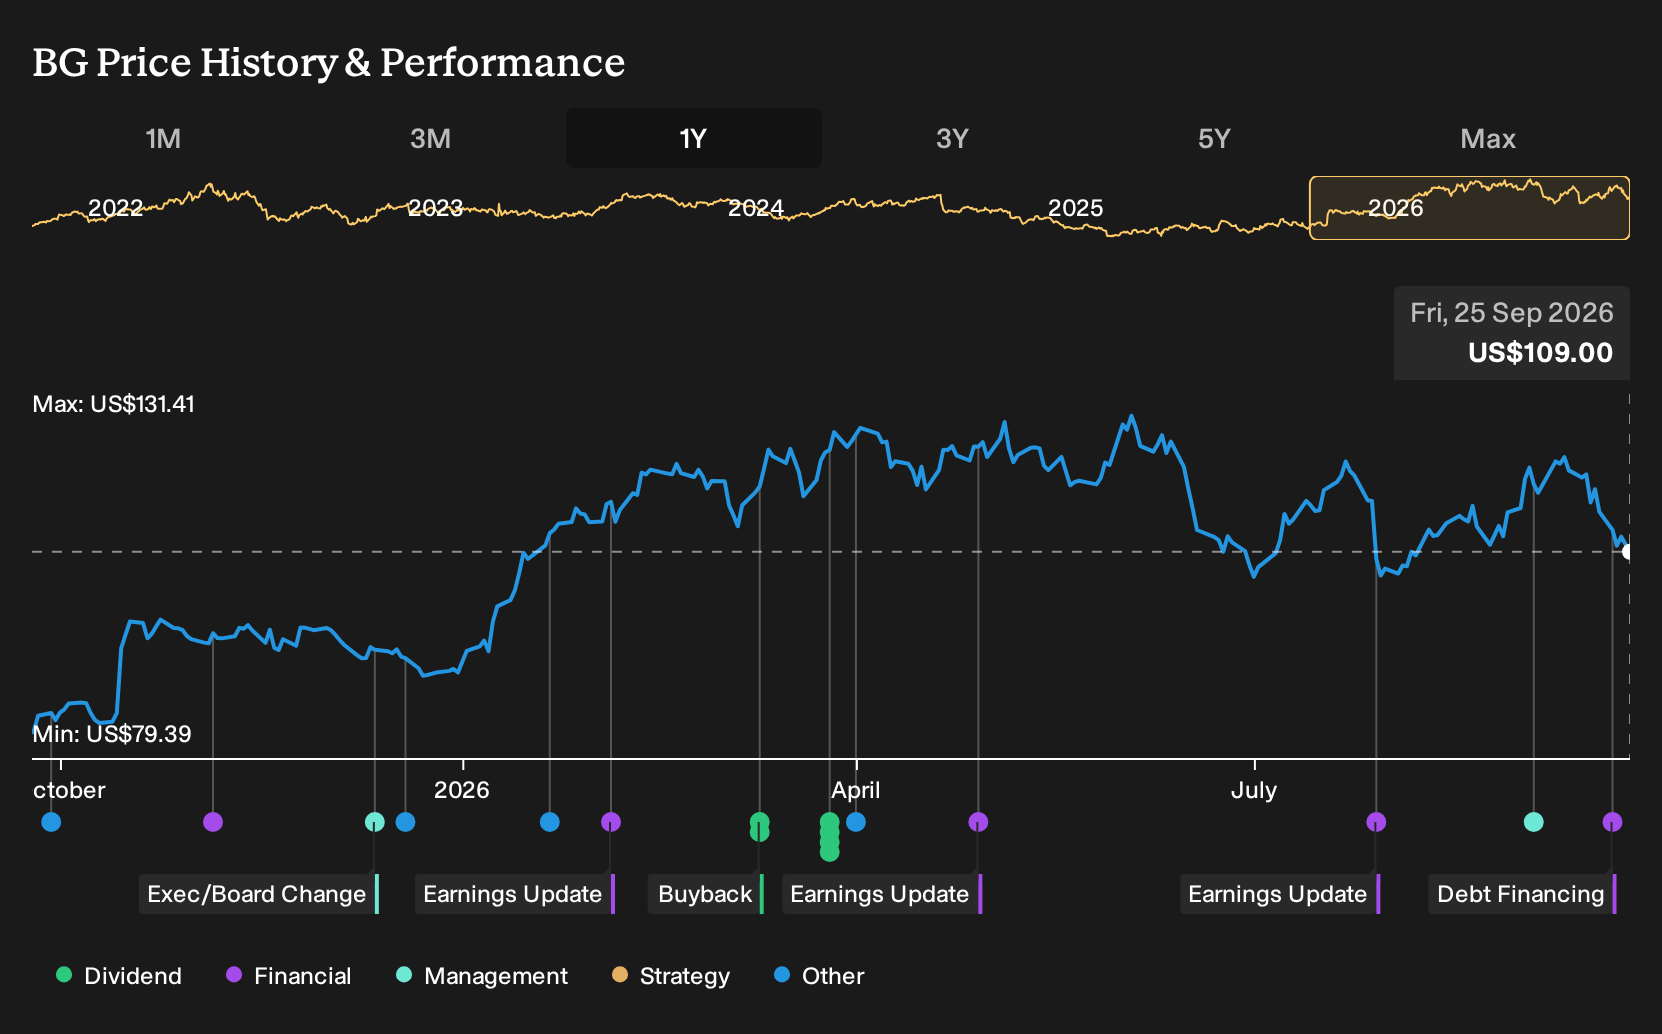
Exploring Other Perspectives
One alternate view puts the Viterra integration risk front and center. You might see the extended credit lines as useful, while the most optimistic analysts were already penciling in about US$97.5b of revenue and US$3.5b of earnings by 2029. Those forecasts came before this funding news, and opinions may shift as the story evolves.
Explore 3 other Bunge Global fair value estimates, including one that suggests as much as 261% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bunge Global research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bunge Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bunge Global's overall financial health at a glance.
Looking For More Bunge Global Style Investment Ideas?
If Bunge Global has you thinking about balance sheet strength, earnings quality and funding flexibility, it can help to widen the lens and compare it with other businesses that share similar traits.
The Simply Wall St Screener lets you scan for stocks with specific financial characteristics that fit your own risk and return preferences. A few angles many investors look at are:
- Target resilience first by reviewing companies that score well on financial strength and conservative funding through the 30 resilient stocks with low risk scores.
- Focus on potential mispricing by scanning for businesses that combine solid fundamentals with room for re rating using the 32 high quality undervalued stocks.
- Prioritise fresh opportunities with sound balance sheets that are not widely followed by institutions through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com