
Lower Oil Prices Could Lift Qantas Shares And Other Airline Stocks
Oil prices have eased after recent war driven spikes, yet bond yields sit at multi decade highs and keep pressure on stock valuations. Fuel hungry transport and logistics groups sit right in the crosshairs of this mix of relief and stress, which can quickly reshape profit potential. This piece unwraps how that plays out for three specific stocks exposed to this news backdrop, and why their stories matter now.
The stocks covered next are just a sample of the opportunities that could feel any relief from cheaper fuel. The full screen pulled out 49 more transport and logistics businesses with equally compelling stories that are not included below. To identify and analyze those additional candidates with the strongest fit to this oil sensitive theme, head straight into the Energy-Intensive Transport & Logistics Benefiting from Lower Oil Prices screener.
Aegean Airlines (ATSE:AEGN)
Overview: Aegean Airlines is a Greece based carrier that provides passenger and cargo flights across domestic and international routes alongside related aviation services.
Operations: Aegean Airlines generates about €1.9b from high quality air transport, with roughly €405 million from Greece and €1.5b from international routes.
Market Cap: €1.0b
For an airline like Aegean Airlines, where jet fuel dominates the cost base, changes in oil prices can significantly affect the earnings picture.
"Aegean Airlines has experienced strong demand for travel, particularly during typically weak winter months, driven by increased visitation to Greece and improved domestic economic conditions, which could lead to higher revenue and more balanced seasonal performance."
Investors may want to consider how fuel driven margins could be affected if a major pressure on costs were to ease at scale.
That fuel swing risk is only one piece of the puzzle, and the full narrative for Aegean Airlines shows how Aegean Airlines could turn shifting demand into an accelerating story beyond seasonal travel.

Qantas Airways (ASX:QAN)
Overview: Qantas Airways runs domestic and international passenger and freight flights plus the Jetstar low cost arm and a large loyalty program. This makes it a fuel sensitive airline that can feel meaningful earnings relief when oil prices ease.
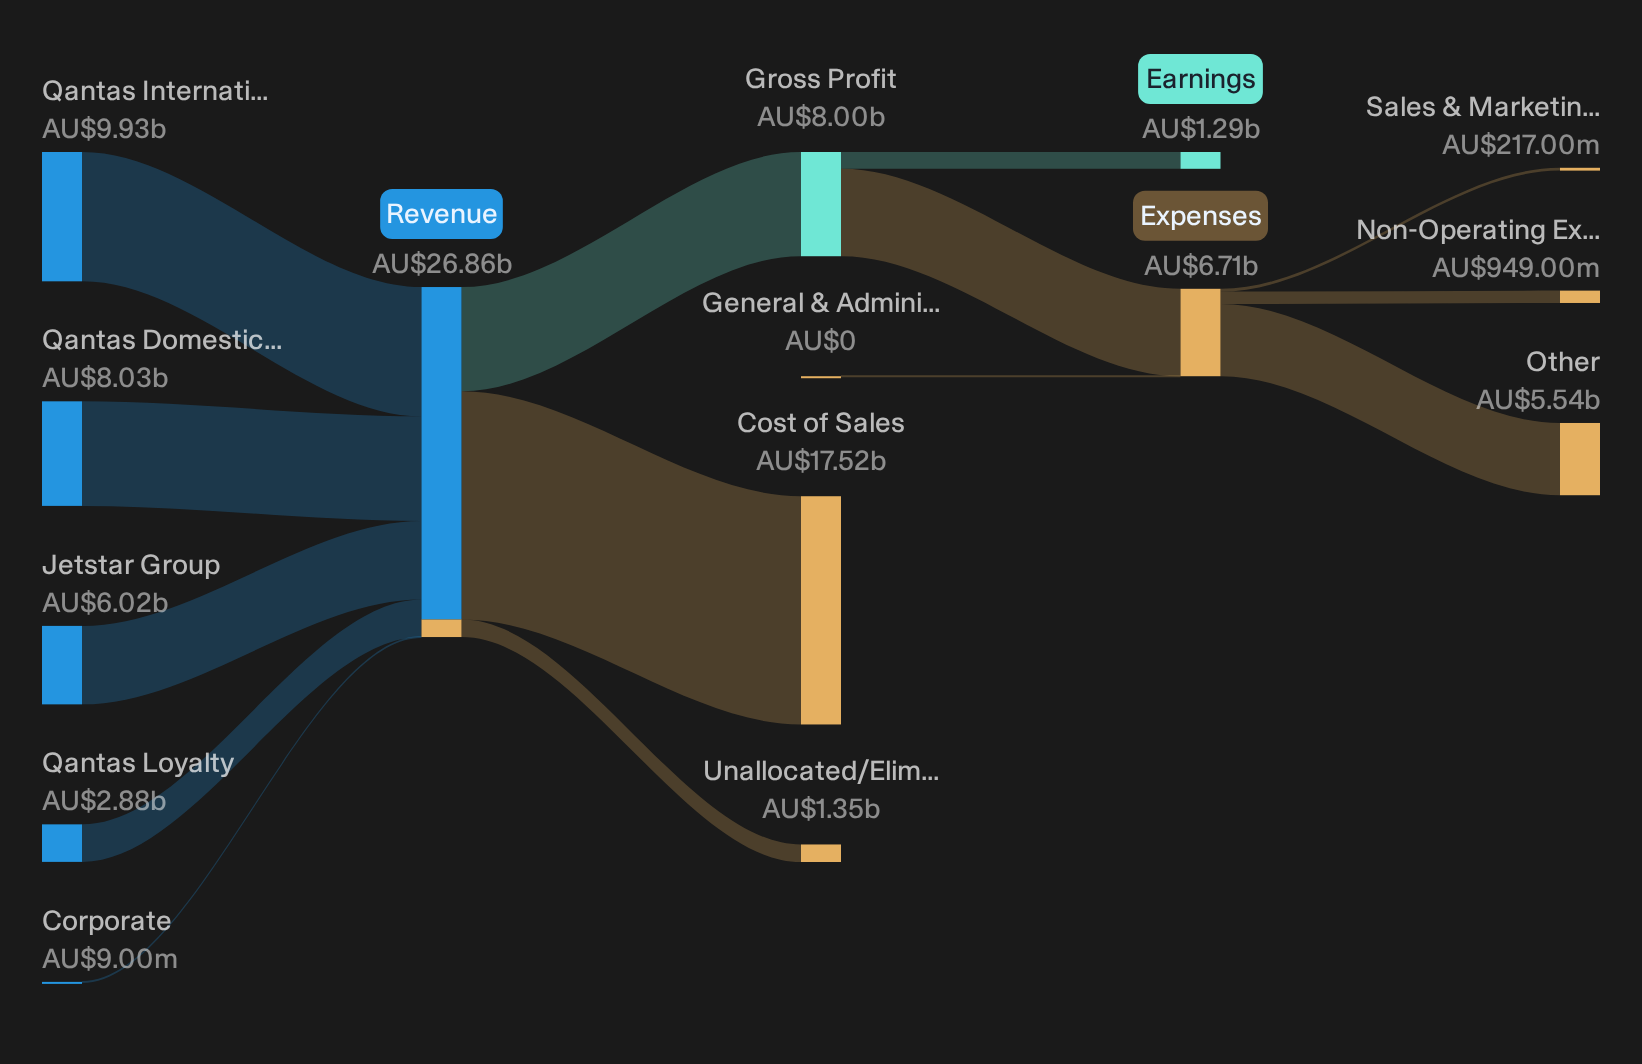
Operations: Qantas Airways generates about A$8.0b from Qantas Domestic, A$9.9b from Qantas International, A$6.0b from Jetstar and A$2.9b from Qantas Loyalty.
Market Cap: A$13.2b
Qantas Airways sits near the center of this lower oil theme because jet fuel costs and long haul flying magnify every move in crude prices.
"Fuel price fluctuations materially impacting margins"
The real story for Qantas now hinges on how one unseen pressure shapes the balance between robust demand and future margin headroom.
That margin headroom question is exactly what the full narrative for Qantas Airways unpacks, separating short term fuel relief from longer running drivers of Qantas Airways' earnings power.
Air New Zealand (NZSE:AIR)
Overview: Air New Zealand operates fuel intensive passenger and cargo flights across New Zealand and long haul routes spanning Asia, Europe and the Americas.
Operations: Air New Zealand generates about NZ$7.0b from transporting passengers and cargo, with NZ$4.1b from New Zealand and NZ$2.9b across overseas markets.
Market Cap: NZ$1.3b
Air New Zealand is a textbook example of the screener theme at work, where a fuel hungry network leaves profits tightly linked to jet fuel costs and broader economic conditions.
"Air New Zealand’s earnings are highly sensitive to fuel prices, operational reliability, and macroeconomic conditions, with near term performance potentially improving if jet fuel prices fall."
The real test now is how one quietly shifting cost line could reshape the room for margin recovery across this rebuilt fleet.
That margin room question is exactly what the full narrative for Air New Zealand tackles, highlighting where fuel swings, demand rebuilding and capacity decisions could be masking Air New Zealand’s next gear.

Seeking Fresh Alternatives Before They Fly
Markets move fast. Fresh breakout ideas, momentum shifts and quietly dropping valuations rarely stay under the radar for long. Scan these curated shortlists before the crowd arrives and act now.
- Spot potential cash generators early by scanning a curated 182 high quality undervalued stocks while valuations still reflect hesitation rather than full optimism.
- Track powerful income opportunities as yields and prices move by zeroing in on a hand picked 162 dividend fortresses before demand catches up.
- Ride the build out of next wave infrastructure by filtering a focused 40 power grid technology and infrastructure stocks while these stories are still forming.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com