
3 Fixed Income Stocks Investors May Revisit If Treasury Yields Stay Above 5%
When the 10-year Treasury yield pushes above 5% and the bedrock of “risk free” starts to feel less rock solid, the usual playbook for stocks gets scrambled. Bond-heavy asset managers and ETF sponsors sit right in that crossfire, which can create both pressure and fresh openings for patient investors. This article walks through three U.S.-listed fixed-income focused stocks that are directly exposed to this rate shock, and explains how each might be positioned.
The three stocks in this piece are a starting sample only, and the full screen surfaced 27 more U.S. and U.K.-listed fixed-income focused managers with equally compelling narratives that are not covered below. To go deeper, analyze, compare, and identify your own highest conviction ideas directly in the U.S.-Listed Fixed-Income Asset Managers and Bond ETF Sponsors screener.
St. James's Place (LSE:STJ)
St. James's Place gives this fixed-income focused screen a wealth-management angle, because it steers client portfolios across bonds and multi-asset funds while sitting right in the middle of the U.K. advice market.
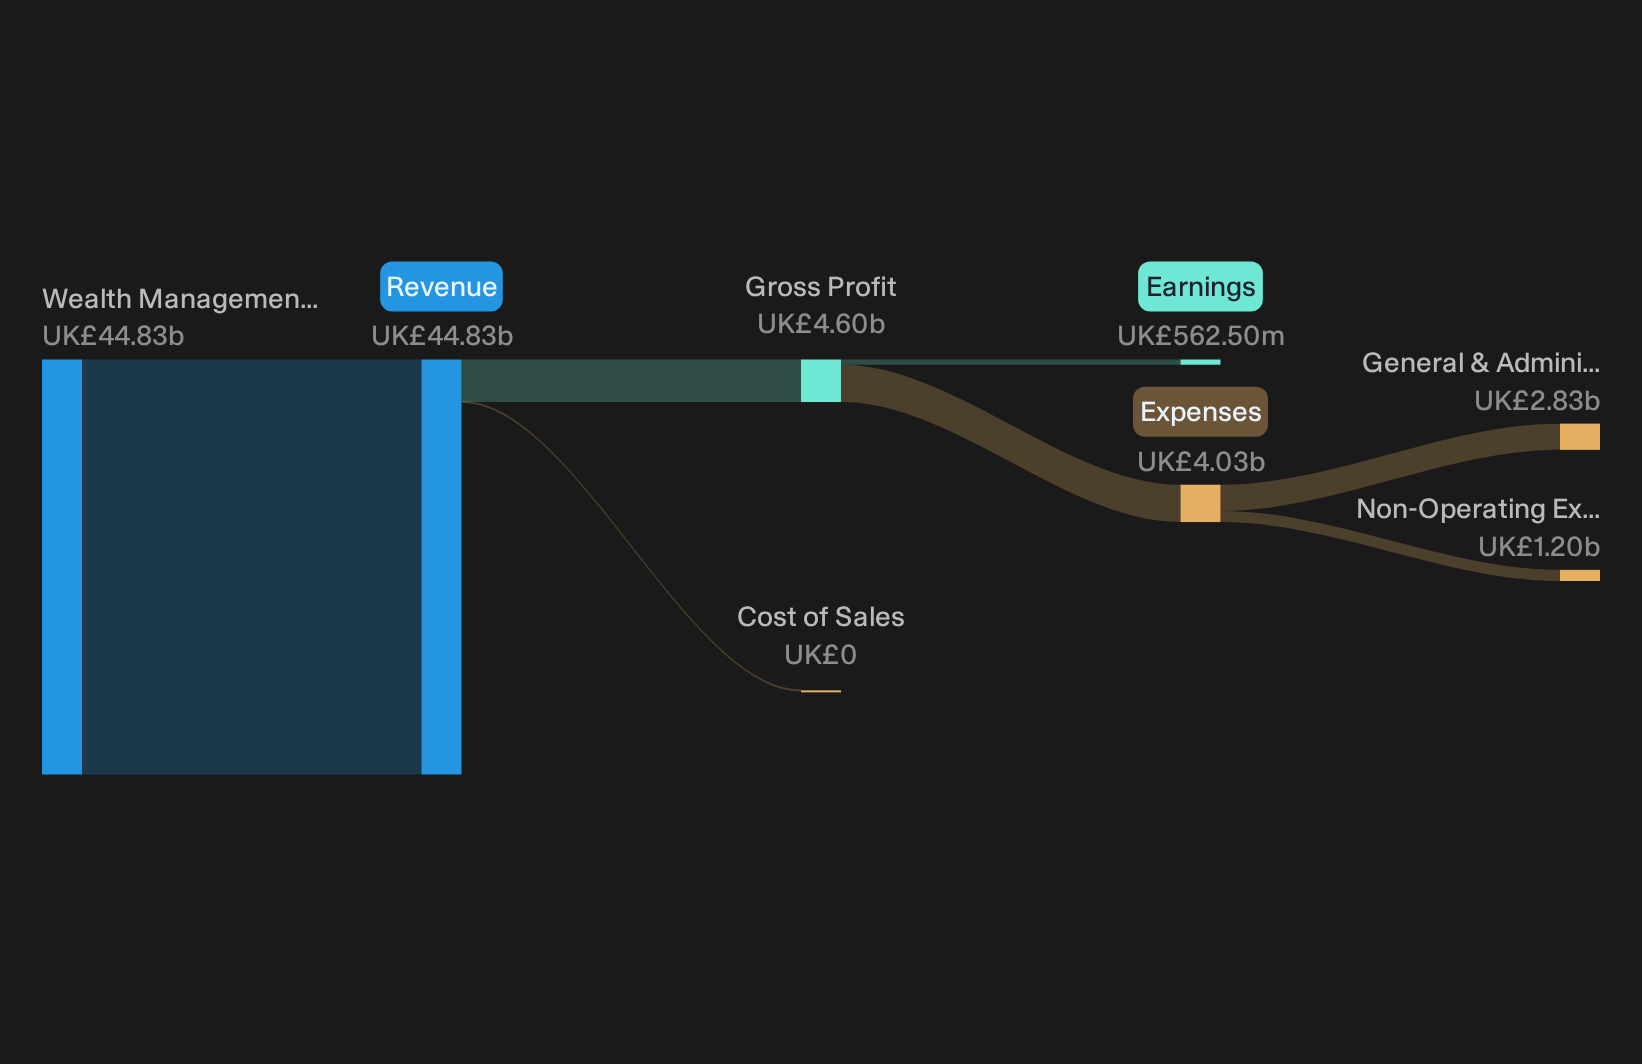
St. James's Place manages wealth for U.K. clients through equity, bond, and balanced funds, with its entire £44.8b wealth management business revenue generated in the United Kingdom and a market value of about £5.4b.
Expansion of digital platforms, automation, and hybrid advice models is improving adviser productivity and lowering administrative costs, which supports positive operational leverage and the company's ambition to double underlying cash results by 2030. This may ultimately drive net margin improvement.
What happens if one underappreciated pressure on its advice-led model shifts faster than expected just as fixed-income demand intensifies?
If that shift is what you are weighing, read the full narrative for St. James's Place to see how adviser economics, regulation, and client behavior could be quietly reshaping the opportunity.
Lazard (LAZ)
Lazard links into this fixed-income focused screen through its asset management arm, which runs bond and income strategies alongside its global advisory franchise. This gives investors a mix of fee streams that can respond differently when clients shift toward fixed-income products.
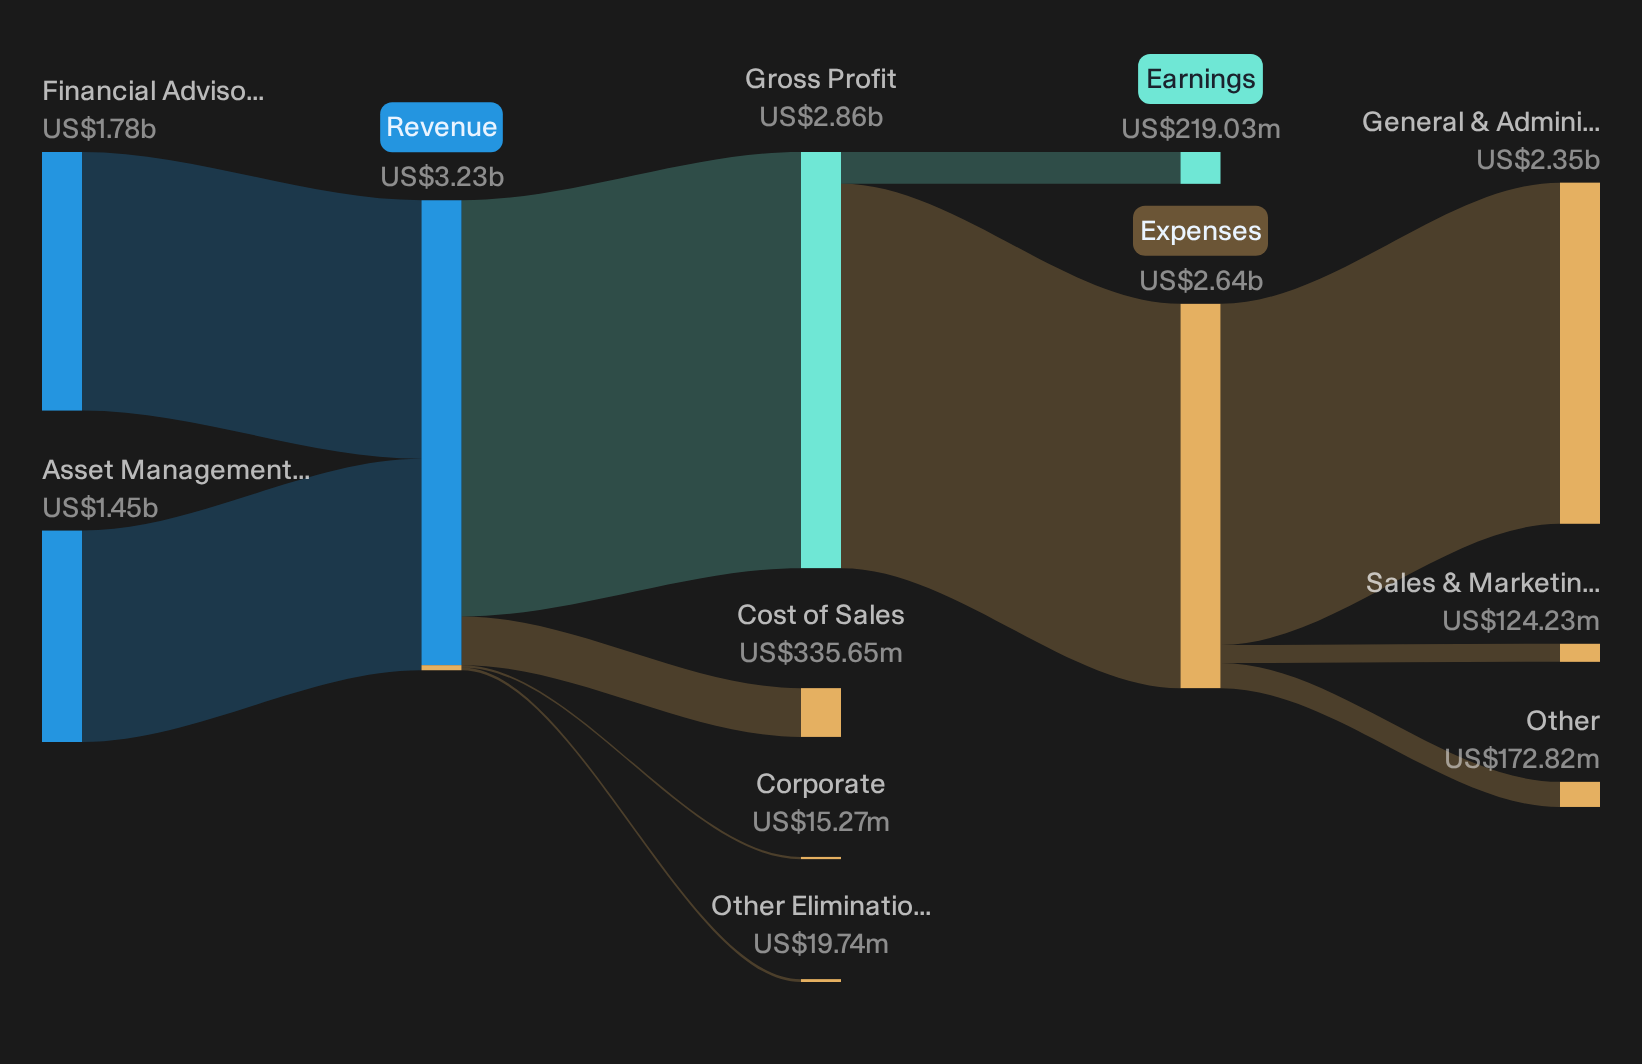
Lazard, Inc. is a global advisory and investment manager that pairs a large Financial Advisory unit, generating about US$1.8b, with an Asset Management arm producing roughly US$1.5b, plus a smaller corporate loss. The stock carries a market value near US$3.6b.
Lazard's expansion in the Middle East with a new Financial Advisory office in Abu Dhabi could strain resources and lead to higher operating costs without immediate revenue impact, potentially affecting net margins.
What really interests fixed-income focused investors is how one unresolved pressure on funding and payout commitments could tilt the balance between attractive yield and financial flexibility.
That funding puzzle is exactly what the full narrative for Lazard unpacks, showing how Lazard's capital commitments, payout promises, and advisory momentum could be quietly decoupling.
Liontrust Asset Management (LSE:LIO)
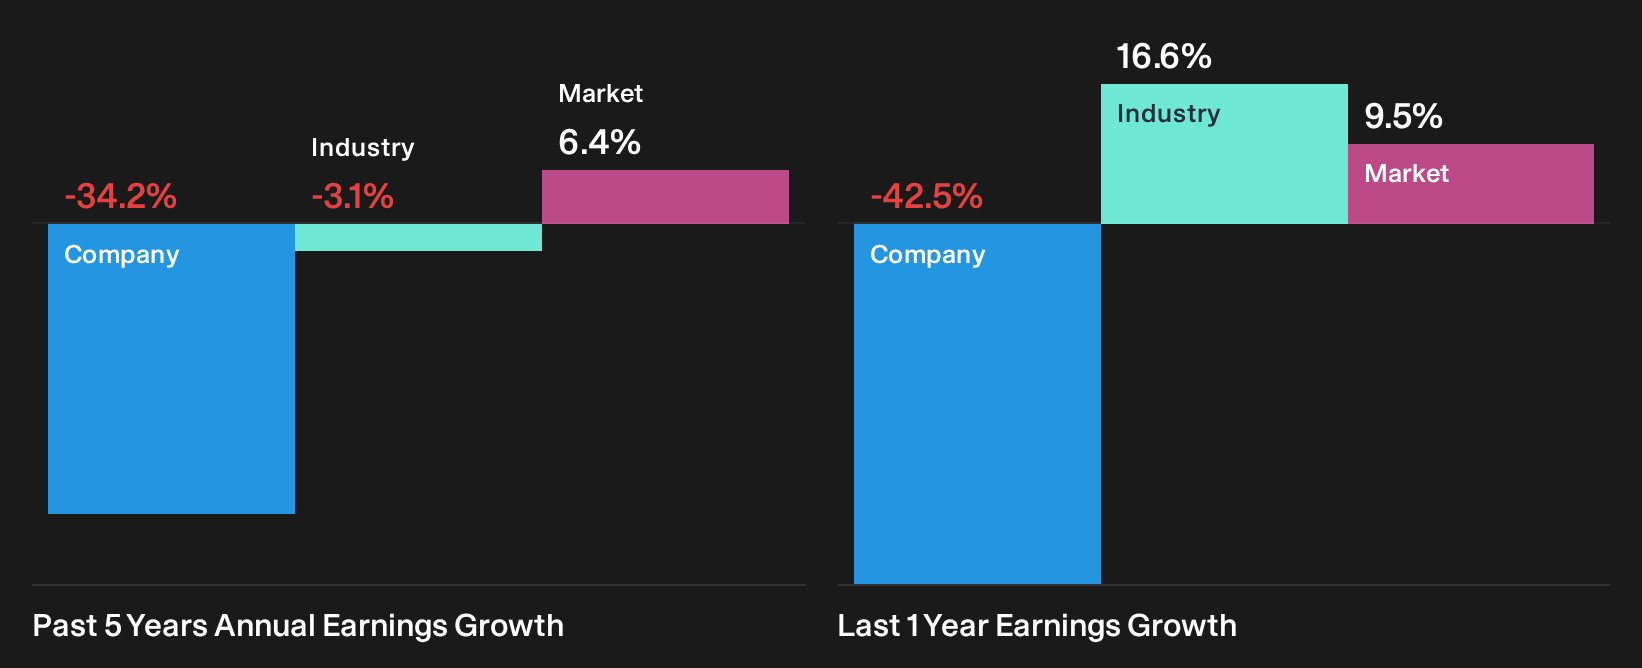
Liontrust Asset Management appears on this fixed-income focused screen as a U.K. asset manager running equity, bond, multi-asset, and managed funds. It generates £134 million from Investment Management and has a market value of about £159 million.
For investors scanning this fixed-income heavy shortlist, Liontrust Asset Management offers an active manager angle that could matter if clients shift towards bond funds and multi-asset solutions while still wanting stock pickers to run the money.
The accelerating structural shift toward low-cost passive investing and ETFs is likely to drive continued outflows from active managers, undermining Liontrust's core strategies and resulting in persistent pressure on assets under management and revenue growth.
What happens if one quiet shift in how investors pay for yield ends up forcing Liontrust to reset its whole profitability mix?
That reset is exactly what the full narrative for Liontrust Asset Management unpacks, revealing how fee pressure, product mix, and client flows could still accelerate the next chapter for Liontrust Asset Management.
Seeking Alternatives Before The Crowd
Fresh opportunities move fast. Some stocks are building quiet momentum while others are dropping off radars, and the best entry points rarely wait. Treat this as your early read, then consider your options promptly.
- Target resilient cash flows and lower volatility by scanning a curated list of solid balance sheet and fundamentals (10 results) before the crowd focuses on these sturdier businesses flying under the radar.
- Explore income-focused ideas by reviewing a hand-picked 1 dividend fortresses list while yields remain appealing and share prices have not fully reflected recent momentum.
- Position around the energy transition by concentrating on infrastructure builders through a selective 40 power grid technology and infrastructure stocks before attention broadens and pricing reflects shifting demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com