
HEICO (HEI) Could Be 22% Below Fair Value Following Q3 Earnings Beat
HEICO (HEI) just reported third quarter results that beat earnings expectations, with earnings per share up 32.5% year over year and sales, operating income, and net income all showing solid year over year gains.
Even with the earnings surprise, HEICO’s recent 30 day share price return is down 10.9%, and the 90 day share price return is also lower by 10.6%. However, the 3 year total shareholder return of 91.0% and 5 year total shareholder return of 128.9% highlight how strong the longer term compounding has been.
Compare HEICO’s post-earnings setup with a curated group of quality stocks on the move by scanning our 32 high quality undervalued stocks today.
HEICO just posted strong quarterly numbers, yet the share price has slipped over the past few months. Is most of the gain already in the rear view mirror, or does current valuation still leave meaningful upside on the table?
Most Popular Narrative: 21.7% Undervalued
Against HEICO’s last close at $308.53, the most followed narrative points to a fair value of $393.95, which implies meaningful upside if those long range assumptions play out as expected.
The worldwide trend of aging commercial and military aircraft fleets, combined with increasing pressure for cost-effective maintenance solutions, strongly favors HEICO's business model. As airlines and governments seek alternatives to expensive OEM parts, HEICO's FAA-approved PMA parts and repairs continue to gain market share and drive margin expansion, as reflected in rising operating and EBITA margins.
See why 26 investors see HEICO as 22% undervalued.
Result: Fair Value of $393.95 (UNDERVALUED)
Still, the HEICO narrative can break if competition from original equipment manufacturers squeezes aftermarket share, or if acquisition driven expansion starts to dilute profitability.
Find out about the key risks to this HEICO narrative.
Another View: What HEICO’s P/E Is Telling You
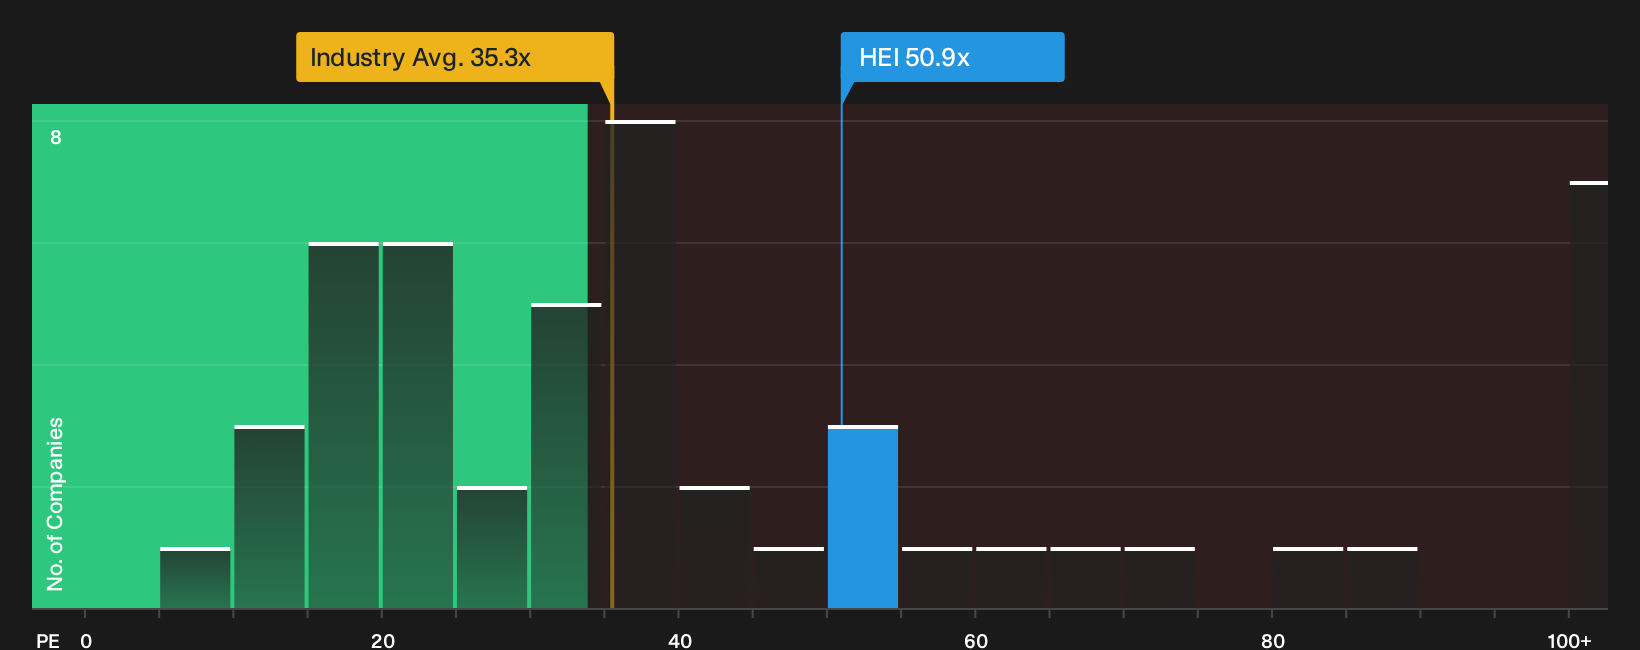
HEICO looks about 3.1% below the Simply Wall St fair value estimate, yet the current P/E of 50.9x tells a different story. That multiple is above the US Aerospace & Defense average of 35.3x and sits well ahead of the 27.9x fair ratio the market could move toward. For investors, that gap points to real valuation risk if sentiment cools faster than earnings grow.
To see how this high P/E stacks up against both peers and the fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages across HEICO’s valuation, sentiment, and recent price moves make this a stock you need to inspect on your own terms today. To see how the trade off between upside potential and downside risk stacks up in one place, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond HEICO?
If HEICO has your attention, do not stop here. Fresh opportunities keep moving, and the investors who act early usually see them first.
- Target stability first by scanning a 30 resilient stocks with low risk scores that aims to balance return potential with a focus on resilience.
- Hunt for quality at a discount through a 16 high quality undiscovered gems that highlights lesser known businesses with solid fundamentals.
- Prioritize financial strength by filtering for a list of solid balance sheet and fundamentals (24 results) that can help you avoid fragile companies before trouble shows up in the headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com