
Mexico Growth Outlook Might Change The Case For Investing In BBVA Stock
- Banco Bilbao Vizcaya Argentaria recently completed a €1.5b variable rate covered bond issuance maturing in 2031 and held a CEO presentation at Bank of America’s Financials Conference in London, outlining its business profile to investors.
- Management highlighted sustainable growth ambitions supported by profitability and loan demand in Mexico, while flagging Turkey as a near term earnings risk due to high inflation and interest rates.
- We will now look at how BBVA's investment narrative could be shaped by its confidence in Mexico as a long term growth engine.
Scan beyond Banco Bilbao Vizcaya Argentaria and compare its Mexico driven story with other banks and lenders that screen well on our list of solid balance sheet and fundamentals (202 results).
Banco Bilbao Vizcaya Argentaria Investment Narrative Recap
To hold Banco Bilbao Vizcaya Argentaria, you need to be comfortable with a simple equation. Mexico does the heavy lifting on growth and profitability, while Turkey injects volatility into group earnings. The CEO’s London comments keep that story intact. Loan demand and low leverage in Mexico remain the core upside driver, with digital and efficiency work supporting it.
On the risk side, the near term pressure point stays the same. High inflation and rates in Turkey keep earnings there under strain and reinforce existing concerns about emerging market exposure and currency swings. The recent updates do not radically change that short term risk balance.
The €1.5b covered bond issuance is the clearest operational move tied to this narrative. It extends wholesale funding out to 2031, uses a secured format, and carries a variable coupon that can adjust with future rate conditions. That matters for a bank focused on emerging markets where funding flexibility and cost control are critical.
For shareholders, this financing step feeds into the core catalysts. It supports BBVA’s ability to keep lending into Mexico’s low leverage banking system, maintain balance sheet strength, and continue its digital and ESG lending ambitions without relying only on short term markets. It does not remove Turkey risk, but it does give management more tools to manage that exposure.
Banco Bilbao Vizcaya Argentaria's analyst narrative points to forecast revenue of €48.1 billion and expected earnings of €12.3 billion by 2029, based on an assumed 12.1% yearly revenue growth rate. This implies earnings rising by about €1.6 billion from €10.7 billion today to the 2029 consensus figure.
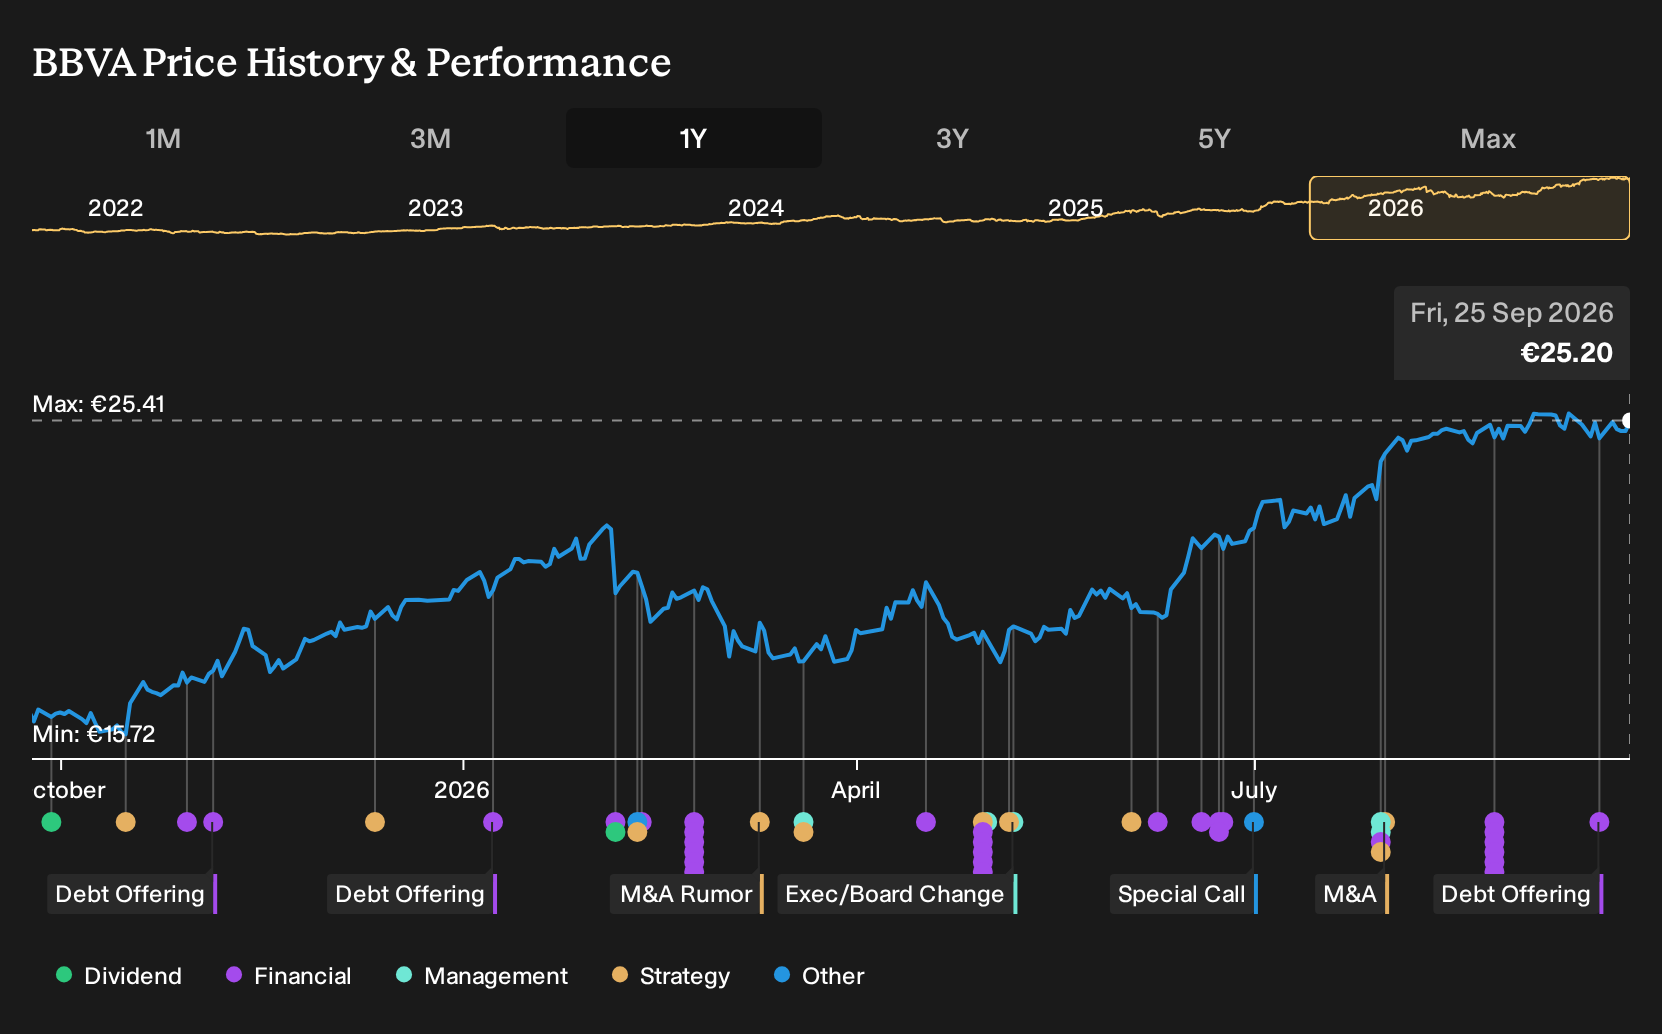
Explore how Banco Bilbao Vizcaya Argentaria's fair value points to a 9% potential downside from its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
One alternate storyline around Banco Bilbao Vizcaya Argentaria focuses on fintech pressure in Mexico rather than Turkey volatility. The most cautious analysts already expected revenue of about €45.1b and earnings of €11.2b by 2029 before this bond deal and CEO conference. That is well below consensus and shows how far opinions can differ. Use this new information as a prompt to compare those more pessimistic assumptions with your own view of BBVA’s Mexico opportunity.
Explore 3 other Banco Bilbao Vizcaya Argentaria fair value estimates, including one that suggests as much as 36% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Bilbao Vizcaya Argentaria research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Bilbao Vizcaya Argentaria. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Bilbao Vizcaya Argentaria's overall financial health at a glance.
Looking For More Ideas Beyond Banco Bilbao Vizcaya Argentaria?
If Banco Bilbao Vizcaya Argentaria has sharpened your thinking about risk, growth and balance sheet strength, you can use that momentum to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who care most about valuation support, review 182 high quality undervalued stocks that combine quality fundamentals with more modest pricing.
- If income is your priority, use 162 dividend fortresses to focus on companies offering higher yields while still aiming for resilience.
- For readers who want steadier profiles, filter for 227 resilient stocks with low risk scores that may offer a calmer ride through different market conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com