
BJ's Wholesale Club Holdings (BJ) Gets A Moody's Lift, Is It Still A Bargain?
Moody’s outlook change puts BJ's Wholesale Club Holdings in focus
Moody’s shift to a positive outlook on BJ's Wholesale Club Holdings (BJ) has turned attention to the retailer’s credit profile and what a potential investment grade path could mean for shareholders.
The outlook shift lands on a stock that has already been grinding higher, with a 90-day share price return of 5.54% and a last close of US$93.79. BJ's Wholesale Club Holdings has delivered a 31.41% total shareholder return over three years and 76.00% over five years, suggesting recent momentum is building on a much longer track record of shareholder gains rather than appearing in isolation from its broader performance story.
Capitalize on the credit upgrade theme by scanning hand-picked retailers and consumer stocks with resilient balance sheets through the 30 resilient stocks with low risk scores.After a steady climb, a positive Moody’s outlook and BJ’s Wholesale Club Holdings trading near US$93.79, the real fork in the road is simple: pay up now for perceived quality or wait for a better entry and risk missing it.
Most Popular Narrative: 13% Undervalued
On the numbers, the most followed narrative values BJ's Wholesale Club Holdings at $108.22 a share, which sits above the recent $93.79 close and frames Moody’s positive outlook alongside a slightly richer long term story according to LunaRodas.
The 2024 club class comping double digits, mentioned in Q2's prepared remarks, extends the delivery chain from what Q1 established. 22 of 23 clubs opened from 2022 to 2024 comping above the chain average. The new club engine is not a one-quarter story anymore. It is the most consistently delivered multi-quarter commitment in this transcript pair.
See why 1 investors see BJ's Wholesale Club Holdings as 13% undervalued.
Result: Fair Value of $108.22 (UNDERVALUED)
Still, the BJ's Wholesale Club Holdings story could be knocked off course if Texas club performance cools or if price investment compresses merchandise margins faster than funding offsets appear.
Find out about the key risks to this BJ's Wholesale Club Holdings narrative.
Another View on BJ's Wholesale Club valuation
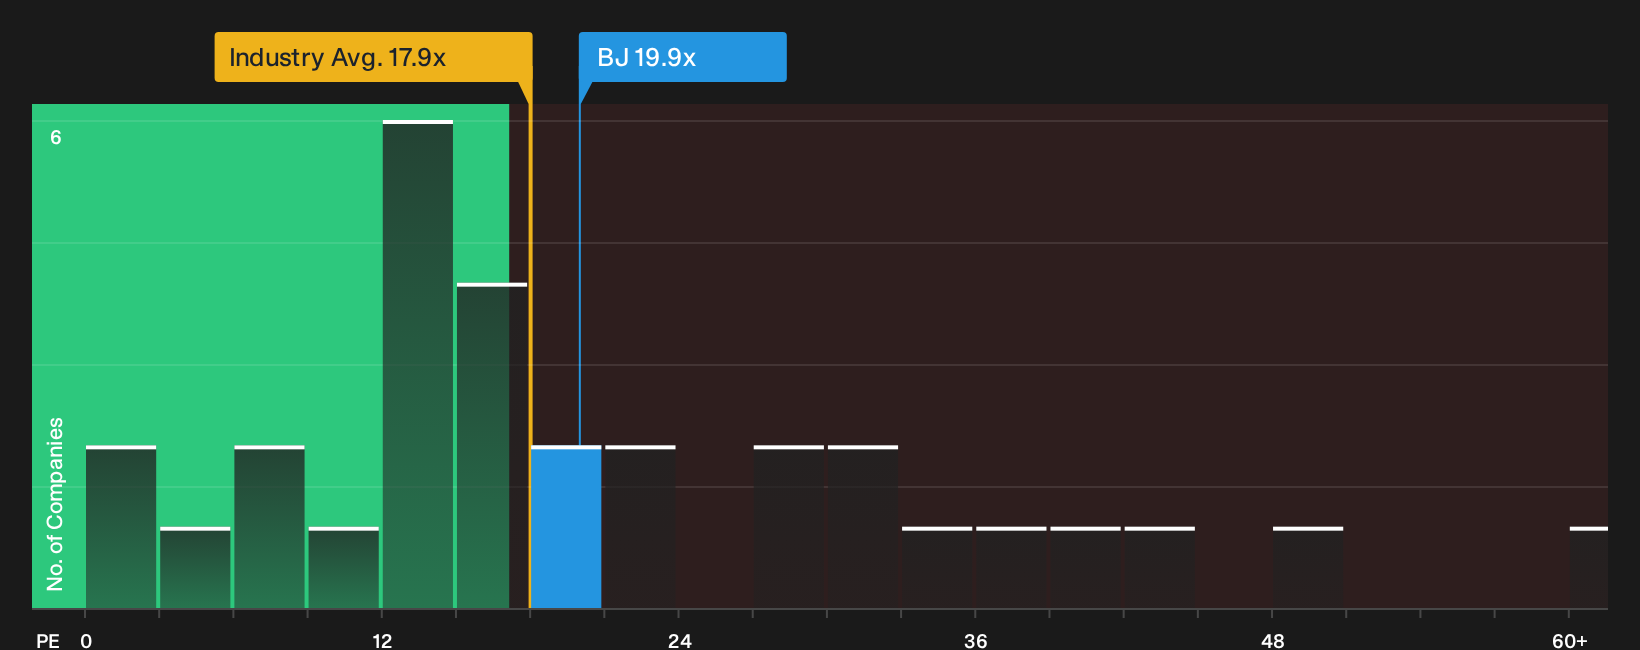
The user narrative pegs BJ's Wholesale Club fair value at $108.22, but the market is also signalling something else. At a P/E of 19.9x, the stock trades slightly above the US Consumer Retailing industry on 18x and just above peer companies on 19.8x, even though the fair ratio is 23.9x.
This gap suggests the share price already bakes in a quality premium while still leaving room for the P/E to drift toward that higher fair ratio. This can cut both ways for anyone concerned about overpaying or waiting too long, so it is worth considering how this aligns with your own margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether this mix of optimism and caution around BJ's Wholesale Club Holdings matches your own read on the situation? Take a close look at both sides of the argument and pressure test your thesis against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BJ's Wholesale Club Holdings?
If BJ's Wholesale Club Holdings has sharpened your thinking, do not stop here. Use the screener to compare it with other opportunities and pressure test your watchlist.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when conditions shift.
- Spot mispriced opportunities by reviewing a 32 high quality undervalued stocks that pairs strong fundamentals with valuations that may still leave room on the table.
- Strengthen your income stream by assessing a 8 dividend fortresses that focuses on higher yielding companies with potential staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com