
NVR (NVR), Is There More To This Housing Story?
Rising interest rates are squeezing home affordability and cooling buyer demand, putting pressure on homebuilders such as NVR (NVR) as investors reassess exposure to the sector and its interest rate sensitivity.
NVR’s recent moves in the market tell a mixed story. The share price has retreated over the year, with a year-to-date share price return of a 13.48% decline and a 1-year total shareholder return of a 21.60% decline, while the 5-year total shareholder return of 31.60% points to more constructive longer-term momentum that contrasts with the recent pullback as rising rates weigh on sentiment.
Spot 32 high quality undervalued stocks that, like NVR, combine disciplined capital allocation with resilient cash generation, even when higher mortgage rates are pressuring demand.The slide in NVR already reflects a lot of rate pain. The open question for investors now is whether current pricing still leaves meaningful upside, or if most of the easy valuation catch up has already played out.
Most Popular Narrative: 68% Overvalued
NVR last closed at $6,297.60, while the most followed narrative pegs fair value at $3,758 per share, so the story hinges on whether that gap reflects quality or exuberance.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model: NVR pays non-refundable deposits of ~10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land, NVR redeploys into share buybacks. The risk that peers absorb in housing downturns, NVR walks away from by forfeiting deposits.
See why 6 investors see NVR as 68% overvalued.
According to Esteban, the narrative argues that investors are paying a rich price for NVR’s asset-light approach and high reported returns, with the market price sitting far above the $3,758 fair value implied by a discount rate of 8.56% and more cautious revenue assumptions. The tension is clear. Simple Wall St’s own models currently see the shares trading 11.2% below an estimated intrinsic value based on future cash flows of $7,092.08. However, this narrative frames NVR as materially overpriced versus its long run fundamentals.
The fair value gap in Esteban’s work is driven less by a collapse scenario and more by discipline on entry price. Revenue growth in the narrative has already been revised down to a decline of 7.71%, and the fair value embeds that more muted outlook alongside a profit margin assumption of 12.49% and a future P/E of 13.57. In plain English, the thesis suggests the business model may be strong, but the share price leaves little room for disappointment if housing demand softens or if peers further copy NVR’s lot option strategy.
For readers weighing that stance against the current pullback, it helps to keep both sides of the ledger in view. Reported earnings have grown a modest 0.4% per year over the past 5 years, the latest year showed a 24.9% decline in profit, and net margins slipped from 14.2% to 11.9%. At the same time the company generated a high 33.7% return on equity, carries high quality earnings, and still screens as good value under some cash flow based approaches despite the recent share price performance.
Result: Fair Value of $3,758 (OVERVALUED)
Still, NVR’s story could crack if mortgage rates stay elevated for longer than buyers can tolerate or if rivals push lot optioning far enough to erode its edge.
Find out about the key risks to this NVR narrative.
Another View On NVR’s Valuation
There is a very different story if you zoom out to the SWS DCF model. On that measure NVR at $6,297.60 screens about 11.2% below an estimated future cash flow value of $7,092.08, which raises a simple question: Is the market overpaying on narrative, or underpricing the cash flows?
Look into how the SWS DCF model arrives at its fair value.
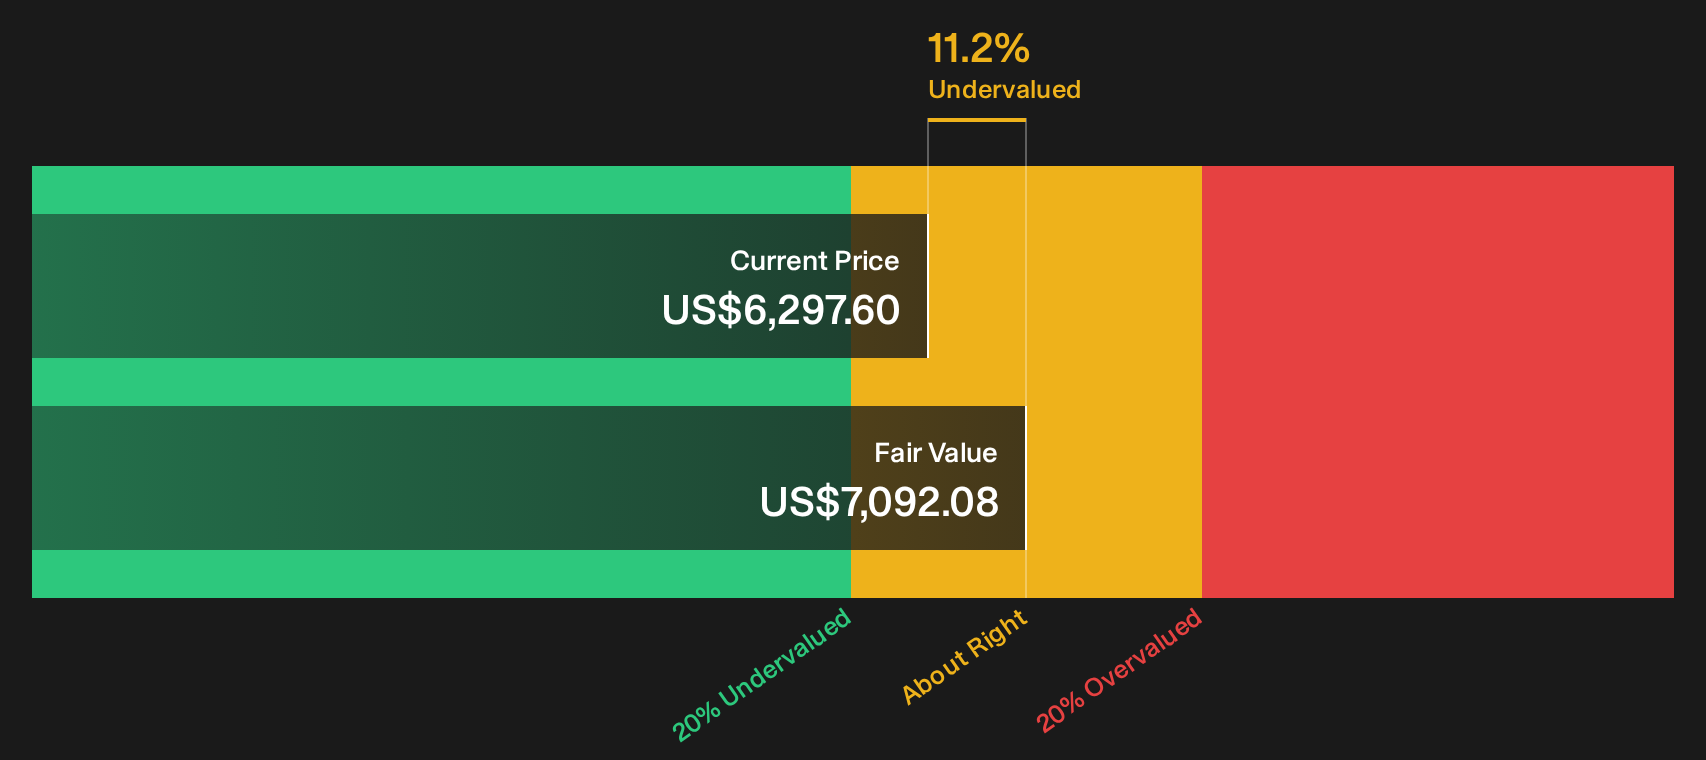
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on NVR is split, and the only view that really counts is yours. Move fast and weigh both sides by checking the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond NVR?
If NVR has you thinking about where to put fresh capital next, do not stop here. The best opportunities rarely sit in plain sight for long.
- Target resilient compounding potential by checking companies that score well on balance sheet strength using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by scanning the 16 high quality undiscovered gems before other investors start paying attention.
- Prioritise sleep-at-night portfolios by focusing on the 30 resilient stocks with low risk scores that keep financial risk metrics in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com