
Is Devin Rollout Altering The Investment Case For Cognizant Stock (CTSH)?
- Cognizant Technology Solutions and Cognition reported production use of Devin, an AI software engineer, at Odyssey Logistics, where Devin supported legacy conversion, cloud native rebuilds and testing for the OdysseyONE platform and contributed to an estimated 37% cost saving versus a conventional approach.
- The partners have moved beyond a single deployment into a broader suite of Devin based offerings for modernization, quality engineering and cyber defense. This suggests Cognizant is operationalizing AI assisted delivery at scale rather than treating it as a one off pilot.
- The focus now turns to what this wider Devin rollout could mean for Cognizant Technology Solutions' AI led investment narrative and cost model.
Compare Cognizant Technology Solutions' AI driven push with other potential breakouts by scanning our hand picked list of 37 profitable AI stocks that aren't just burning cash that are already turning AI into real earnings.
Cognizant Technology Solutions Investment Narrative Recap
Cognizant Technology Solutions appeals to investors who think AI assisted delivery can steadily reshape a large global IT services base rather than create a quick spike. The Devin rollout and Axis Bank contract both point to clients using automation to compress delivery cycles. The near term catalyst remains proof that this AI heavy delivery model can support stable revenue while keeping complex programs on track.
The biggest risk today is that discretionary tech budgets stay tight or move in house just as Cognizant leans into outcome based and fixed price deals. If AI projects stall or pricing compresses faster than productivity gains materialize, margin pressure could persist even with Project Leap and cost discipline.
The Devin production work with Odyssey Logistics looks most relevant because it directly tests Cognizant Technology Solutions' AI led cost model. Management has already trained more than 3,000 associates on Devin, and is now packaging that into modernization, quality engineering and cyber offerings, which relates directly to the core revenue and margin story.
For a shareholder, the catalyst is whether similar production wins across sectors build a repeatable book of AI heavy engagements. Execution risk remains significant. Clients could push for aggressive pricing on automation projects or pause AI work altogether if benefits remain patchy, which would blunt the payoff from Cognizant's training, tooling and capital deployment around AI.
Cognizant Technology Solutions' current analyst narrative points to revenue of US$24.9b and earnings of US$3.2b by 2029, built on forecast top line growth of 4.8% per year and an earnings step up of about US$1.0b from US$2.2b today.
Uncover why Cognizant Technology Solutions' fair value indicates a 12% potential upside to its current price, before other investors fully price in the AI thesis.
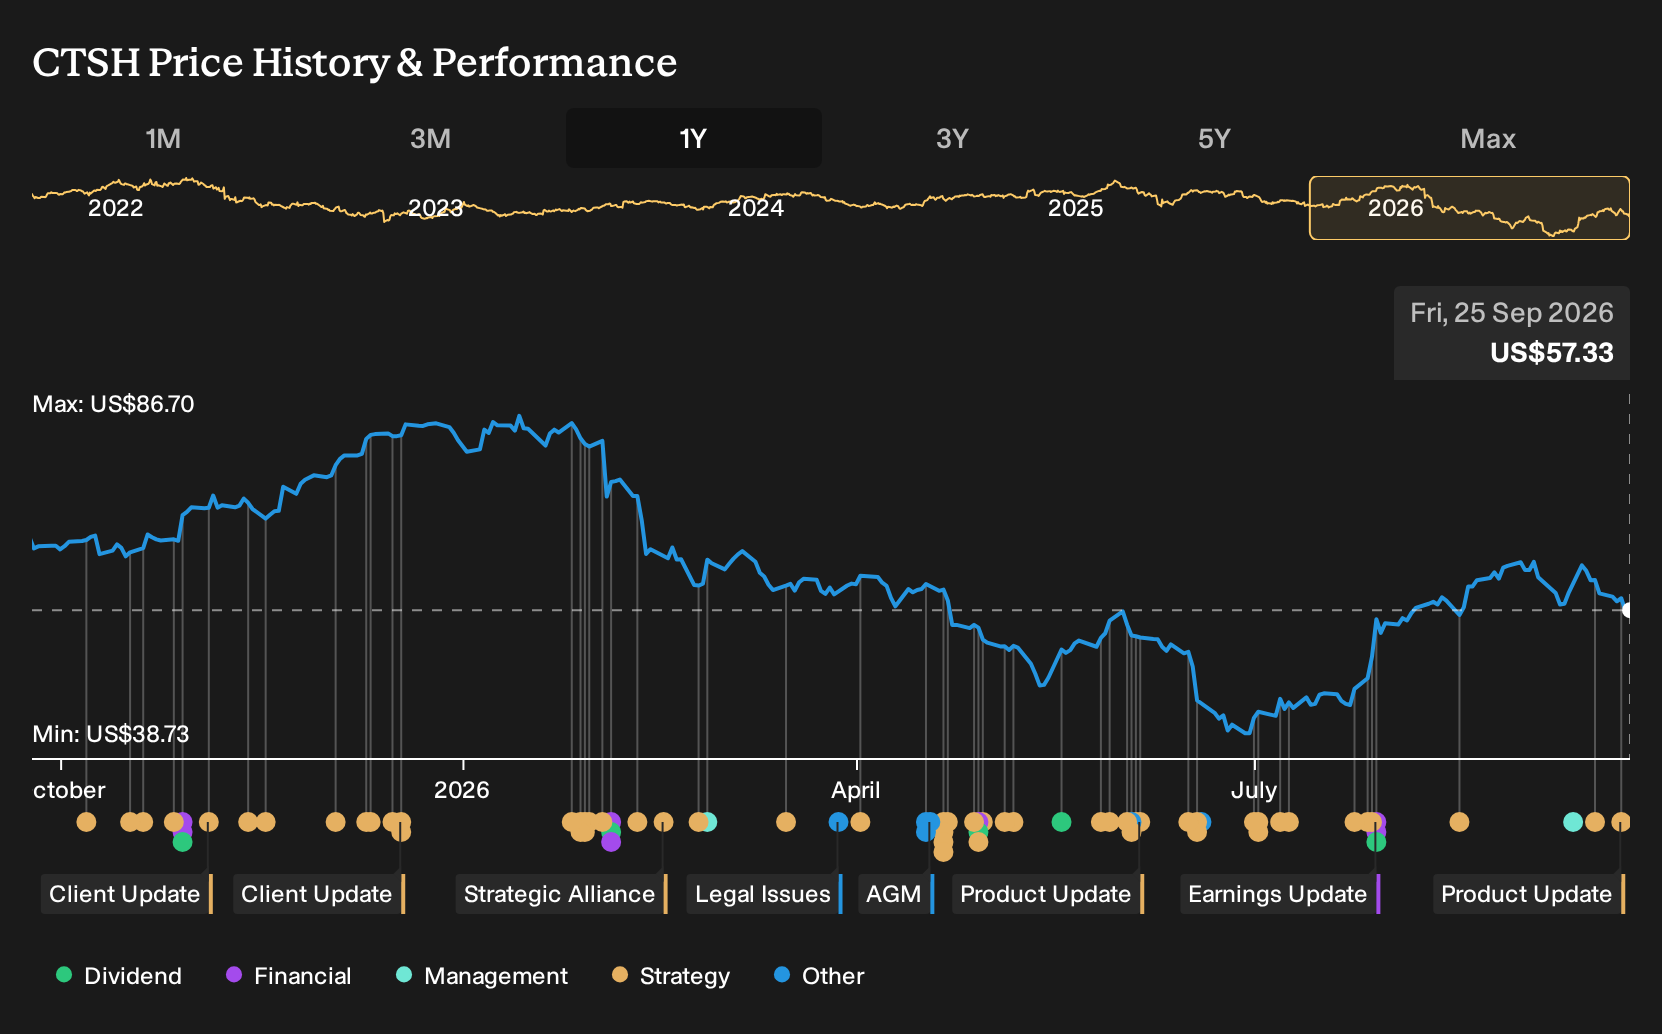
Exploring Other Perspectives
One alternate view says the real catalyst for Cognizant Technology Solutions is not cost savings but the extent to which AI builder projects can stretch revenue. The most optimistic analysts were already modeling about US$26.1b of revenue and US$3.9b of earnings by 2029. Those numbers did not factor in the Odyssey or Axis Bank updates, so you may want to reassess which scenario feels closer to your own expectations.
Explore 6 other Cognizant Technology Solutions fair value estimates, including one that suggests up to 94% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cognizant Technology Solutions research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cognizant Technology Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognizant Technology Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cognizant Technology Solutions?
If Cognizant Technology Solutions has sharpened your interest in AI led stories, broaden your watchlist by using the Simply Wall St Screener to spot other opportunities that match your risk profile, income needs and time horizon.
- If capital protection comes first for you, start with a set of 30 resilient stocks with low risk scores that score well on resilience and financial stability.
- For investors who care most about balance sheet strength and business quality, filter for companies in our list of solid balance sheet and fundamentals (24 results) and see which ones merit a deeper look.
- Those hunting for future candidates before they hit the spotlight can scan a curated pool of 16 high quality undiscovered gems with stronger fundamentals than their limited coverage implies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com