
3 British Founder Led Stocks With Up To 21% Earnings Growth
Global bond markets have been shaken by rising long term yields, which can punish companies that rely on cheap debt and short term thinking. Founder led British businesses often work differently. Leaders with meaningful skin in the game tend to think in decades, not quarters, and can be more disciplined about balance sheets. This article highlights three founder backed UK stocks from our screener that show how that mindset translates into listed companies.
The three founder led stocks below are just a starting sample from a much wider universe, with the full screen surfacing 60 more UK listed businesses where owners are still at the helm and the story is just as compelling. To identify the leaders that best fit your own playbook, head straight into the Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks is a founder led premium mixer specialist, with Tim Warrillow still running the business he built. This ties directly into this screener’s focus on long term owner operators shaping brand, pricing and expansion decisions for the long haul.
Fevertree Drinks develops and sells premium mixer drinks under the Fever Tree brand across the UK, US, Europe and other regions, and is currently valued at about £0.9b.
"The partnership with Molson Coors is intended to secure U.S. profit growth, but an overreliance on one strategic partner may expose Fevertree to unfavorable contract renegotiations, possible margin dilution if guaranteed royalties fail to match rising costs, and slower-than-expected U.S. market penetration, all of which could weigh on future profits."
The impact of any single assumption about future pricing power will matter a lot for how this founder story plays out.
That pricing power debate sits at the center of the full narrative for Fevertree Drinks, where the focus shifts to how brand strength and capital discipline could keep earnings momentum accelerating beyond one partnership wrinkle.

Computacenter (LSE:CCC)
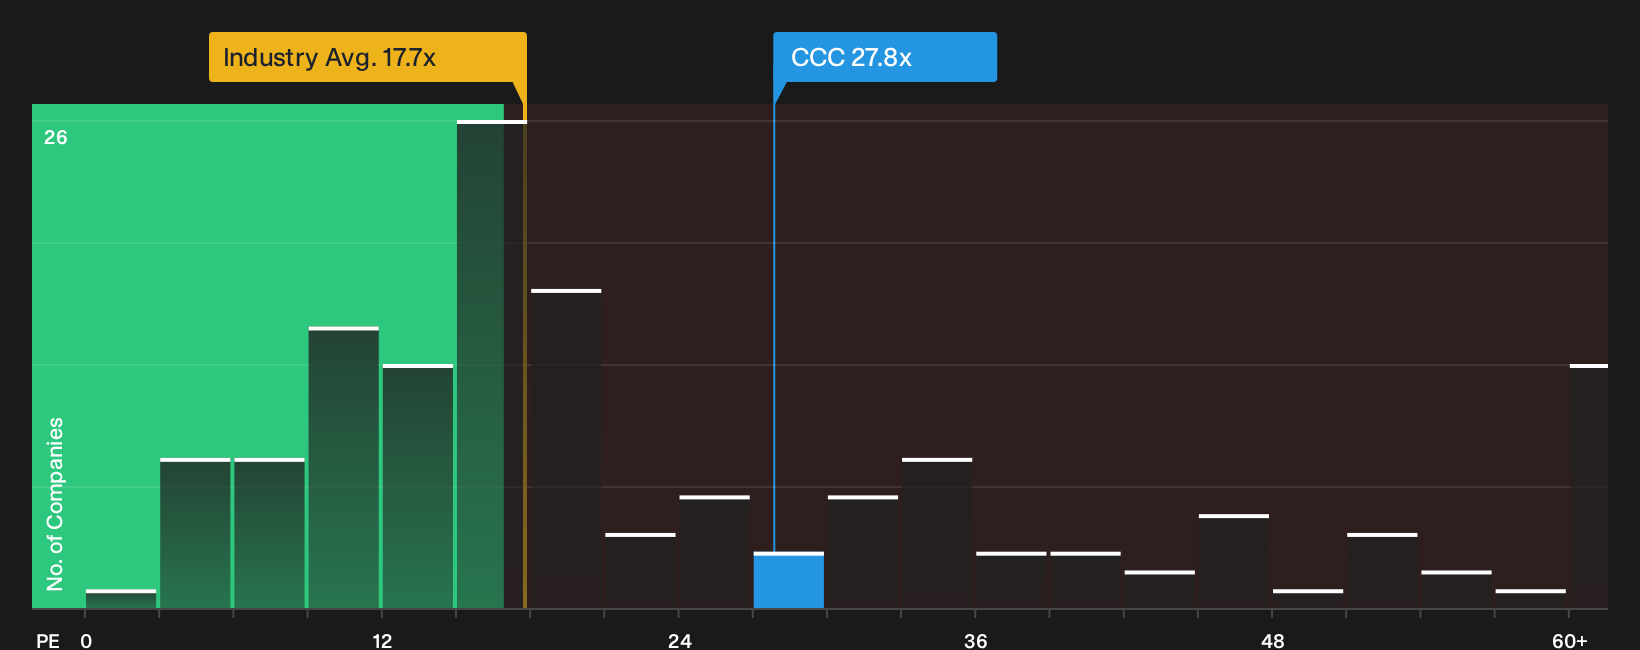
Computacenter is a founder influenced IT services group, where founder Philip Hulme still holds a large stake and serves on the board, aligning leadership with long term performance. The business generates about £12.1b from computer services and is valued at roughly £5.7b.
Earnings growth running ahead of the wider IT sector, a P/E of 27.8x below peer averages, and a high 21.1% ROE all point to a founder aligned operator turning long-term outsourcing contracts into meaningful shareholder value, depending on how one unseen pressure on its tight 1.7% net margin plays out.
That razor thin margin is the hinge. See how long term contracts, a P/E of 27.8x, and a 21.1% ROE connect inside the analysis report for Computacenter
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an asset manager that channels capital into infrastructure and founder-led private equity and venture-backed businesses, with about £114.8 million of revenue from real assets and £50.1 million from private equity, and a market value near £476 million.
Foresight Group plays to the Founder-Led Companies theme from a different angle, using its private equity and venture funds to back founders directly while investors gain exposure through the listed manager.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is expected to support compounding EPS growth and may result in higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and the return of capital accelerates."
The real test will come if one key pressure point on how Foresight Group converts fee income into consistent margins shifts against these assumptions.
If that pressure point proves less fragile than it looks, the full narrative for Foresight Group Holdings explains how Foresight Group Holdings could turn fee resilience into accelerating, cash backed returns.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly while attention is elsewhere. Some ideas begin to show breakout momentum before headlines catch up. Scan these under the radar sets now and consider them before they become widely followed.
- Explore potential income resilience by checking out 1 dividend fortresses that may help keep cash flows steady while much of the market focuses on lower yields.
- Identify under-followed growth stories early by scanning the 5 high quality undiscovered gems that are relatively quiet for now but may gain attention as awareness increases.
- Monitor infrastructure themes in motion through the 87 AI infrastructure stocks before broader capital flows concentrate in a smaller group of companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com