
Is Cullen/Frost Bankers (CFR) A Bargain As Dividend Focus And 2026 Guidance Lift Interest?
Fresh commentary around Cullen/Frost Bankers (CFR) is centering on its dividend profile and management’s 2026 guidance, which together are shaping how investors weigh the bank’s Texas growth and capital return plans.
Cullen/Frost Bankers’ share price has pulled back over the past month, with a 30 day share price return of 3.58% and a softer 7 day move. Yet the year to date share price return of 22.82% and 1 year total shareholder return of 25.74% show momentum that longer term holders will recognize from the 3 year total shareholder return of 89.52% and 5 year total shareholder return of 49.45%. This frames the latest dividend commentary and 2026 guidance as part of an ongoing recalibration of growth expectations and perceived risk.
Spot other banks trying to balance dividend appeal with growth guidance by scanning the hand picked 8 dividend fortresses that share Cullen/Frost Bankers' focus on income and capital return.Cullen/Frost Bankers looks like a solid Texas banking franchise with clear income appeal after the recent run. The next step is simple: Are you paying a fair price for that strength today?
Most Popular Narrative: 10% Undervalued
Against Cullen/Frost Bankers’ last close of $157.42, the most followed valuation narrative anchors fair value at $174.86, which implies a material gap that hinges on how credibly management can hit its 2026 growth and efficiency targets.
Management’s guidance for 2026, including higher ranges for full year average loan growth of 7% to 8%, net interest income growth of 4.75% to 5.25% and noninterest income growth of 7.5% to 8.5%, along with lower expected expense growth, points to operating leverage that could support future margins and earnings if delivered.
See why 4 investors see Cullen/Frost Bankers as 10% undervalued.
Result: Fair Value of $174.86 (UNDERVALUED)
Still, the Cullen/Frost Bankers story can shift quickly if Texas credit pockets in real estate or energy worsen, or if branch heavy expansion keeps expenses stubbornly high.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another View: Cullen/Frost Bankers On Earnings Multiples
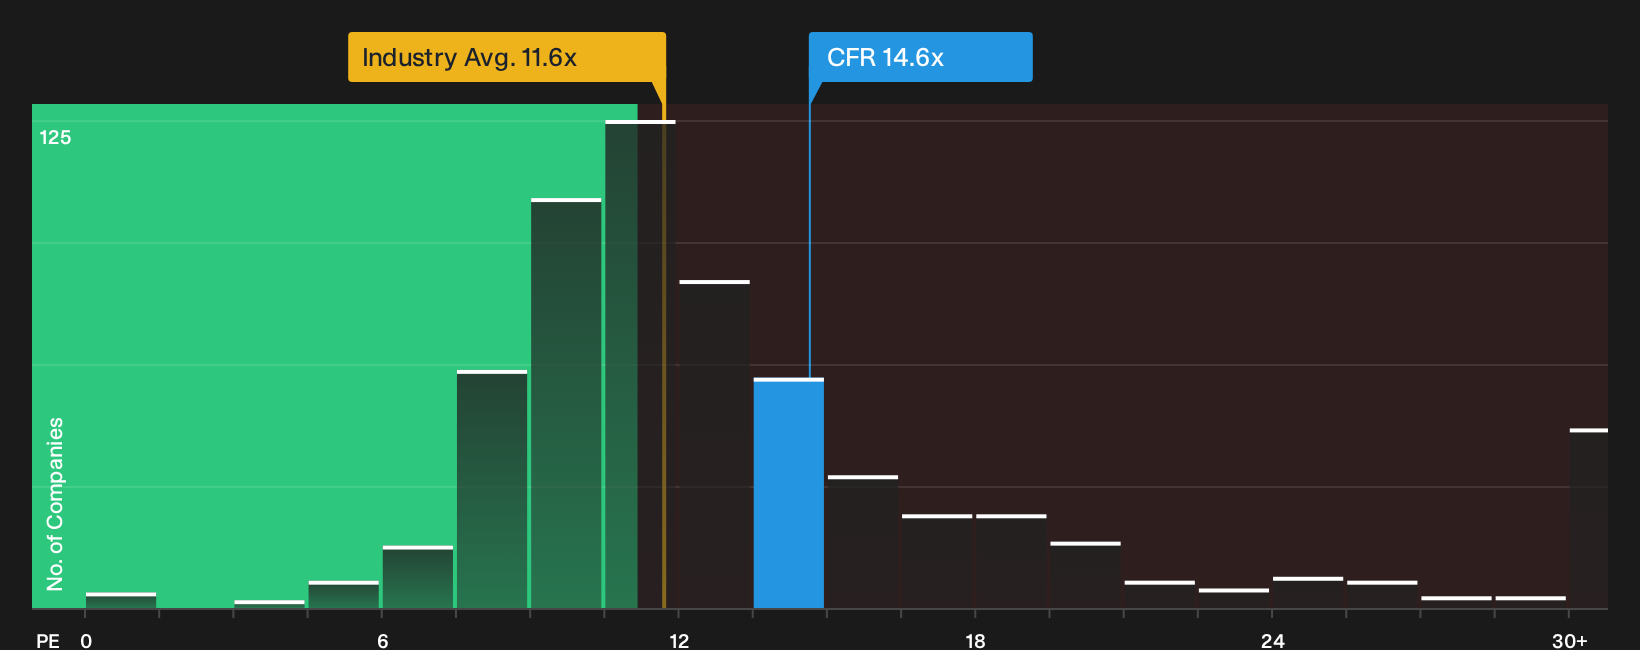
The cash flow work suggests Cullen/Frost Bankers is attractive, yet the earnings multiple presents a more challenging picture. The shares trade on a P/E of 14.6x, compared with a fair ratio of 11.9x, the US Banks group at 11.6x, and peers at 10.3x. That richer valuation raises a straightforward question: Is the DCF upside enough to compensate for paying above sector and peer levels today?
To see how the current pricing compares with the earnings profile, and what that higher P/E might imply for potential returns, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Cullen/Frost Bankers is mixed. Treat this as a prompt to move quickly, review the underlying numbers, and decide where you stand. To see what optimistic investors are focusing on, take a closer look at the 3 key rewards.
Looking for more Cullen/Frost Bankers style ideas?
If Cullen/Frost Bankers has sharpened your focus, do not stop here. Use fresh data driven shortlists to spot what others might overlook tomorrow.
- Target stability first by checking companies that pair healthy cash flows with resilient finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for value by reviewing the 32 high quality undervalued stocks that blend quality fundamentals with attractive pricing before attention catches up.
- Get ahead of the crowd by scanning the 16 high quality undiscovered gems that strong fundamentals already support even if wider recognition has not arrived yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com