
Magnolia Oil & Gas (MGY) Following Its Shelf Filing And Oil Volatility Looks Undervalued But Riskier
Magnolia Oil & Gas stock moves after large shelf registration filing
Magnolia Oil & Gas (MGY) has put a fresh financing option on the table, filing a shelf registration for up to US$889.4m of Class A shares totaling 32,203,000 securities.
Recent trading reflects that backdrop. Magnolia Oil & Gas has seen its share price fall 2.6% over the past day and 8.8% over the past month, while its 1-year total shareholder return is slightly negative even though the 5-year total shareholder return sits in positive territory. This suggests longer term holders have fared better than recent buyers as energy volatility and the new shelf registration reshape expectations around both growth potential and risk.
Compare Magnolia Oil & Gas with other energy producers facing similar volatility by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that may better balance commodity sensitivity with financial resilience.
Given Magnolia Oil & Gas now faces both a fresh equity overhang and fully unhedged commodity swings, does the recent pullback still leave enough upside to justify the added risk, or has the balance shifted?
Most Popular Narrative: 26% Undervalued
On the most followed narrative, Magnolia Oil & Gas screens as undervalued, with a fair value of $32.65 against a last close of $24.11. In that framework, the shelf registration sits against a backdrop of a stock already trading at a discount.
Ongoing bolt-on acquisitions and successful appraisal programs are expanding Magnolia's core Giddings acreage at low cost, increasing the duration and scale of its high-return inventory. This supports longer-term production growth, more robust free cash flows, and ultimately higher revenue visibility.
See why 10 investors see Magnolia Oil & Gas as 26% undervalued.
Result: Fair Value of $32.65 (UNDERVALUED)
Still, the bullish Magnolia Oil & Gas narrative relies heavily on continued bolt-on deals and an unhedged commodity profile that could quickly work against shareholders.
Find out about the key risks to this Magnolia Oil & Gas narrative.
Another View: Magnolia Oil & Gas Through The P/E Lens
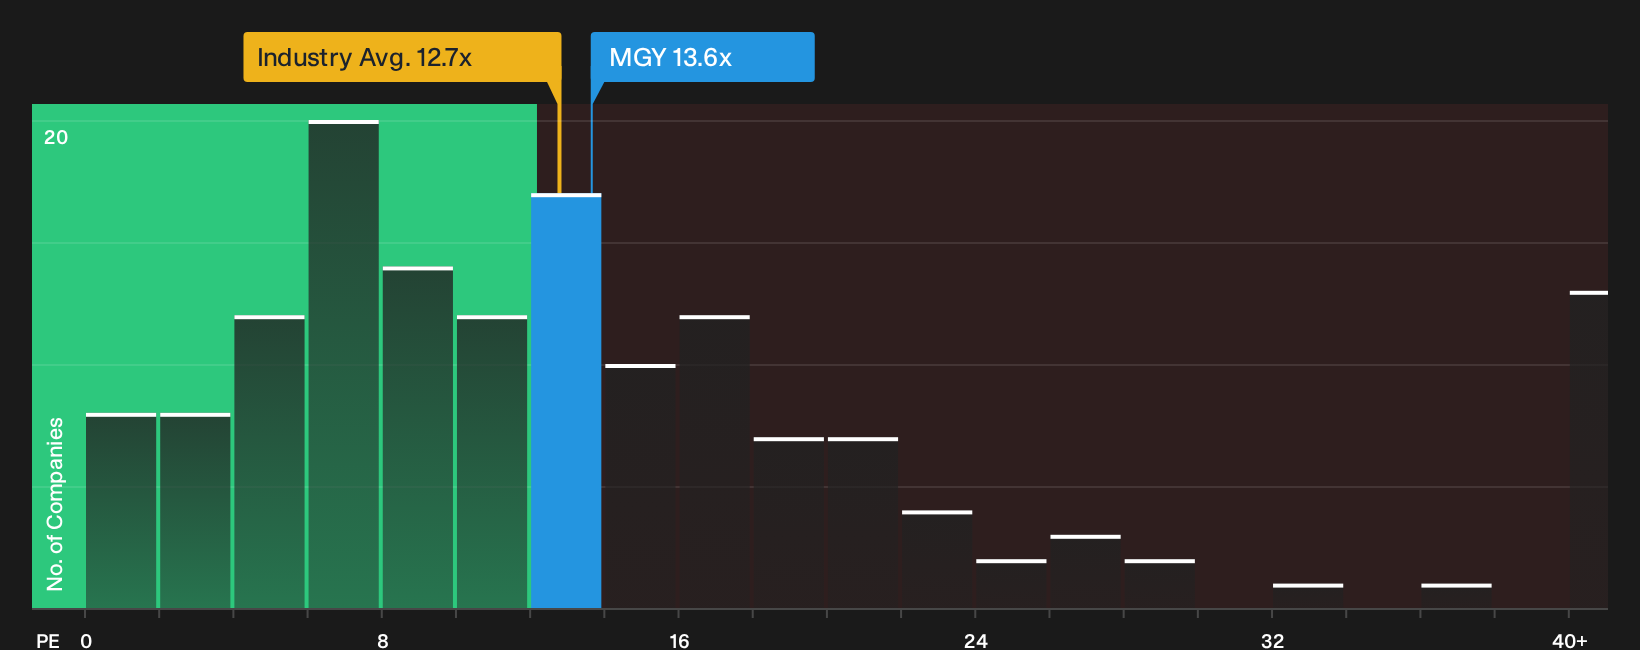
Magnolia Oil & Gas may screen as undervalued on fair value models, yet its P/E of 13.6x runs above both the US Oil and Gas group at 12.8x and a 10.5x peer average, while sitting below a 19.4x fair ratio that the market could move toward. Is this a valuation cushion or a signal that earnings expectations already carry extra risk?
For a closer look at how this earnings multiple stacks up in practice, including where the fair ratio leaves room for upside or disappointment, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Magnolia Oil & Gas so far. If you want to move quickly and form your own take based on the same numbers, start with 3 key rewards and 1 important warning sign.
Looking for more Magnolia Oil & Gas sized investment ideas?
You do not need to stop at Magnolia Oil & Gas. Use the same tools professionals rely on to quickly surface focused opportunities that match your approach.
- Target potential upside by scanning a curated pool of stocks that currently screen as attractively priced using the 32 high quality undervalued stocks.
- Stabilize your portfolio by focusing on resilient businesses that carry stronger finances through the 30 resilient stocks with low risk scores.
- Spot lesser known opportunities early by browsing the 16 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com