
Yangzijiang Shipbuilding (Holdings) (SGX:BS6) On Its Seaspan Tie Up And Valuation
Yangzijiang Shipbuilding (Holdings) (SGX:BS6) is back in focus after its closer tie up with Seaspan through the Poseidon and Seaspan acquisition, which gives the shipbuilder direct access to long term vessel demand pipelines.
Recent price action has been strong, with Yangzijiang Shipbuilding (Holdings) trading at SGD5.19 after a 30 day share price return of 7.23% and a 90 day move of 48.29%. The 1 year total shareholder return of 65.91% and roughly 7x 5 year total shareholder return indicate that momentum has been building over multiple timeframes.
Scan for other shipbuilders and capital goods stocks that show similar contract pipelines and price strength by checking the curated 620 high quality undiscovered gems alongside Yangzijiang Shipbuilding (Holdings).
After such a sharp move and a closer link to Seaspan’s order pipeline, the key issue for Yangzijiang Shipbuilding (Holdings) now is simple. Does the current price still offer an attractive risk reward, once the valuation is unpacked?
Most Popular Narrative: 4.9% Undervalued
On kapirey’s narrative, Yangzijiang Shipbuilding (Holdings) screens as slightly undervalued, with a fair value of SGD5.46 against the latest SGD5.19 close. That framing leans heavily on contracted work, green-vessel exposure, and the shift into a broader maritime ecosystem.
The original thesis centred on Yangzijiang as a high-quality industrial compounder benefiting from a structural shipbuilding upcycle, clean-energy vessel demand, and disciplined capital allocation. That thesis remains largely valid. However, a landmark strategic acquisition in March 2026 materially changes the company's risk profile and long-term positioning, and requires an updated framework.
See why 14 investors see Yangzijiang Shipbuilding (Holdings) as 5% undervalued.
Result: Fair Value of SGD5.46 (UNDERVALUED)
Still, the Yangzijiang Shipbuilding (Holdings) narrative could be knocked off course if shipbuilding demand weakens sharply or the Poseidon stake underperforms expectations.
Find out about the key risks to this Yangzijiang Shipbuilding (Holdings) narrative.
Another View On Yangzijiang Shipbuilding’s Value
kapirey’s fair value of SGD5.46 paints Yangzijiang Shipbuilding (Holdings) as slightly undervalued. Our DCF model points the other way, with an estimated future cash flow value of SGD4.93 against the SGD5.19 share price, which implies the stock screens as expensive on this framework. Which lens do you trust more when the signals conflict?
For investors who want to unpack the moving parts behind that cash flow estimate, it can help to see each assumption laid out step by step, then decide whether those inputs feel conservative or generous for Yangzijiang Shipbuilding (Holdings). Look into how the SWS DCF model arrives at its fair value.
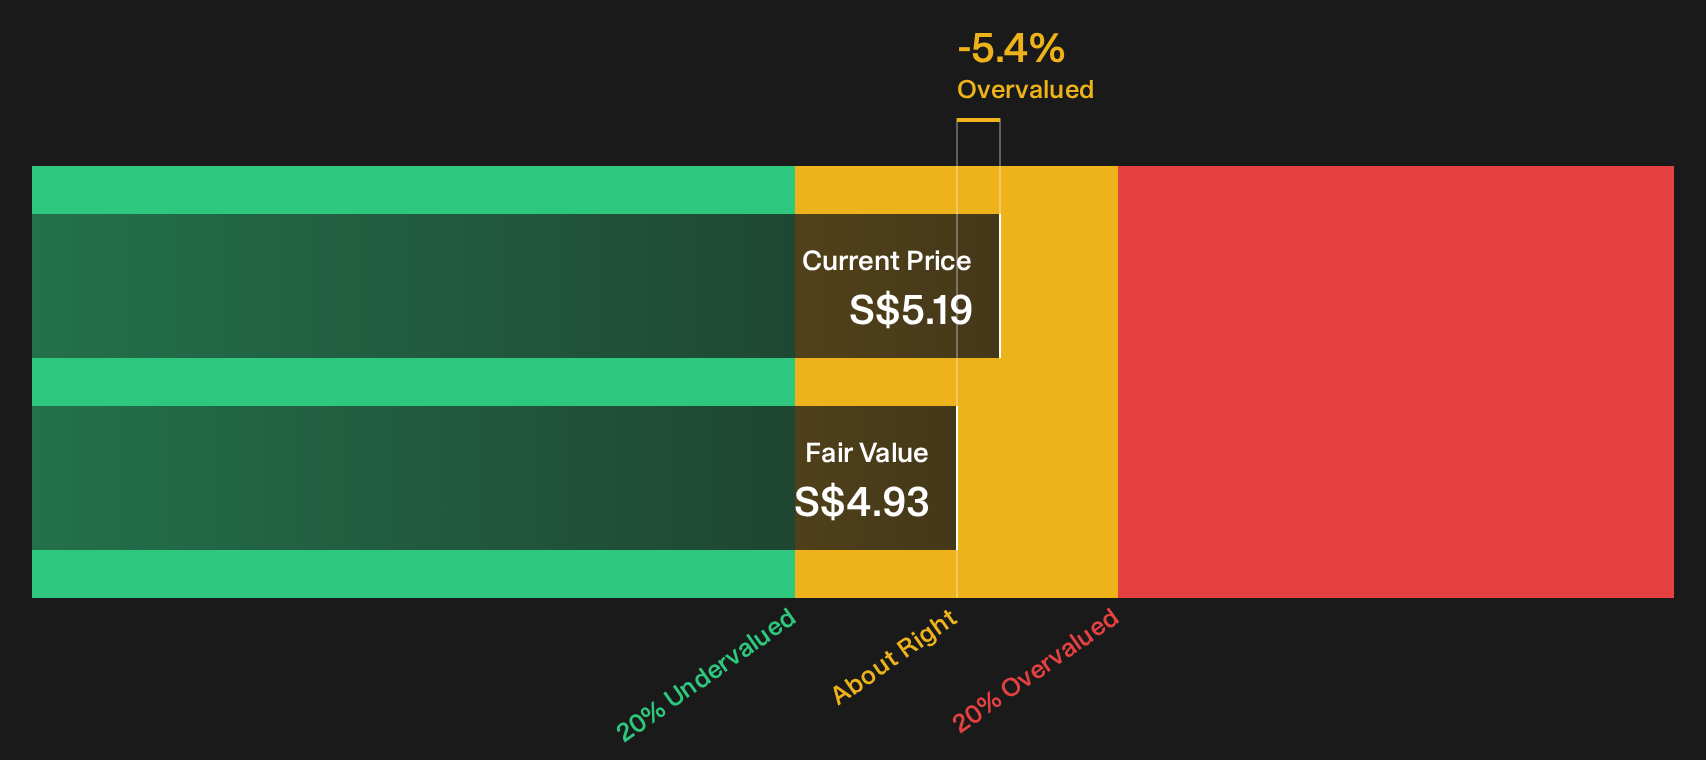
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yangzijiang Shipbuilding (Holdings) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split in views on Yangzijiang Shipbuilding (Holdings) has you on the fence, move quickly and weigh the full picture of risks and rewards for yourself. Start by lining up the 3 key rewards and 2 important warning signs.
Looking for more Yangzijiang Shipbuilding investment ideas?
Do not stop with Yangzijiang Shipbuilding (Holdings). Broaden your watchlist now, or you risk missing other high quality opportunities hiding in plain sight.
- Identify potential upgrade candidates that combine quality and possible mispricing by scanning the 182 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient payers using the 162 dividend fortresses.
- Reduce the likelihood of unpleasant surprises by filtering for resilient companies through the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com