
Sherwin-Williams (SHW) Maps Out Growth To $25 Billion, Is It Still 16% Undervalued?
Sherwin-Williams (SHW) has outlined a clear growth roadmap, targeting more than US$25b in annual sales by 2026 through store openings, productivity gains, and increased investment in digital tools.
Sherwin-Williams shares closed at US$329.10 after a 1-day share price return of 2.72%. However, the 30-day share price return is down 5.61%, and the 1-year total shareholder return has slipped 2.83%, even after a 32.51% total shareholder return over three years. This suggests near-term momentum has cooled, while the longer record still reflects meaningful gains.
Scan how Sherwin-Williams compares with other materials stocks that may be setting up for the next move using our hand-picked 32 high quality undervalued stocks.
Sherwin-Williams looks like a solid operator with a clear playbook, yet the share price has gone sideways after its recent pullback. So at about US$329, are you paying up for quality or getting it at a reasonable tag?
Most Popular Narrative: 16% Undervalued
At a fair value estimate of about $390 per share versus Sherwin-Williams at $329.10, the prevailing narrative frames the stock as underpriced while still heavily tied to execution on its growth playbook and end-market demand.
The company's sustained focus on cost control, broad and deep restructuring (doubling annual savings targets to approximately $80 million), and disciplined SG&A management is structurally improving fixed cost leverage and expected to yield improved net margins and earnings power as sales volumes recover.
Ongoing construction of a new R&D center and increased R&D investment is expected to accelerate the rollout of premium, environmentally friendly, and specialty coatings that command higher price points, supporting future gross margin expansion and increasing competitive differentiation as sustainability and performance requirements intensify.
See why 39 investors see Sherwin-Williams as 16% undervalued.
Result: Fair Value of $390 (UNDERVALUED)
Still, weak demand in key housing related markets and pressure on Consumer Brands and Performance Coatings margins could challenge the underpriced Sherwin-Williams narrative if conditions stay soft.
Find out about the key risks to this Sherwin-Williams narrative.
Another View: Sherwin-Williams Through The P/E Lens
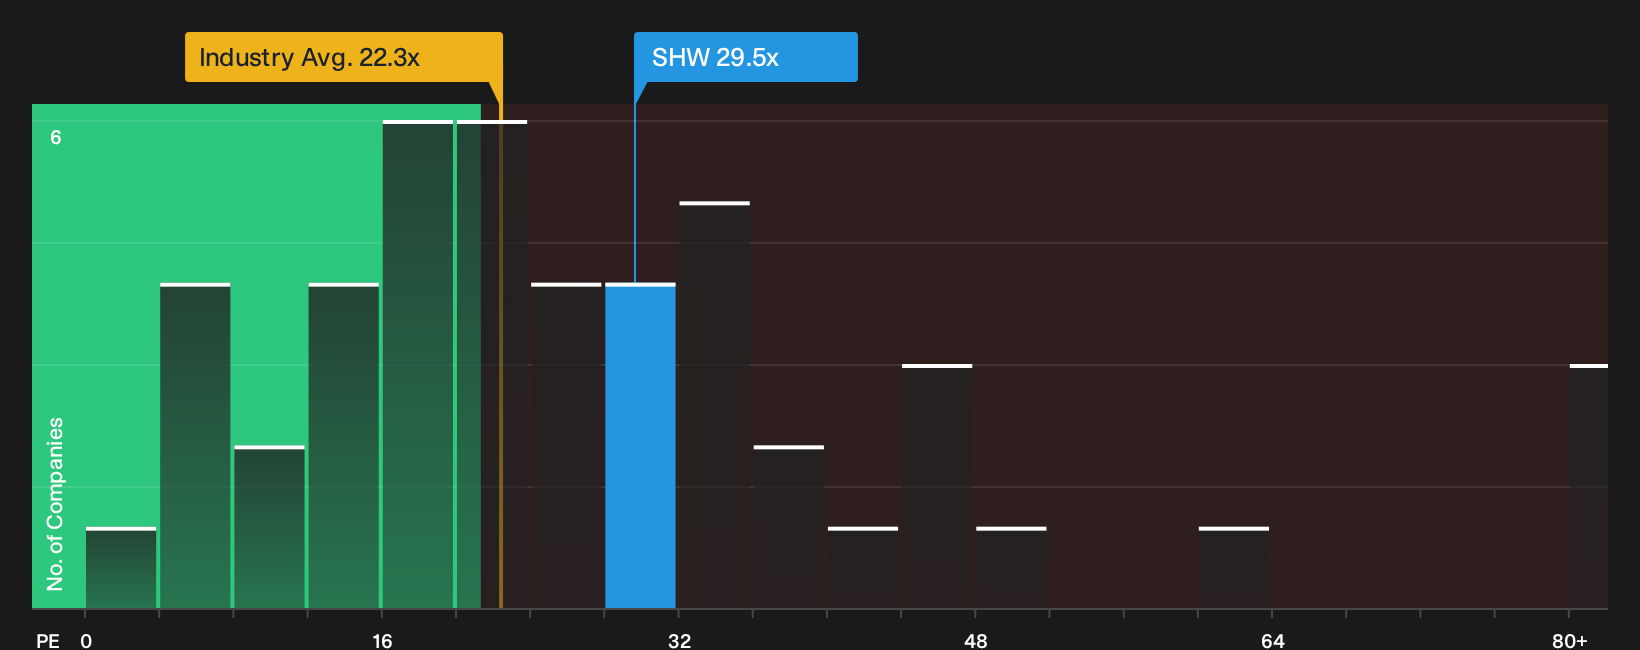
The first narrative leans on future cash flows and a fair value near $390. Yet on simple P/E maths, Sherwin-Williams looks expensive. The current multiple of 29.5x sits well above the estimated fair ratio of 22.7x, the US Chemicals industry at 22.3x, and peers at 21.4x.
That gap points to valuation risk if the market ever decides Sherwin-Williams should trade closer to its fair ratio, or closer to sector and peer levels. The question for you is whether the quality of the business and its execution record are sufficient to justify paying this kind of premium today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can be frustrating, especially when Sherwin-Williams carries both clearly flagged risks and some appealing upside drivers. Move quickly and pressure test the data yourself, starting with the balance of 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Sherwin-Williams?
You have a clear read on Sherwin-Williams now, so do not stop there. Broaden your watchlist with fresh ideas tailored to different investing angles.
- Target resilient cash generators by scanning our list of solid balance sheet and fundamentals (24 results) that focus on stability and underlying financial strength.
- Hunt for potential mispriced opportunities by reviewing the hand picked 32 high quality undervalued stocks that match your return and risk preferences.
- Build a recurring income stream by checking out our 8 dividend fortresses that aim to combine yield with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com