
Trevi Therapeutics (TRVI) Following Its Pullback Still Carries An Undervalued Narrative
Trevi Therapeutics (TRVI) has drawn fresh attention after recent share price moves, with the stock down 19.6% over the past month and 20.6% over the past three months while remaining positive year to date.
Short term momentum for Trevi Therapeutics has cooled, with the share price down over the past week and month. However, the 1-year total shareholder return of 64.31% and a very large 5-year total shareholder return show longer term holders have still seen substantial gains.
Scan beyond Trevi Therapeutics to see how it compares with a hand picked group of 16 high quality undiscovered gems that are also catching attention for their long term return profiles and fundamentals.
After Trevi Therapeutics slipped from recent highs yet still sits on hefty multi year gains, the real focus now is simple: Does the current valuation still leave enough upside to justify the clinical and cash burn risk?
Most Popular Narrative: 49% Undervalued
Against Trevi Therapeutics' last close of $14.41, the most followed narrative points to a fair value of $28.18. This frames the current drawdown as a valuation gap rather than a broken story.
Approximately US$188 million in cash, cash equivalents and marketable securities at year end 2025 with an indicated runway into 2028 funds top line data across key IPF, non IPF ILD and refractory chronic cough studies. This limits near term financing pressure and can support more controlled decision making around future capital structure, share count and potential earnings per share.
See why 1 investors see Trevi Therapeutics as 49% undervalued.
Result: Fair Value of $28.18 (UNDERVALUED)
Still, the Trevi Therapeutics story leans heavily on a single drug, and any trial delay or extra capital raise could quickly challenge the current rerating narrative.
Find out about the key risks to this Trevi Therapeutics narrative.
Another View On Trevi Therapeutics' Valuation
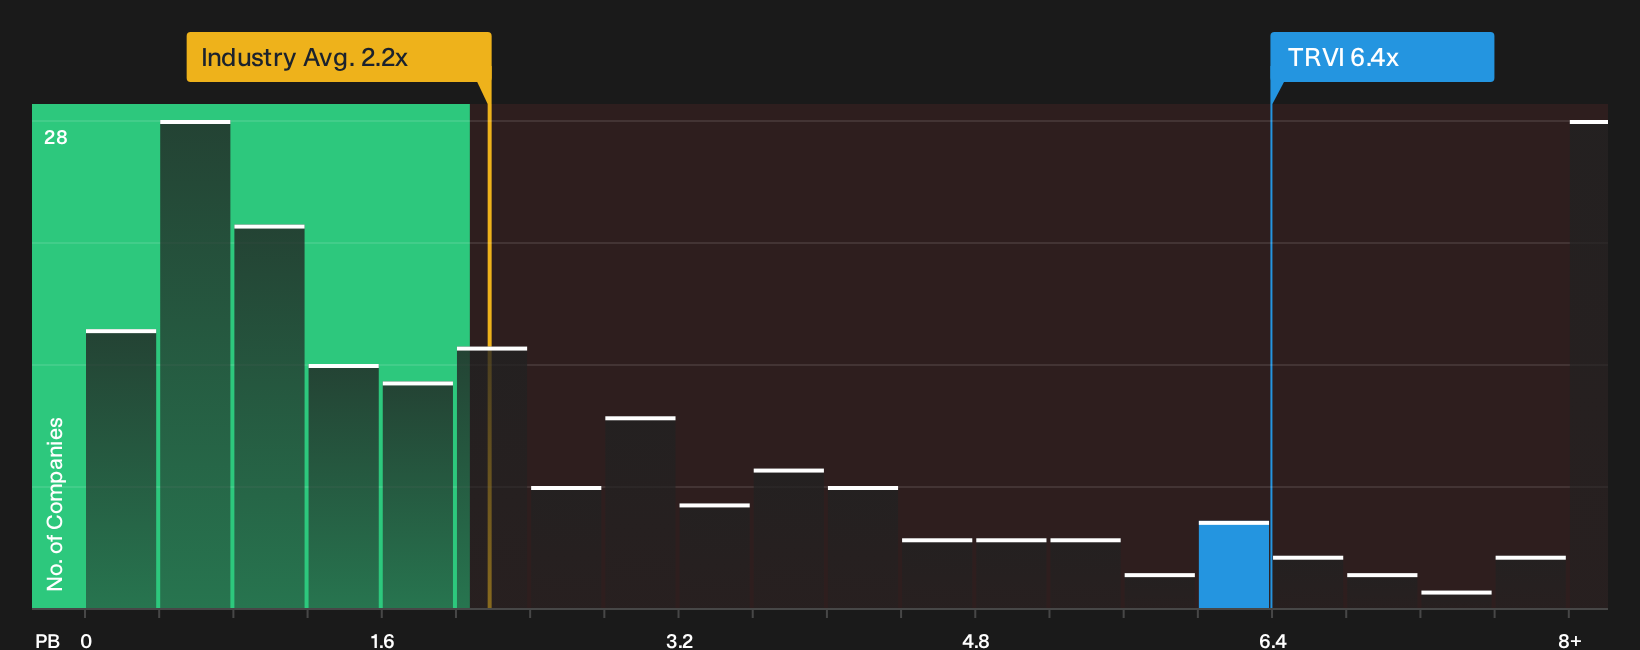
The analyst fair value of $28.18 suggests Trevi Therapeutics looks cheap on future earnings assumptions. On book value though, the picture flips. The stock trades on a P/B of 6.4x, compared with 2.2x for the wider US Pharmaceuticals group and 4.1x for peers, which signals investors are already paying a premium for its pipeline. The key question is whether a single asset story justifies that kind of mark up if timelines slip or sentiment cools.
See what the numbers say about this price in more detail in our valuation breakdown, including how that P/B premium stacks up over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Trevi Therapeutics is mixed, so treat this as your prompt to dig into the numbers yourself and move early if the thesis still works for you. To pressure test that view against the bear case, start with the 4 important warning signs.
Looking for more Trevi Therapeutics style ideas?
If Trevi Therapeutics has sharpened your focus on risk, reward and valuation, do not stop here. Broader opportunity sets often reveal stronger fits for your own investing style.
- Target steady compounding by reviewing a curated 32 high quality undervalued stocks that pair quality fundamentals with prices that still look restrained.
- Prioritise resilience by checking a list of solid balance sheet and fundamentals (24 results) that can better handle funding cycles and tougher credit conditions.
- Boost your income watchlist by scanning 8 dividend fortresses that combine higher yields with disciplined payout habits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com