
3 U.S. Bank Stocks Built For Higher Interest Rates
Interest rates just moved higher again, and that ripple through borrowing costs, loan demand and insurer investment income is reshaping where risk and reward sit in financial markets. Some banks and insurance stocks may now see margins or investment returns shift in ways many portfolios are not yet priced for, which can create both openings and traps. This article walks through three U.S. financial stocks exposed to this rate shock and explains how each could be affected.
The three stocks below are just a sample of what higher rates can mean for banks and insurers, and the full screen surfaced 38 more companies with similarly detailed investment stories that are not covered here. To identify and analyze your own highest conviction ideas across this theme, head straight to the U.S. Bank and Insurance Stocks (Beneficiaries of Higher Interest Rates) screener.
John Marshall Bancorp (JMSB)
Overview: John Marshall Bancorp is a community-focused bank holding company that funds loans with customer deposits across the Washington, D.C. region.
Operations: The bank generates its entire US$66.9 million of revenue from core banking activities in the United States, mainly lending and deposit services.
Market Cap: US$324.3 million
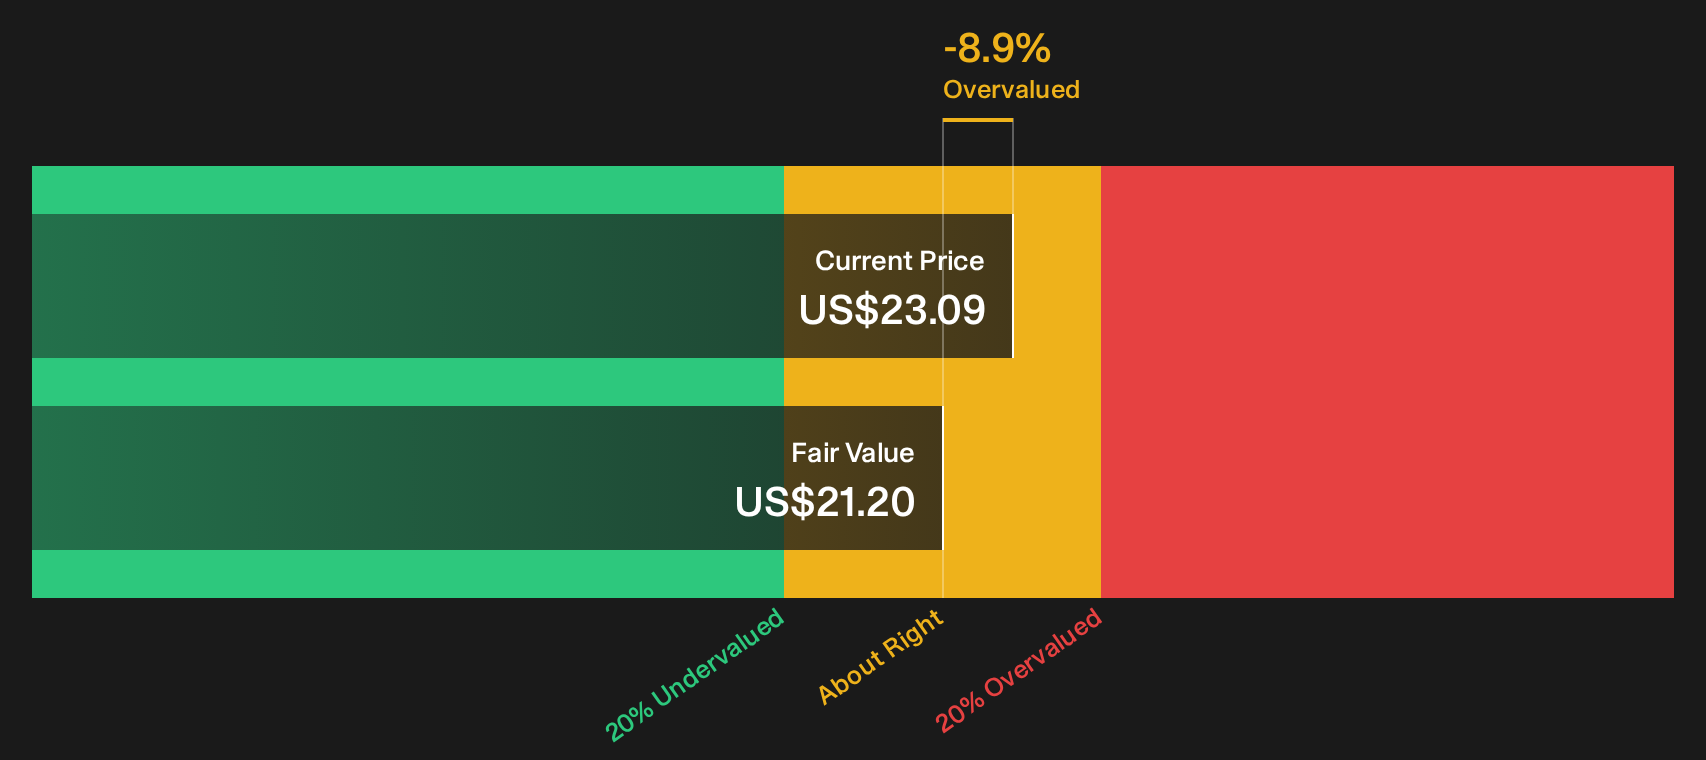
John Marshall Bancorp sits squarely in the higher rate beneficiary camp, with lending funded by deposits, rising net interest income, and a recent net profit margin of 36.4%. Forecasts for faster earnings and revenue growth add context to a P/E of 13.3x. What ultimately matters for investors is how one quiet pressure on future margins and returns actually resolves.
That margin question is exactly what the DCF valuation analysis for John Marshall Bancorp helps you unpack so you can see whether today’s P/E really reflects the higher rate upside.
Isabella Bank (ISBA)
Overview: Isabella Bank is a century-old Michigan bank holding company that provides traditional lending, deposits, and wealth management services closely tied to interest rates.
Operations: Isabella Bank generates US$83.2 million from retail banking operations in the United States, primarily through deposit taking and lending activities.
Market Cap: US$293 million
Higher rates push borrowing costs up for customers. Isabella Bank’s forecast 27.33% annual earnings growth and 24% net margin are key reasons this rate-sensitive lender appears in a screener focused on banks that may benefit from wider net interest margins. What really matters now is how changes in funding costs and loan pricing ultimately affect its profitability.
That profitability tug of war is exactly what the analysis report for Isabella Bank helps you unpack before earnings expectations and funding costs decouple further.

Citizens & Northern (CZNC)
Overview: Citizens & Northern is a regional bank holding company providing traditional deposit accounts, lending, wealth management, and insurance services across Pennsylvania and New York.
Operations: Citizens & Northern generates US$127.3 million from community banking in the United States, reflecting a primarily interest income driven model.
Market Cap: US$460.9 million
Citizens & Northern operates within the higher rate theme, with a classic community banking model built on net interest income, a 4.36% dividend yield, and forecast earnings growth linked to wider margins. Investors watching banks that could be affected by each Fed hike may find that the story centers on how one quieter pressure on funding costs develops.
That quiet funding pressure is exactly what the 3 key rewards and 3 important warning signs reveals, so you can see where Citizens & Northern risk may be masking upside.

Curious About What You Might Be Missing?
Fresh ideas move first, and markets rarely wait. Spot where momentum could be building or quietly dropping under the radar for now, then get in early.
- Hunt for resilient cash machines by scanning a curated list of solid balance sheet and fundamentals (24 results) that may hold up when weaker balance sheets start to feel the strain.
- Target potential income anchors with a focused 8 dividend fortresses that spotlights companies combining higher yields with robust fundamentals while it still flies under most radars.
- Chase real business traction through 37 profitable AI stocks that aren't just burning cash that highlight AI players already turning technology into earnings momentum before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com