
How Investors May Respond To Leidos (LDOS) Army Contract Extension
- Leidos Holdings recently secured a U.S. Army contract worth up to US$127 million to continue operating the ARTEMIS airborne ISR platform in Europe and other regions through 2027, providing aircraft, mission systems, and support under a contractor owned, contractor operated model.
- The contract extends a long running Army relationship on ARTEMIS, reinforcing Leidos Holdings' role in high altitude intelligence collection that relies on integrated digital, cyber, and mission software capabilities.
- Next, the focus will be on how Leidos Holdings' extended ARTEMIS ISR work could shape the broader investment narrative around government contracts.
Scan how Leidos Holdings' new Army work compares with other defense contractors by reviewing the hand picked 40 power grid technology and infrastructure stocks now shaping critical infrastructure and mission readiness.
Leidos Holdings Investment Narrative Recap
To own Leidos Holdings, you need to believe in a long pipeline of complex government work that leans heavily on digital modernization, ISR and mission software. The ARTEMIS extension fits neatly into that view, but at up to US$127 million, it looks incremental next to a business generating more than US$17.6b in revenue.
The more immediate swing factor is contract execution and margins on large defense and IT programs, not this single Army award. The key risk stays the same. Heavy dependence on U.S. federal budgets and high leverage could bite if funding priorities or pricing pressure move against Leidos Holdings.
The Navy Marine Corps enterprise network contract option, worth US$875 million for the second year, is the clearest companion to the new ARTEMIS work. Both underline how Leidos Holdings is embedded in day to day mission operations, from airborne ISR to secure connectivity across more than 2,500 sites and 425,000 devices.
For catalysts, that Navy deal shows how digital modernization, cyber work and automation feed into recurring service revenue and potential efficiency gains. It also highlights concentration risk. A large portion of future execution now hinges on delivering reliably for a handful of massive contracts under tight security and performance expectations.
Leidos Holdings' current analyst narrative points to revenues of US$20.7b and earnings of US$1.6b by 2029, based on a 5.4% yearly revenue growth rate and an earnings increase of about US$200m from US$1.4b today.
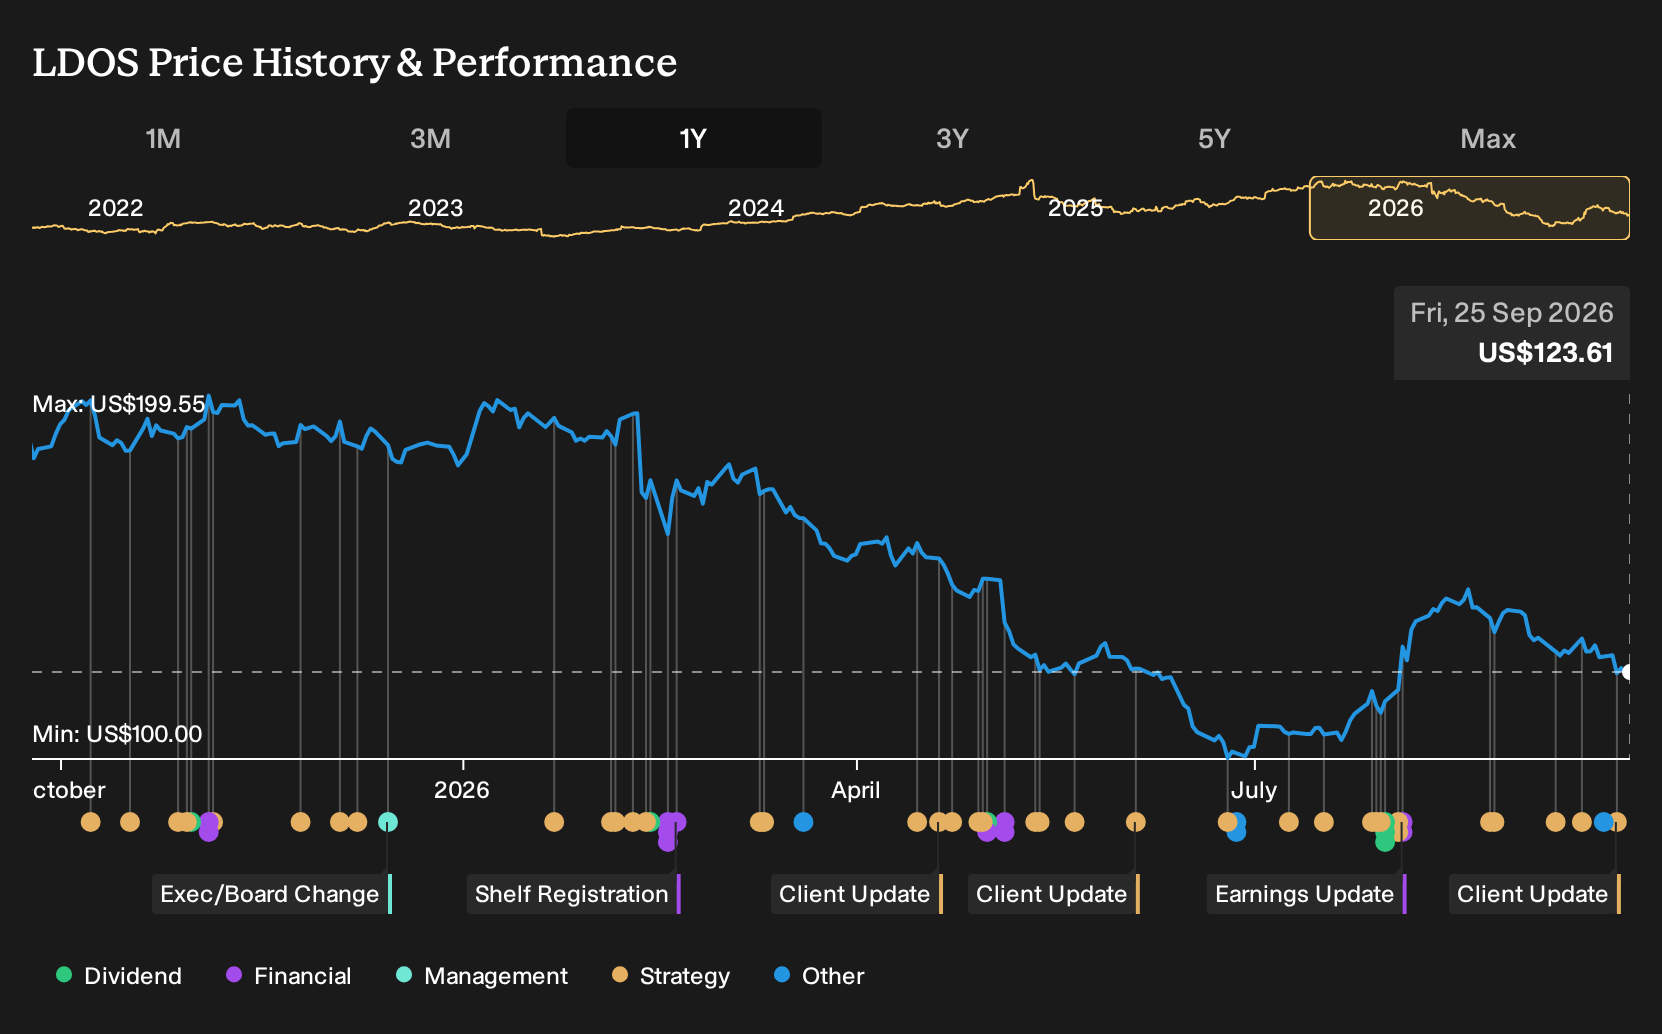
Uncover why Leidos Holdings' fair value indicates a 27% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate take on Leidos Holdings leans hard into margin risk. The most cautious analysts were pencilling in revenue of about US$20.3b and flat earnings around US$1.4b by 2029 before this ARTEMIS news. That is a much cooler story than consensus and it shows how far views can spread. Use it as a cue to explore multiple scenarios before deciding what this latest contract might mean for you.
Explore 2 other Leidos Holdings fair value estimates, including one that suggests it could be worth just $156.60!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Leidos Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Leidos Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leidos Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Leidos Holdings?
Once you have a handle on Leidos Holdings, it often helps to widen the lens and compare it with other listed businesses that fit different risk and income profiles. The Simply Wall St Screener can surface targeted sets of stocks so you can test your thesis, pressure check your assumptions, and avoid anchoring on a single government contractor.
- If you want potential upside with less balance sheet strain, scan a 30 resilient stocks with low risk scores that keep financial risk scores in check.
- For investors who care about both resilience and income, review a 8 dividend fortresses that combine elevated yields with a focus on durability.
- If you are hunting for underfollowed stories rather than household tickers, filter through a 16 high quality undiscovered gems that already show solid fundamentals but get limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com