
Enterprise Financial Services (EFSC) Draws Fresh Attention, Is The Valuation Still About Right?
Enterprise Financial Services (EFSC) drew fresh attention after its recent share price movement, with the stock last closing at US$60.93. Investors are weighing that level against the bank's earnings profile and regional footprint.
Viewed over a longer stretch, Enterprise Financial Services has paired a 12.73% year to date share price return with a 5.92% one year total shareholder return. The 73.86% three year and 45.37% five year total shareholder returns point to momentum that has built over time rather than faded.
Scan beyond Enterprise Financial Services and compare its trajectory with a curated 32 high quality undervalued stocks that pair established track records with balance sheets built to handle tougher cycles.
After that run, investors are left with a simple tension: Has Enterprise Financial Services already done most of the heavy lifting, or does the current valuation still leave meaningful room for upside from here?
Price-to-Earnings of 11.8x: Is it justified?
Enterprise Financial Services is on a modest earnings multiple, with the stock trading on a P/E of 11.8x at a last close of $60.93. That level leaves the valuation sitting slightly above the wider US Banks industry average but below the tighter peer group used in the comparison.
The P/E ratio compares the current share price to earnings per share. For a regional bank like Enterprise Financial Services that is already profitable and established, it is a straightforward way for investors to weigh what they are paying today against the business's current earnings power.
EFSC screens as expensive against the broader US Banks industry, where the average P/E is 11.6x, which is only a small gap but still puts the stock on the richer side of that benchmark. Against a closer peer set, the picture flips. Enterprise Financial Services is described as good value on 11.8x compared with a 13.3x peer average, and the ratio is also aligned with the estimated fair P/E of 11.8x, which is the level the market could gravitate toward over time.
Explore the SWS fair ratio for Enterprise Financial Services.
Result: Price-to-Earnings of 11.8x (ABOUT RIGHT)
Still, the story can change quickly if Enterprise Financial Services faces credit losses in its loan book or a weaker funding mix that increases pressure on deposit costs.
Find out about the key risks to this Enterprise Financial Services narrative.
Another View: What The SWS DCF Model Says
The P/E workup paints Enterprise Financial Services as roughly fairly judged, yet the SWS DCF model tells a different story. On that framework, EFSC at $60.93 is trading at a steep discount to an estimated future cash flow value of $102.29, which implies meaningful upside if those cash flows materialise.
That kind of gap can look like a cushion for long term holders or a sign that the cash flow assumptions are simply too optimistic. The real question is which side of that argument you trust more.
Look into how the SWS DCF model arrives at its fair value.
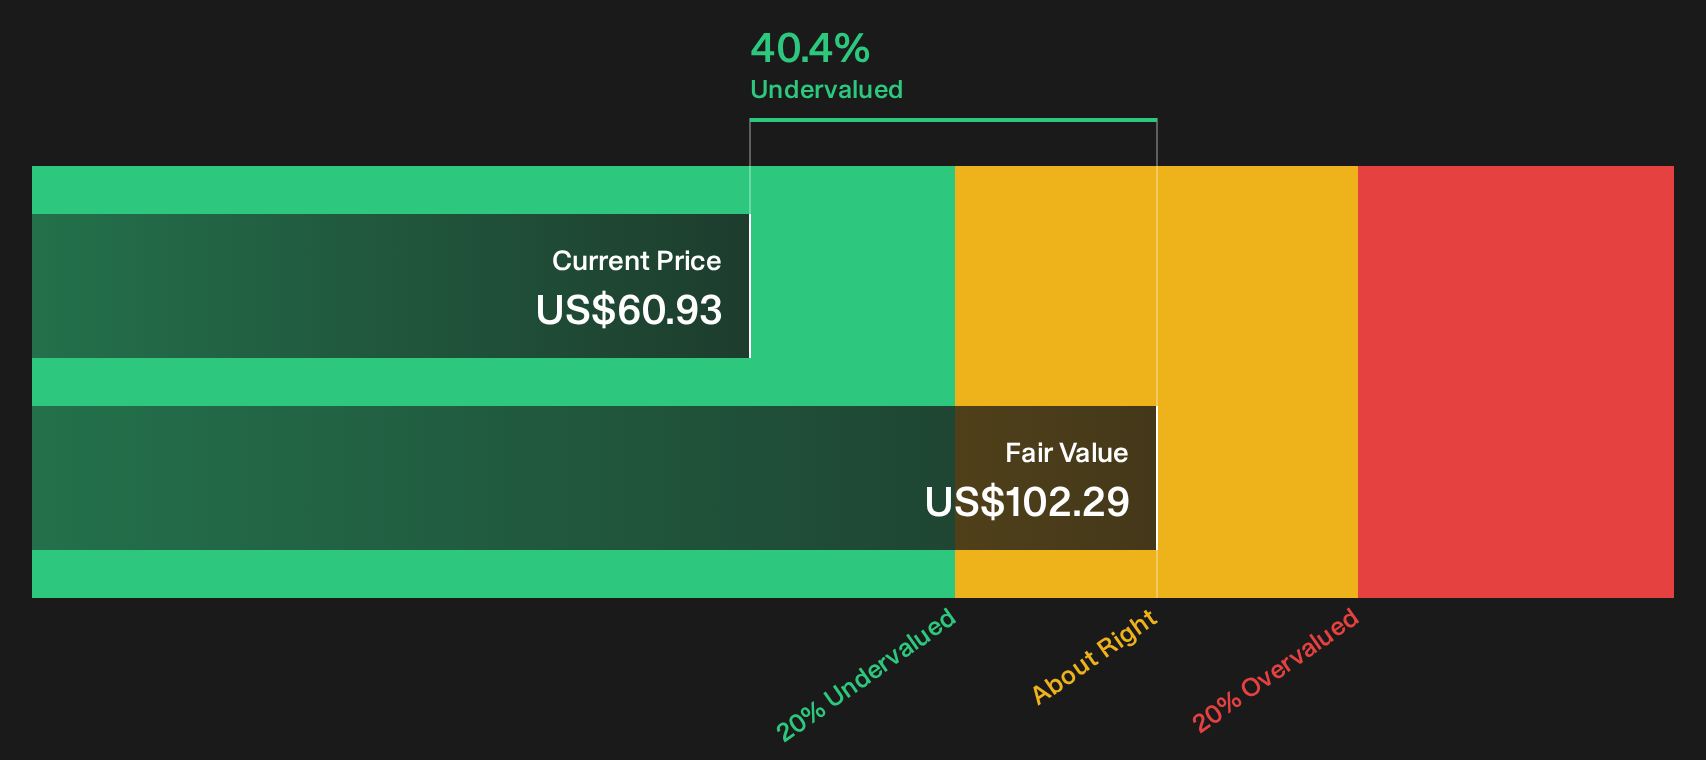
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enterprise Financial Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Wondering whether the market mood around Enterprise Financial Services lines up with your own instincts today? Act while the data is fresh and pressure test the upside case for yourself by reviewing the 3 key rewards.
Looking for more investment ideas beyond Enterprise Financial Services?
If Enterprise Financial Services has sharpened your focus on valuation and risk, consider broadening your watchlist with a few targeted stock ideas built from the same data driven toolkit.
- Target income potential by scanning companies with robust payout profiles and strong coverage metrics through the 8 dividend fortresses.
- Focus on resilient balance sheets by running a targeted search using the list of solid balance sheet and fundamentals (24 results).
- Explore overlooked opportunities by filtering for quality fundamentals within the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com