
How Investors May Respond To OceanaGold (TSX:OGC) High Grade Drill Results
- OceanaGold reported past drill results from 16 holes at its Wharekirauponga project in New Zealand, with wide, high grade gold intercepts that support converting parts of the southern zone from Inferred to Indicated resources.
- The company has increased drilling capacity to five rigs and is targeting a high grade zone that lies partly outside the current resource model. This could reshape how investors think about the Waihi district’s long term production profile.
- Now the focus shifts to how OceanaGold's broader investment narrative could be affected by these high grade Wharekirauponga drill results.
OceanaGold Investment Narrative Recap
To own OceanaGold, you need to be comfortable with a multi asset miner that leans heavily on solving operating bottlenecks at Haile, Macraes and Didipio while trying to grow through projects such as Wharekirauponga and Waihi North. The short term catalyst still sits in how reliably existing mines convert into cash, not in any one drill result.
The Wharekirauponga intercepts and extra rigs matter most as support for future technical reports and resource conversions rather than near term cash flow. The bigger near term risk remains execution problems like harder ore, resequenced stopes, weather and inflation that could push costs higher while heavy site spending is already required.
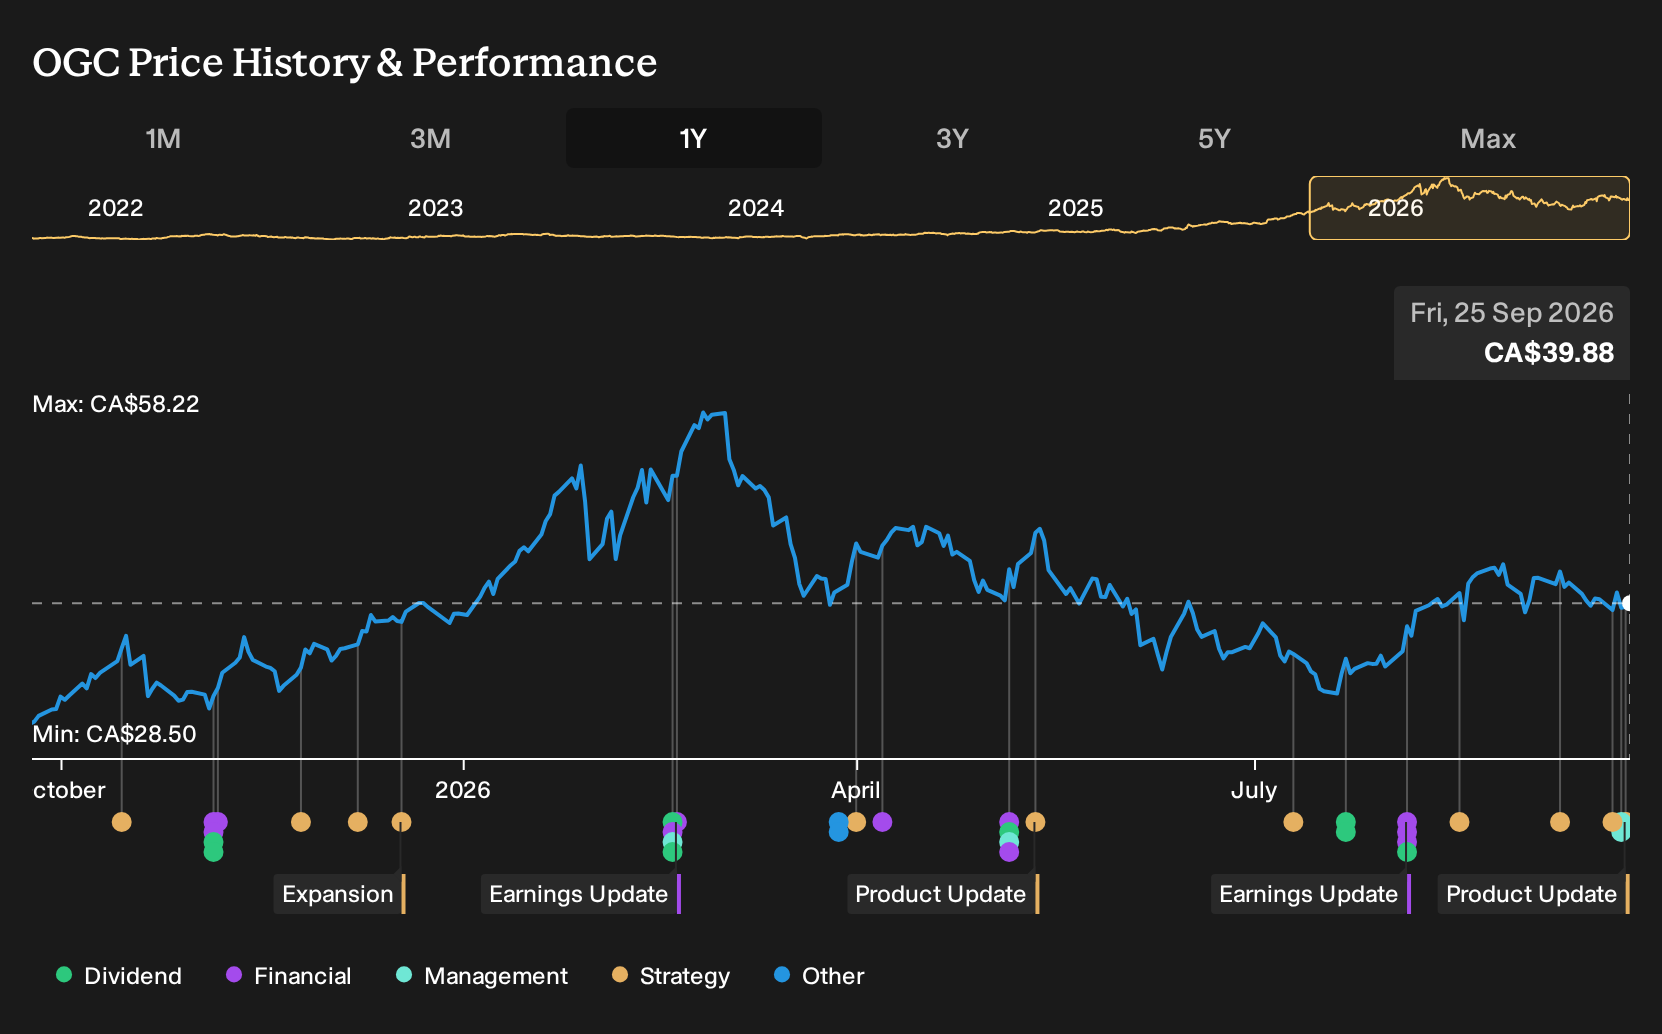
The Wharekirauponga drilling update ties directly into an earlier OceanaGold comment about evaluating an expansion of the Waihi processing plant from 0.8 million tons a year to 1.2 million tons. Strong grades and continuity at EG and the HW veins help justify doing the engineering work needed to run Martha Underground and Wharekirauponga at the same mill.
For you as a shareholder, that processing decision sits near the top of the catalyst list, because it links a high grade discovery story to real tonnes and cash generation. It also raises execution questions. Any mill expansion and dual mine feed heightens exposure to permitting, capital cost control, labour availability and the same environmental risks already present across the rest of the portfolio.
OceanaGold's current analyst story points to revenues of $2.2b and earnings of $764.2 million by 2028, built on an assumed 12.7% yearly revenue growth rate and an earnings increase of about $388.4 million from $375.8 million today.
Uncover why OceanaGold's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate take on OceanaGold focuses less on Wharekirauponga drill excitement and more on gold price risk. The lowest analysts were already cautious, building their story around slower 4.5% yearly revenue growth and earnings of about $1.4b by 2029 from $757.4 million. Their view could shift if these intercepts reshape confidence.
Explore 7 other OceanaGold fair value estimates, including one that suggests it could be worth just CA$40.31.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OceanaGold research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for OceanaGold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OceanaGold's overall financial health at a glance.
Looking for more OceanaGold sized investment ideas?
If the OceanaGold story has you thinking about position sizing, risk and upside in your wider portfolio, it can help to line it up against a broader set of opportunities using the Simply Wall St screener.
- If you want potential upside with stronger fundamentals behind it, scan through a 9 high quality undiscovered gems that may not yet be on most investors' radar.
- For a more defensive tilt, focus on a 8 resilient stocks with low risk scores that could help you build a portfolio with steadier risk scores across different sectors.
- When resilience and financial strength matter most, filter for a list of solid balance sheet and fundamentals (7 results) to compare OceanaGold with companies that pair lower leverage with healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com