
What Is Driving Attention Around Avnet (AVT) Today?
Why Tributary’s Move Put Avnet In Focus
Tributary Capital Management’s new position in Avnet (AVT) during Q2 2026 has drawn fresh attention to the distributor, tying the thesis to profit trends rather than short term trading.
The fund is pointing to demand linked to datacenter buildouts, a potential sales recovery in the Farnell unit, and improving conditions across industrial, automotive, and aerospace customers after inventory normalization.
Avnet’s share price has climbed 19.34% over the past 90 days and 108.91% year to date, while its 5 year total shareholder return of 207.91% points to strong longer term compounding. Momentum has accelerated recently due to the Tributary position and an improving profit narrative.
Scan how Avnet compares to other component suppliers benefiting from similar demand trends by reviewing the hand picked 87 AI infrastructure stocks in this space.
After a near doubling of Avnet’s share price over the past year and a value score of 2, the question is whether the current setup still compensates buyers for the risks they are taking from this point onward.
Most Popular Narrative: 3% Undervalued
Analysts following Avnet see fair value at $106.25 versus a last close of $103.08, which leaves only a small implied upside and puts the focus squarely on whether its profit mix can justify that gap.
Expanded investment in digital infrastructure, proprietary customer platforms, and improved e-commerce capabilities, particularly at Farnell, strengthen customer experience and retention, enhancing Avnet's ability to capture market share in high-growth sectors (cloud/AI, industrial automation, EVs). This is expected to drive higher-margin recurring revenues and operating leverage.
See why 9 investors see Avnet as 3% undervalued.
Result: Fair Value of $106.25 (UNDERVALUED)
Still, pressure on gross margins from faster growing Asian sales and the risk of prolonged weakness in EMEA could quickly challenge the current Avnet thesis.
Find out about the key risks to this Avnet narrative.
Another View On Avnet’s Valuation
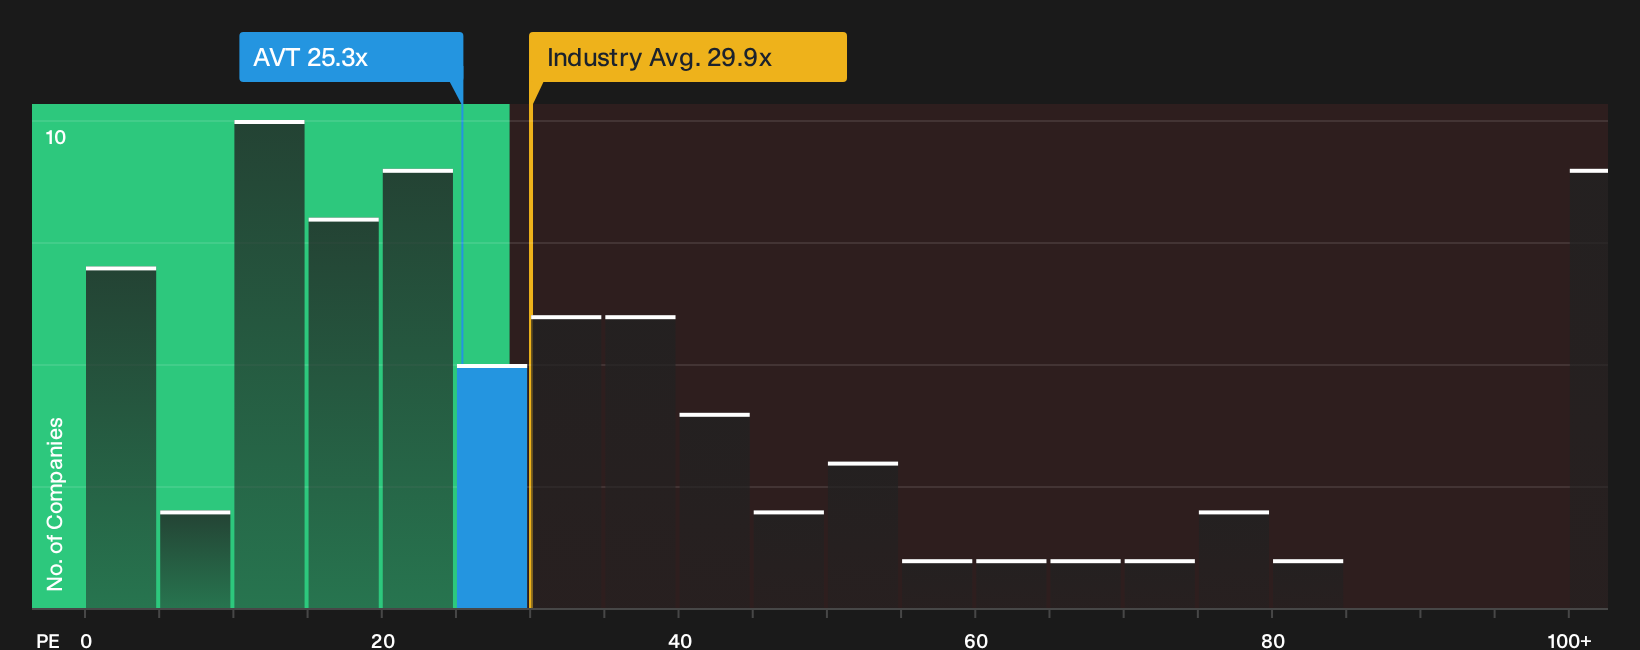
On a simple P/E lens, Avnet looks more expensive than its closest peer group at 25.3x earnings versus 16.7x, yet still below the broader US Electronic industry on 30.1x. The fair ratio model points to 42.5x, which suggests the market could still shift meaningfully from here in either direction. Which reference point do you trust most when sizing valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Avnet so far. If you want to move quickly and build your own view from the ground up, start with the balance of 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Avnet?
Avnet might be on your radar now, but the best opportunities often sit just outside the obvious choices. Give yourself options before the next move.
- Target resilience first by scanning a 30 resilient stocks with low risk scores that aims to keep downside shocks in check while you focus on long term compounding potential.
- Hunt for underappreciated quality with a 16 high quality undiscovered gems that filters for strong fundamentals hiding behind quieter tickers.
- Prioritise financial strength by using a list of solid balance sheet and fundamentals (24 results) that spotlights businesses with the kind of backing that helps them handle rough patches.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com