
How Incoming CEO Priorities Will Impact Toro (TTC) Stock
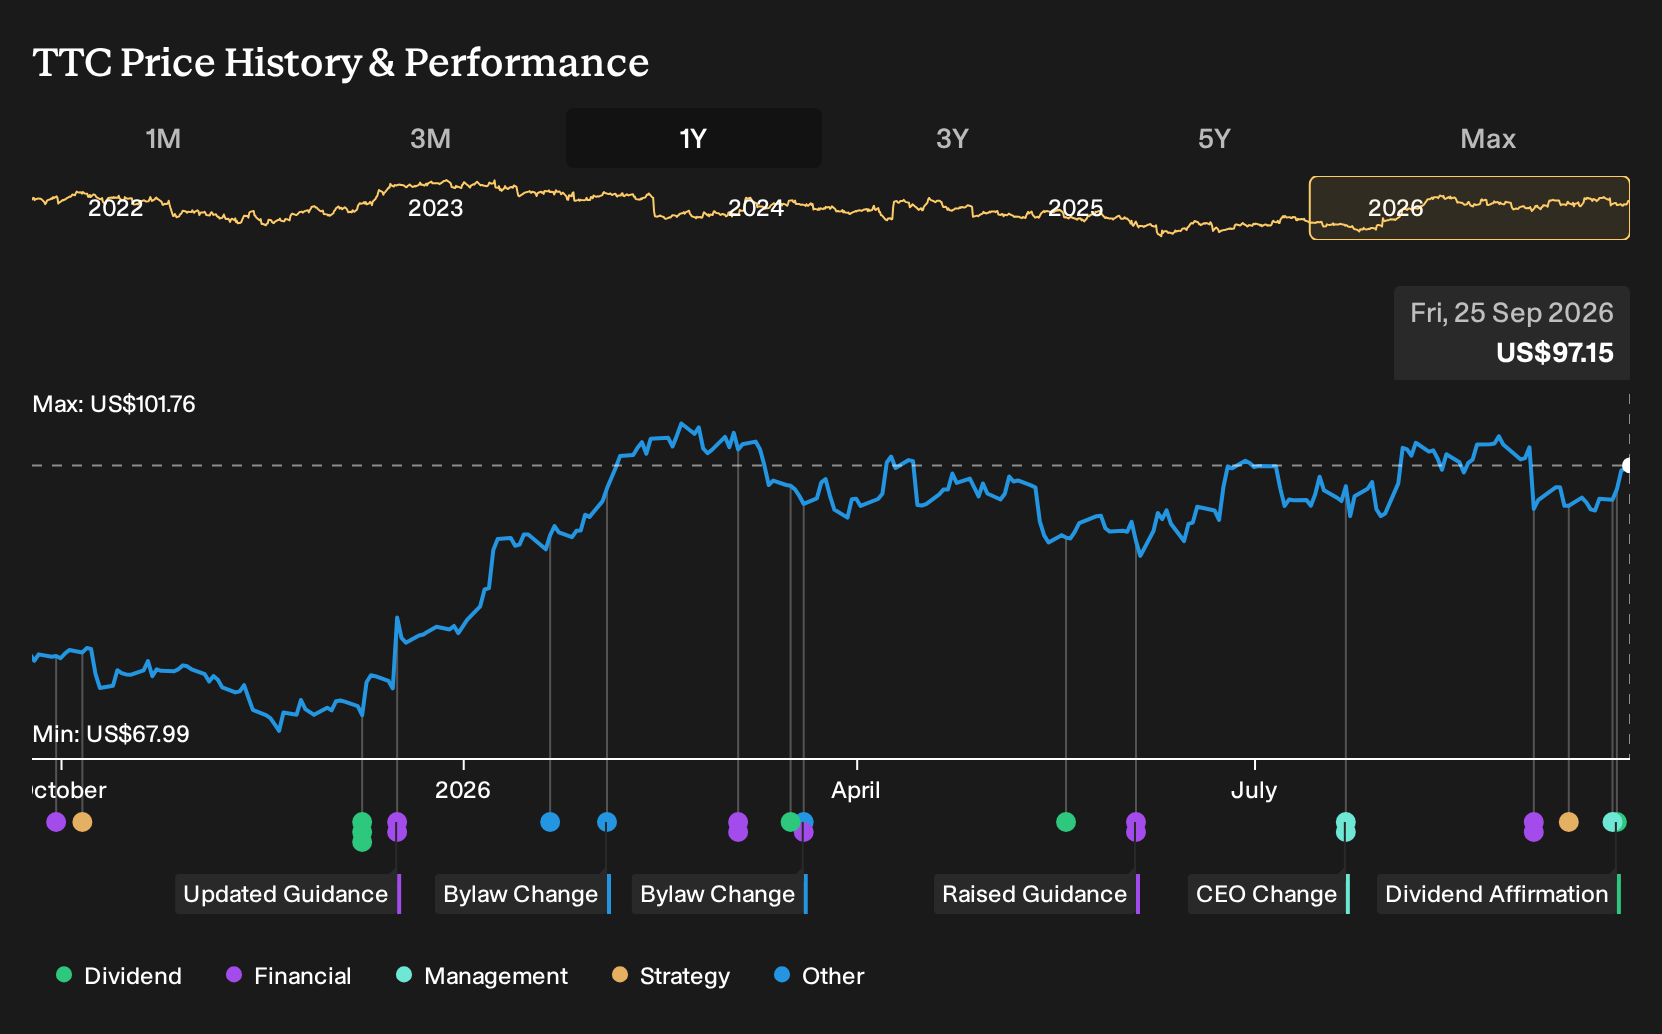
- The Toro Company confirmed a regular quarterly cash dividend of $0.39 per share, payable on October 20, 2026, to holders of record as of October 6. The company also expanded its Board to eleven directors with the appointment of David W. Huml to both the Audit and Finance Committees.
- The recent Board expansion and leadership focus on productivity savings, autonomous equipment, and electrification highlight Toro’s push to tighten execution while prioritizing higher value professional and infrastructure markets.
- We will look at how Toro's investment narrative is shaped by Edric Funk's emphasis on technology driven productivity and professional markets.
Scan how Toro’s dividend move and leadership reshuffle compare with other industrials by running the hand picked roster of 40 power grid technology and infrastructure stocks alongside this latest TTC update.
Toro Investment Narrative Recap
Toro asks you to believe that professional turf and infrastructure equipment can carry the story while residential demand and weather sensitive categories remain choppy. The big near term swing factor is how effectively those higher margin professional lines and productivity savings offset softness in homeowners and snow driven products.
The fresh dividend affirmation does not fundamentally change that setup. It reads more as business as usual capital returns while Toro works on cost savings, automation, and electrification. The key risk stays the same. Prolonged weak residential demand and unpredictable snowfall could keep a lid on operating leverage even as new tech heavy equipment rolls out.
The most relevant update here is Toro’s decision to add David Huml, Tennant’s CEO, to the Board and to both the Audit and Finance Committees. That move adds more industrial and cleaning equipment expertise directly into financial oversight at a time when Toro is focusing on productivity savings and selective capital spending.
For catalysts, investors are watching how Toro executes on automation, connected equipment, and electrification in professional markets. Huml’s background in global operations and marketing could help pressure test major investments, balance sheet choices, and pricing actions. The potential benefit is cleaner execution on growth projects. The key risk is that high debt and cyclical demand may still limit how quickly Toro can move.
Toro earnings setup behind the board and dividend moves
Toro's longer term story on automation and professional markets now sits against a consensus model that is fairly specific about revenue, profit margins, and earnings by the late 2020s. Analysts are building in steadier demand for higher value turf and infrastructure equipment while still acknowledging choppy residential spending and weather risk in the background.
The current forecasts tie those product and efficiency efforts to a 3.8% yearly revenue growth rate over the next three years, with profit margins projected to move from 7.3% today to 10.5% in that same window. On earnings, the analyst group is working off current profit of US$339.8 million and a consensus that earnings could reach US$546.9 million, or US$5.76 per share, by 2029. That implies an increase of roughly US$207 million in annual profit over the period, which is a meaningful step up that depends heavily on professional segment mix, productivity savings, and execution on electrified and autonomous equipment.
Those same assumptions feed into how the stock is being valued. Analysts are effectively saying that for you to align with their view, Toro would need to deliver about US$5.2b of revenue and US$546.9 million of earnings in 2029. In that scenario, the shares would trade on a P/E multiple of 22.5x instead of the current 26.6x. The implied future multiple also sits below the current 27.5x P/E referenced for the wider US Machinery industry, so the story leans more on actual profit delivery and less on an expanding valuation. That setup matters if residential demand stays weak or snowfall remains unpredictable because it leaves less room for disappointment on the earning power that is being penciled in.
Toro's narrative projects about US$5.2b in revenue and US$546.9 million in earnings by 2029. That framework uses a 3.8% yearly revenue growth rate and assumes earnings rise by roughly US$207 million from about US$339.8 million today.
Uncover why Toro's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor for Toro is demand for golf and grounds equipment. The most cautious analysts already assumed revenue of about US$5.2b and earnings of roughly US$546.1 million by 2029, using a lower 20.6x P/E. Both Board changes and the fresh dividend could eventually shift that story, so compare these viewpoints yourself.
Explore 2 other Toro fair value estimates, including one that suggests it could be worth just $109.25.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toro research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Toro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toro?
If Toro has sharpened your interest in equipment and infrastructure stories, broaden your watchlist by scanning other companies through the Simply Wall St Screener and see how their dividends, balance sheets, and valuations stack up.
- If income is a priority, review companies that combine higher yields with resilience using the 8 dividend fortresses.
- For those who care most about financial strength, start with businesses that pair sturdy balance sheets with solid fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you want ideas that are off the beaten path, comb through a curated pool of under-followed opportunities using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com