
DexCom (DXCM) Tests Its Execution Story After Expanding Its CFO Role
DexCom (DXCM) has just expanded Jereme Sylvain’s remit, moving him from pure finance chief to a combined Chief Financial Officer and Chief Operating Officer role that now spans global operations and quality.
Recent trading has been choppy for DexCom, with the share price down 3.1% over the past week and 3.0% over the past month, following a 23.5% 90 day share price return and a 30.2% year to date gain that signal rebuilding momentum.
Compare DexCom’s leadership shift with other medically focused businesses by scanning our hand picked list of 38 healthcare AI stocks, which highlights similar execution and operations themes.
For DexCom, a rising track record on recent returns now meets a bigger execution bet on its CFO turned COO. Does that combination still leave more upside than risk at today’s valuation?
Most Popular Narrative: 8% Undervalued
Against DexCom's last close at $86.62, the most followed narrative pegs fair value at $94.48. This places the stock at a modest discount and frames the new CFO and COO structure in the context of an already fairly constructive earnings path.
Expansion of DexCom CGM use into type 2 non insulin and prediabetes care is supported by the CONNECT trial results, growing U.S. commercial coverage for more than 7 million type 2 non insulin lives and participation in FDA’s TEMPO pilot. Together these factors point to a larger addressable base that can support future revenue growth.
See why 78 investors see DexCom as 8% undervalued.
Result: Fair Value of $94.48 (UNDERVALUED)
Still, the DexCom narrative could be knocked off course if Medicare competitive bidding pressures CGM pricing, or if the Ireland plant ramp weighs heavier on margins.
Find out about the key risks to this DexCom narrative.
Another View: What DexCom’s P/E Is Really Saying
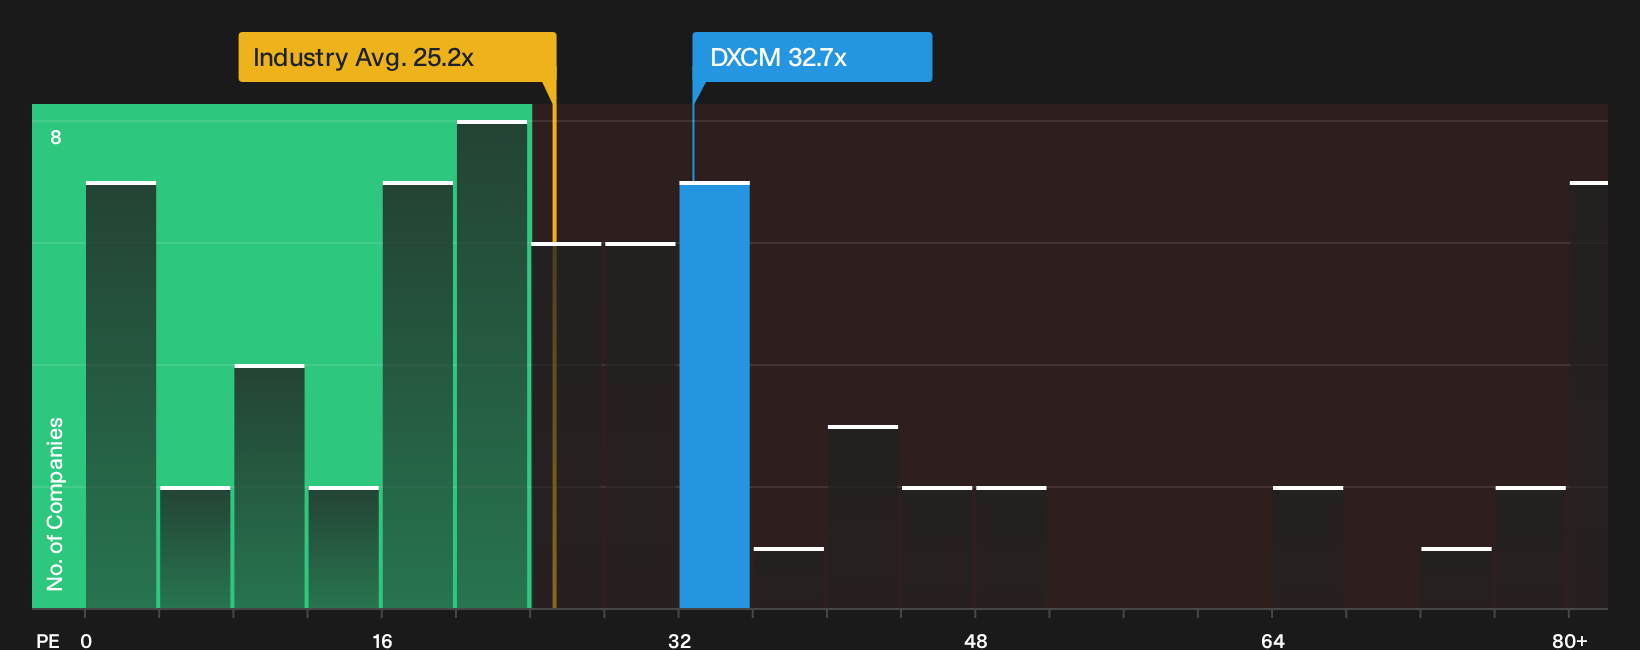
The bullish fair value of $94.48 sits against a market that already prices DexCom at a P/E of 32.7x. That is higher than both the Medical Equipment industry on 25.2x and peers at 30.7x, and it matches the 32.7x fair ratio that the market could eventually lean toward.
This richer multiple suggests investors are already paying up for DexCom's earnings quality and growth profile, which leaves less room for error if the growth path or margins slip. Is that premium something you are comfortable underwriting, or does it push you to demand an even larger margin of safety at the current price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this DexCom story feels finely balanced between optimism and caution, it may be useful to review the underlying numbers and shape your own stance. To see what others view as the key bright spots, start with the 3 key rewards.
Looking For More Investment Ideas Beyond DexCom?
If DexCom has sharpened your appetite for focused opportunities, do not stop here. Broader idea hunting can help you build a stronger, more resilient portfolio.
- Target quality at a discount by scanning companies flagged in our 32 high quality undervalued stocks to see which ones align with your return and risk expectations.
- Prioritize resilience by reviewing the list of solid balance sheet and fundamentals (24 results) so you are not caught out when conditions turn against weaker financial structures.
- Hunt for potential future leaders hiding in plain sight by checking the 16 high quality undiscovered gems before the crowd turns its attention their way.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com