
Home BancShares (HOMB) Could Be 11% Undervalued Following Zacks Upgrade And Dividend Focus
Analyst upgrade and dividend profile put Home BancShares in focus
Home BancShares (HOMB) moved into the spotlight after a recent upgrade to Zacks Rank #2, following growing optimism around its earnings prospects and a dividend profile that has drawn fresh investor attention.
The recent upgrade and dividend story come on top of a share price that has edged higher year to date, with a 4.6% year to date share price return. Longer term total shareholder returns of 52.2% over three years and 37.6% over five years point to momentum that has been building rather than fading.
Short term trading has been choppy, with the share price slipping around 2.1% over the past month. The Zacks Rank #2 upgrade and focus on Home BancShares' dividend sustainability look like fresh catalysts that may be reshaping how investors weigh its earnings outlook against perceived risk.
Scan how Home BancShares compares to other banks showing resilient balance sheets and steady fundamentals using our hand picked list of solid balance sheet and fundamentals (24 results) for this part of the market.
So after a solid multi year run, a recent wobble, and fresh optimism around earnings and income, does Home BancShares still offer enough upside to justify the risk at today’s price, or has the easy reward already been taken?
Most Popular Narrative: 10% Undervalued
On the most followed view of Home BancShares, a fair value of $32.29 sits modestly above the recent $29.19 close. This focuses attention on how sustainable its earnings and balance sheet strength really are.
The company's strong presence and loan growth in high-growth markets such as Texas, Florida, and Arkansas positions it to capture outsized revenue and deposit growth as economic and population expansion in these Sun Belt states continues, supporting sustained top-line growth.
See why 2 investors see Home BancShares as 10% undervalued.
Result: Fair Value of $32.29 (UNDERVALUED)
Still, if credit losses rise in concentrated lending areas or if future acquisitions prove harder to integrate cleanly, the fair value narrative around Home BancShares could shift quickly.
Find out about the key risks to this Home BancShares narrative.
Another View on Home BancShares' valuation
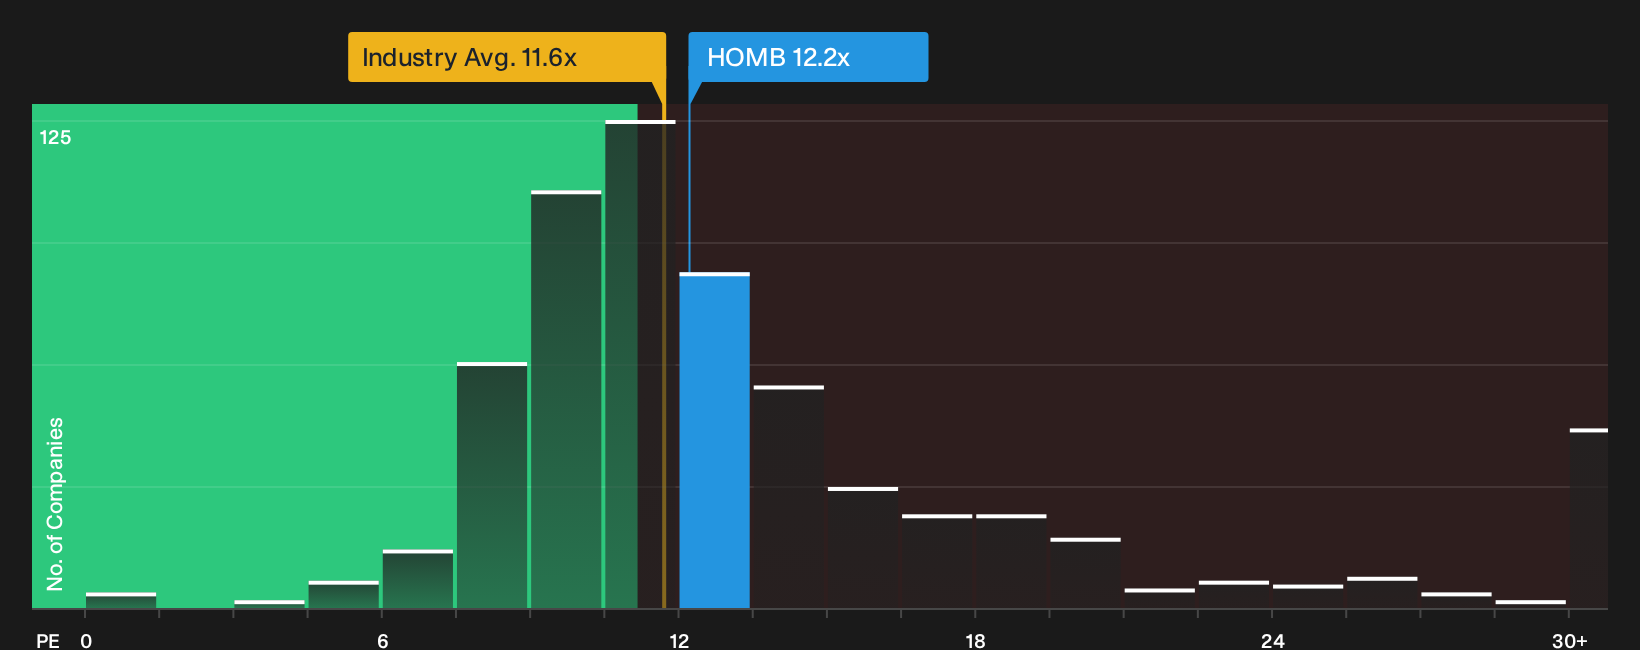
The first narrative leans on discounted cash flows and lands on Home BancShares as modestly undervalued at $32.29 per share, compared with the recent $29.19 price. A different lens tells a cooler story. On earnings, the stock trades on a P/E of 12.2x versus a fair ratio of 11.8x, which implies some valuation risk if sentiment cools rather than improves.
Compared with similar banks, Home BancShares looks cheaper than peers on that same P/E yardstick at 12.2x versus a 13.8x peer average, yet slightly richer than the broader US Banks industry at 11.6x. That mix of modest premium to the sector and discount to closer comparables raises the question of which reference point may matter most for future returns.
To see how that earnings based view fits into the rest of the picture, including how history and assumptions interact, take a look at the valuation breakdown and our fair ratio workup for HOMB, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around value, income, and risk can be confusing, so move quickly, check the underlying numbers for Home BancShares, and weigh the trade off yourself. To see how the positives and red flags compare side by side, review the 4 key rewards and 1 important warning sign.
Looking for more Home BancShares investment ideas?
If Home BancShares has your attention, do not stop here. Use the Simply Wall St screener to find fresh ideas that could round out your portfolio.
- Target higher potential returns by scanning a focused group of opportunities through the 8 elite penny stocks with strong financials.
- Strengthen your core holdings by reviewing a curated pool of quality companies that may trade below their estimated worth with the 32 high quality undervalued stocks.
- Build a steadier income stream by searching for dependable payout candidates using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com