
EnerSys (ENS) Rides Battery Demand Growth, Is The Stock Still Cheap?
Recent reports on the global VRLA and automotive lead acid battery markets have spotlighted EnerSys (ENS) as a key supplier, with investor focus sharpening as demand trends tie directly to backup power and automotive applications.
EnerSys shares have cooled off after a strong run, with the 30-day share price return down 7.29% and the 90-day move down 19.38%, even though the year-to-date share price return is 18.68% and the 1-year total shareholder return sits at 61.23%. This suggests earlier enthusiasm around backup power and automotive battery demand has eased, but longer term holders have still seen substantial gains.
Scan beyond EnerSys and size up peers riding similar backup power and automotive trends with our hand-picked 40 power grid technology and infrastructure stocks as potential beneficiaries of the same demand drivers.
EnerSys now trades at a level where a recent pullback meets a wide gap to analyst and intrinsic estimates. Is the stock already reflecting fair value, or does that spread still point to mispricing?
Most Popular Narrative: 28% Undervalued
The most followed valuation storyline on EnerSys pegs fair value at $247.29 per share, well above the last close at $178.89. This puts a clear gap between narrative assumptions and where the stock changes hands today.
Ongoing recovery in U.S. communications and robust growth in Data Center deployments, both driven by upgrades to broadband and expansion of digital infrastructure, are expected to fuel accelerating demand for EnerSys' energy storage solutions, supporting multi-year revenue growth. EnerSys is embedding IoT and predictive analytics capabilities into its products, enabling cross-selling of higher-value services and energy management solutions, which should expand the addressable market and support both top-line growth and margin improvement over time.
See why 31 investors see EnerSys as 28% undervalued.
Result: Fair Value of $247.29 (UNDERVALUED)
Still, EnerSys faces real pressure if trade policy keeps shifting or if acquisitions like Bren Tronics fail to deliver the expected lift to organic demand.
Find out about the key risks to this EnerSys narrative.
Another View: EnerSys And Cash Flow Fair Value
The popular story around EnerSys leans on analyst targets and earnings forecasts. A different lens, the Simply Wall St DCF model, points to a fair value of $175.15 per share, slightly below the current $178.89 level. That tilts this framework toward mild overvaluation. Which anchor do you treat as your reference point?
Look into how the SWS DCF model arrives at its fair value.
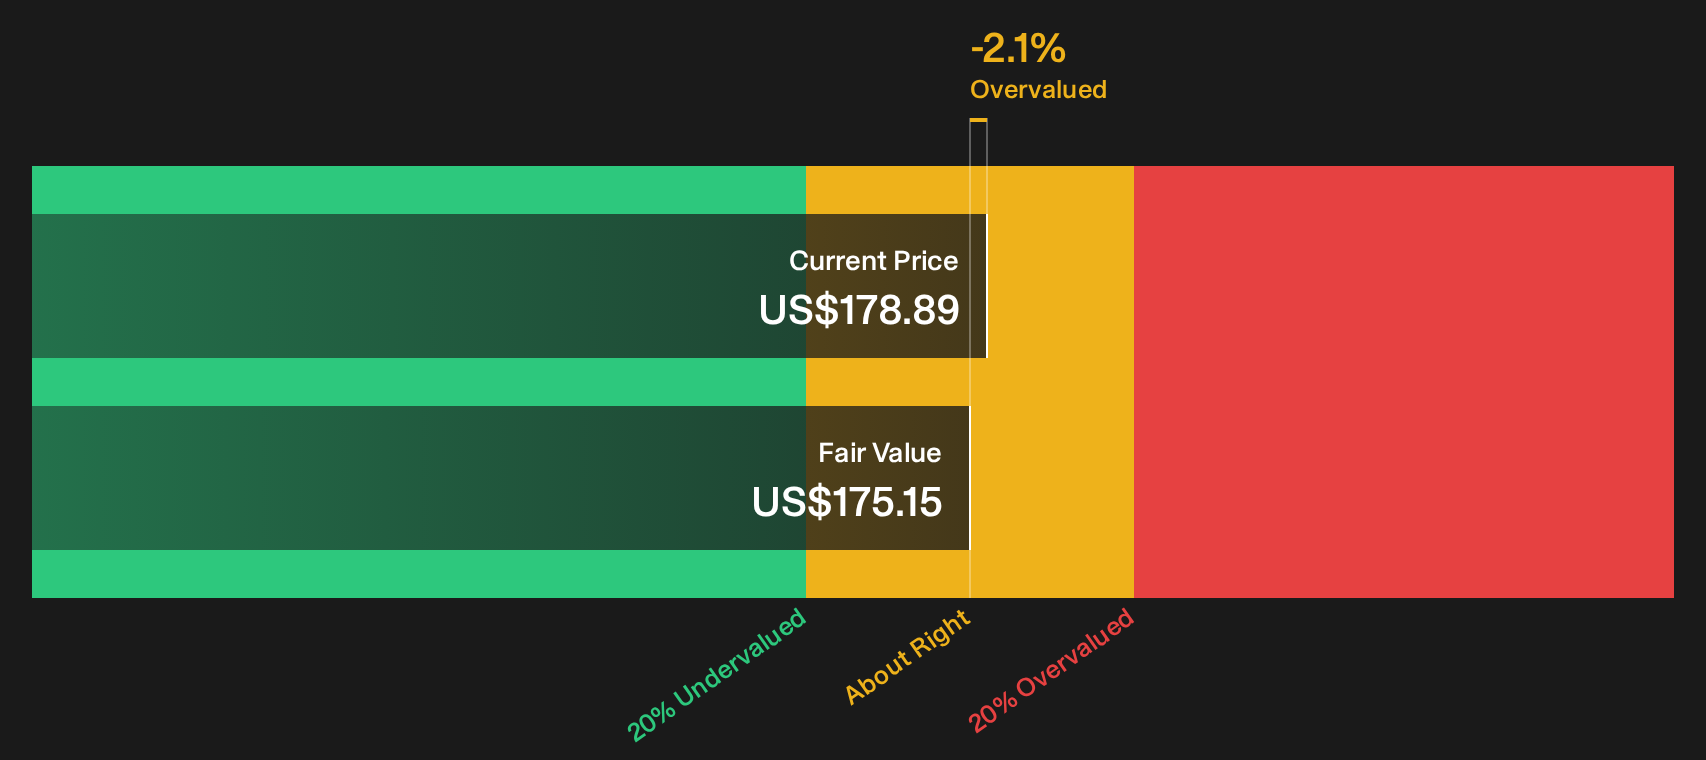
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EnerSys for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling conflicted by the push and pull in the EnerSys story so far? Put the numbers in context quickly and shape your own take, then review the potential upside signals in the 5 key rewards.
Looking for more EnerSys sized investment ideas?
If EnerSys has sharpened your thinking on valuation and risk, do not stop here. Broaden your opportunity set with curated lists that surface stocks meeting clear, disciplined criteria across quality, value, and resilience.
- Target firms where strong cash generation and attractive pricing intersect by running your filters through the 32 high quality undervalued stocks.
- Strengthen your income stream by scanning companies with substantial yields and payout histories using the 8 dividend fortresses.
- Prioritize staying power and capital preservation by focusing on businesses highlighted in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com