
Markets await Monday news of US-China trade discussions
Howdy market watchers!
September is quickly coming to an end with long awaited moisture finally falling across much of the agricultural areas of the country. It is perfect timing ahead of winter wheat seeding in the Southern Plains although less timely for row crops starting to be harvested in the Midwest.
A break from the extreme heat and drought conditions are however welcome for soybeans that are still filling out. While rainfall has still been limited in many areas with much more on the horizon in the week ahead, the grass is already much greener from the weather shift.
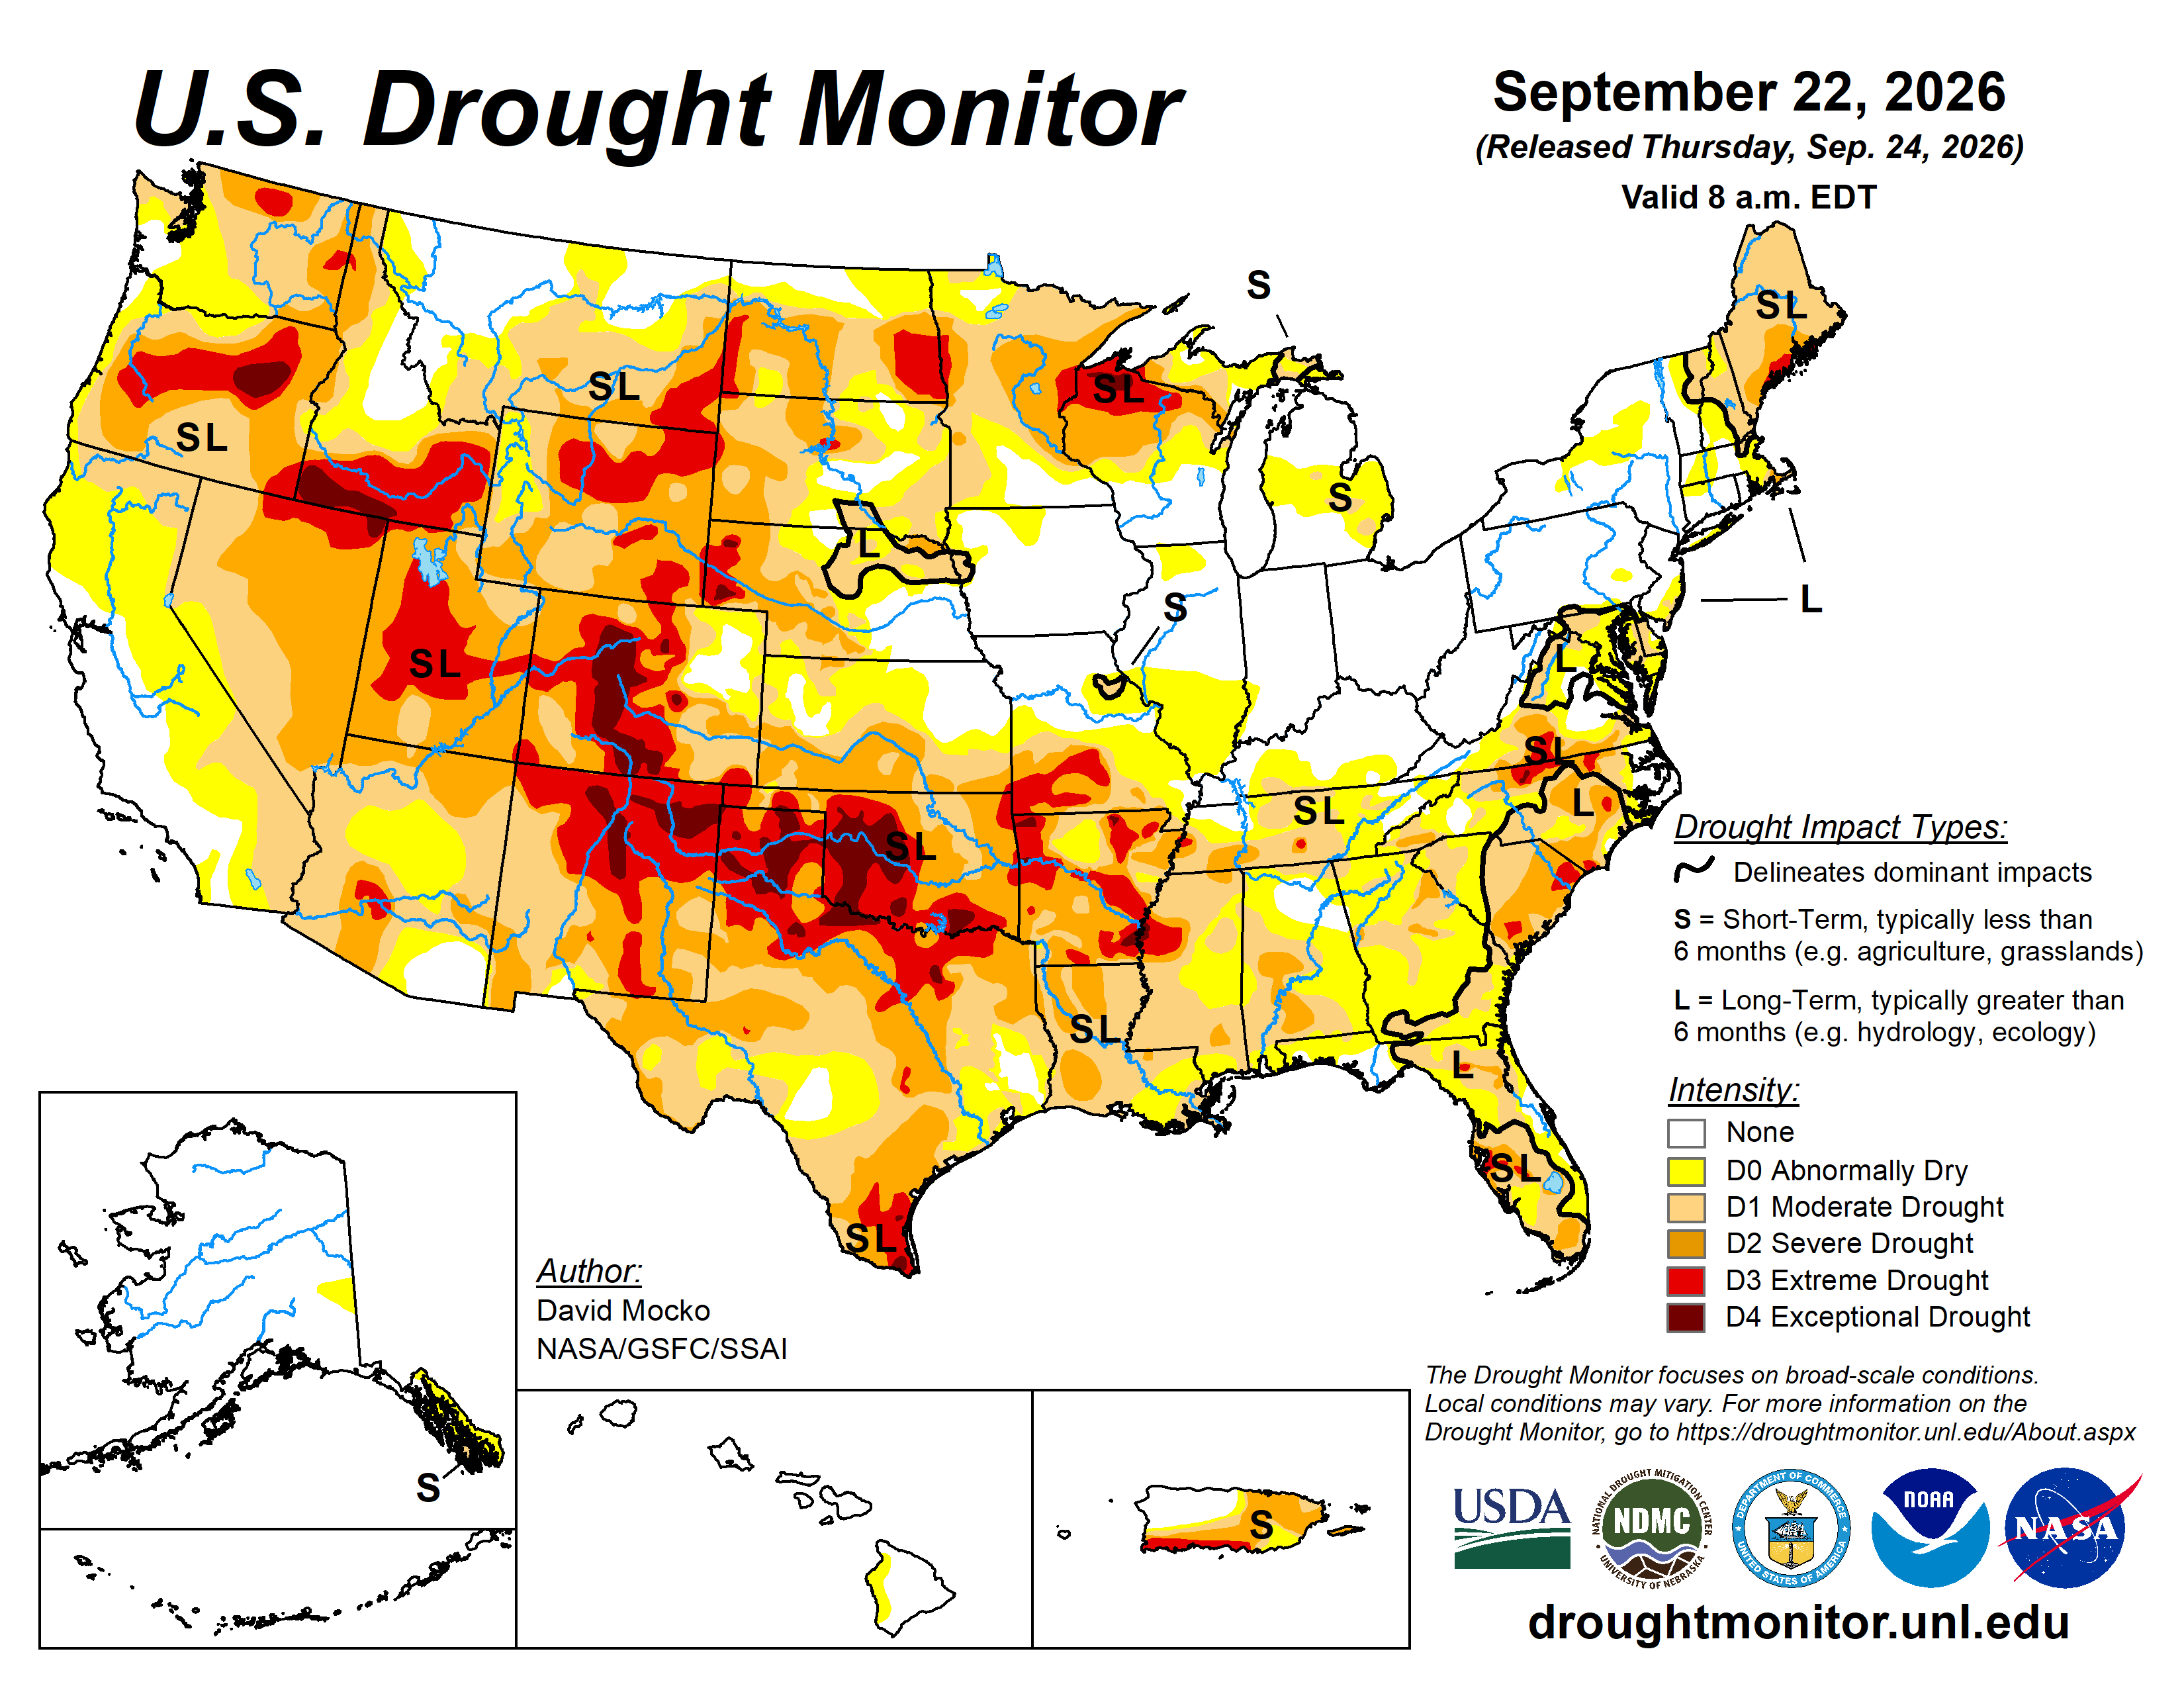
The latest drought monitor still shows a lot of progress remains to be made to restore normal conditions across the South and High Plains. High hopes for the super El Nino continue for late 2026 that would dramatically alter what we’ve been accustomed to over the past several months. We pray they materialize for the sake of winter as well as spring crops. It could, however, mean fewer windows for application and so be ready to take action when the opportunity presents itself.
Meanwhile, this pattern shift means drought conditions in Australia and parts of Asia that could increase export demand for American farmers. One can only hope that will be the case along with continued progress in US-China relations after the grandstanding in Washington, DC this week.
After living and working in Asia for 10 years, I fully understand “giving face” to your counterpart, but the grandiose of the overture to President Xi was not reflective of the current state of the relationship given the issues that divide us. Much of this “State Visit” was form over substance although we will apparently find out the “trade deals” made on Monday. This gives time for both sides to agree on the language and timelines so as not to overcommit politically, which is more critical for President Trump than his Chinese counterpart.
The market was hoping and expecting more immediate news overnight into Friday’s session, the lack of which saw heavy pressure across the grain and oilseed complex. However, with whispers that deals had been made with a forthcoming announcement, there were strong recoveries off the lows into Friday’s close.
In fact, corn and soybeans closed positive on the day after sharp losses overnight into the post biscuit session. With rain delays, soybean basis has firmed near crushing plants with strong demand met with limited supply due to a slow start to harvest. Be sure to ask about this at your delivery point and get all you can get if you’re beans are dry enough!
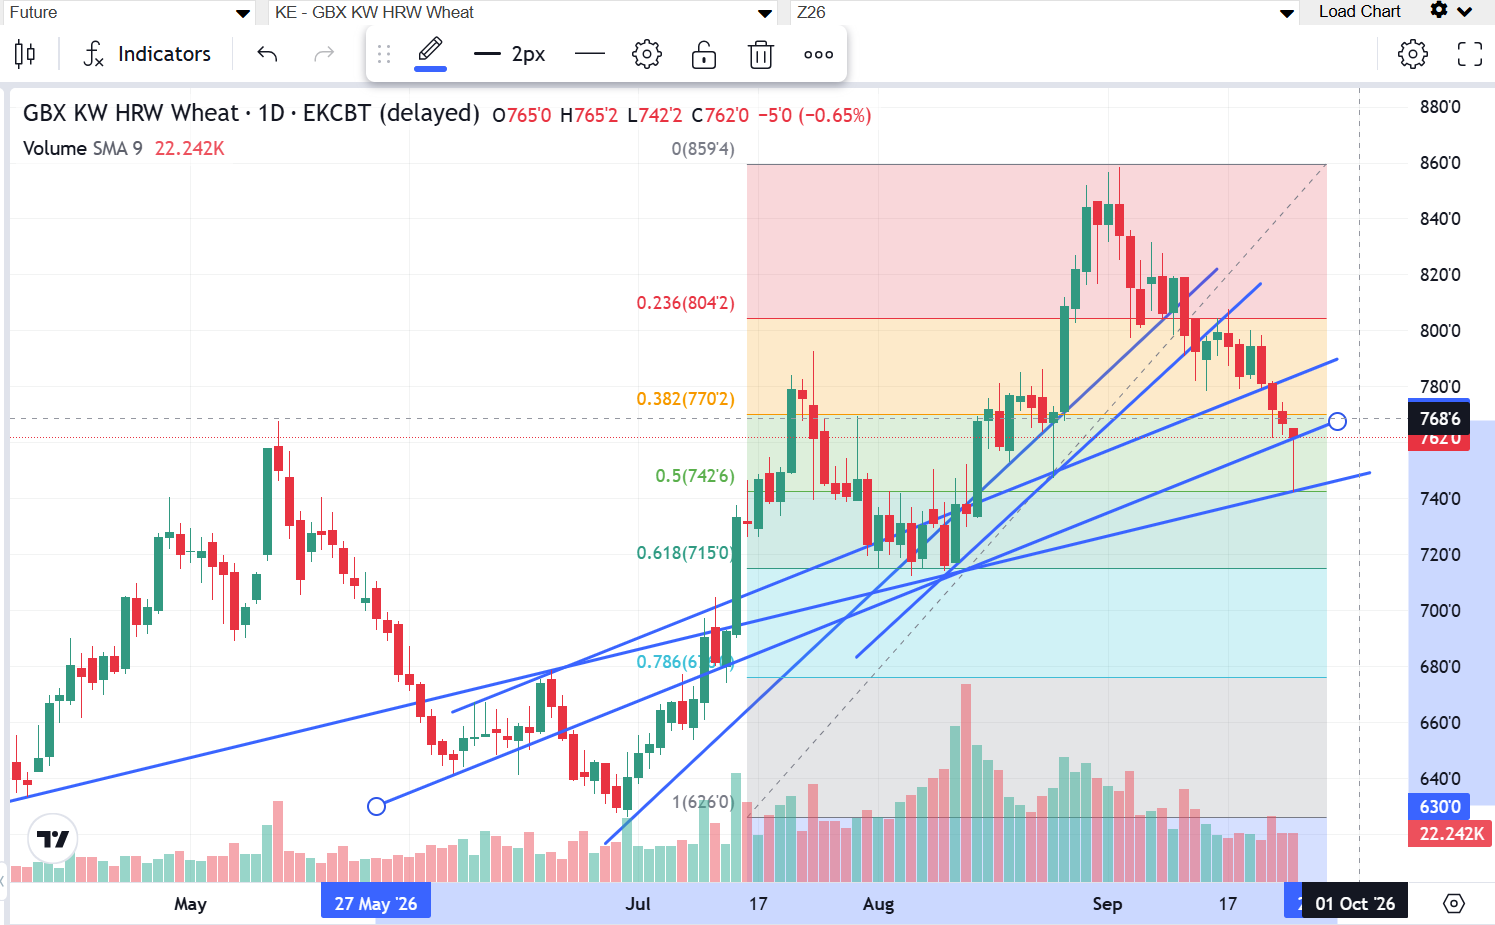
The Kansas City wheat market traded all the way down to the 50 percent Fibonacci retracement level only to stage a sharp recovery into the close that was 20 cents off session lows, ending only down 5 cents on the day.
It was an incredibly busy week for global geopolitics with the United Nations meetings taking place in New York at the beginning of the week and the Chinese President’s State Visit to finish the week. With all the diplomatic posturing, there was increased talks of another ceasefire in Iran via Oman as well as between Russia-Ukraine via Turkey, but I would not be surprised to see resumed conflicts starting next week or over the weekend.
Just when the high stakes can’t seem to get higher, they increase yet again. This essentially translates to neither side suffering enough to capitulate as awful as that seems and sounds. The chess match shall continue after a brief week of niceties, but likely limited “progress.”
The political fervor in the US could not be more hyped in these remaining weeks until the mid-term elections with so much on the table for both parties. Just expect anything and everything to be said by politicians in these final weeks and so be sure to read on to the fine print.
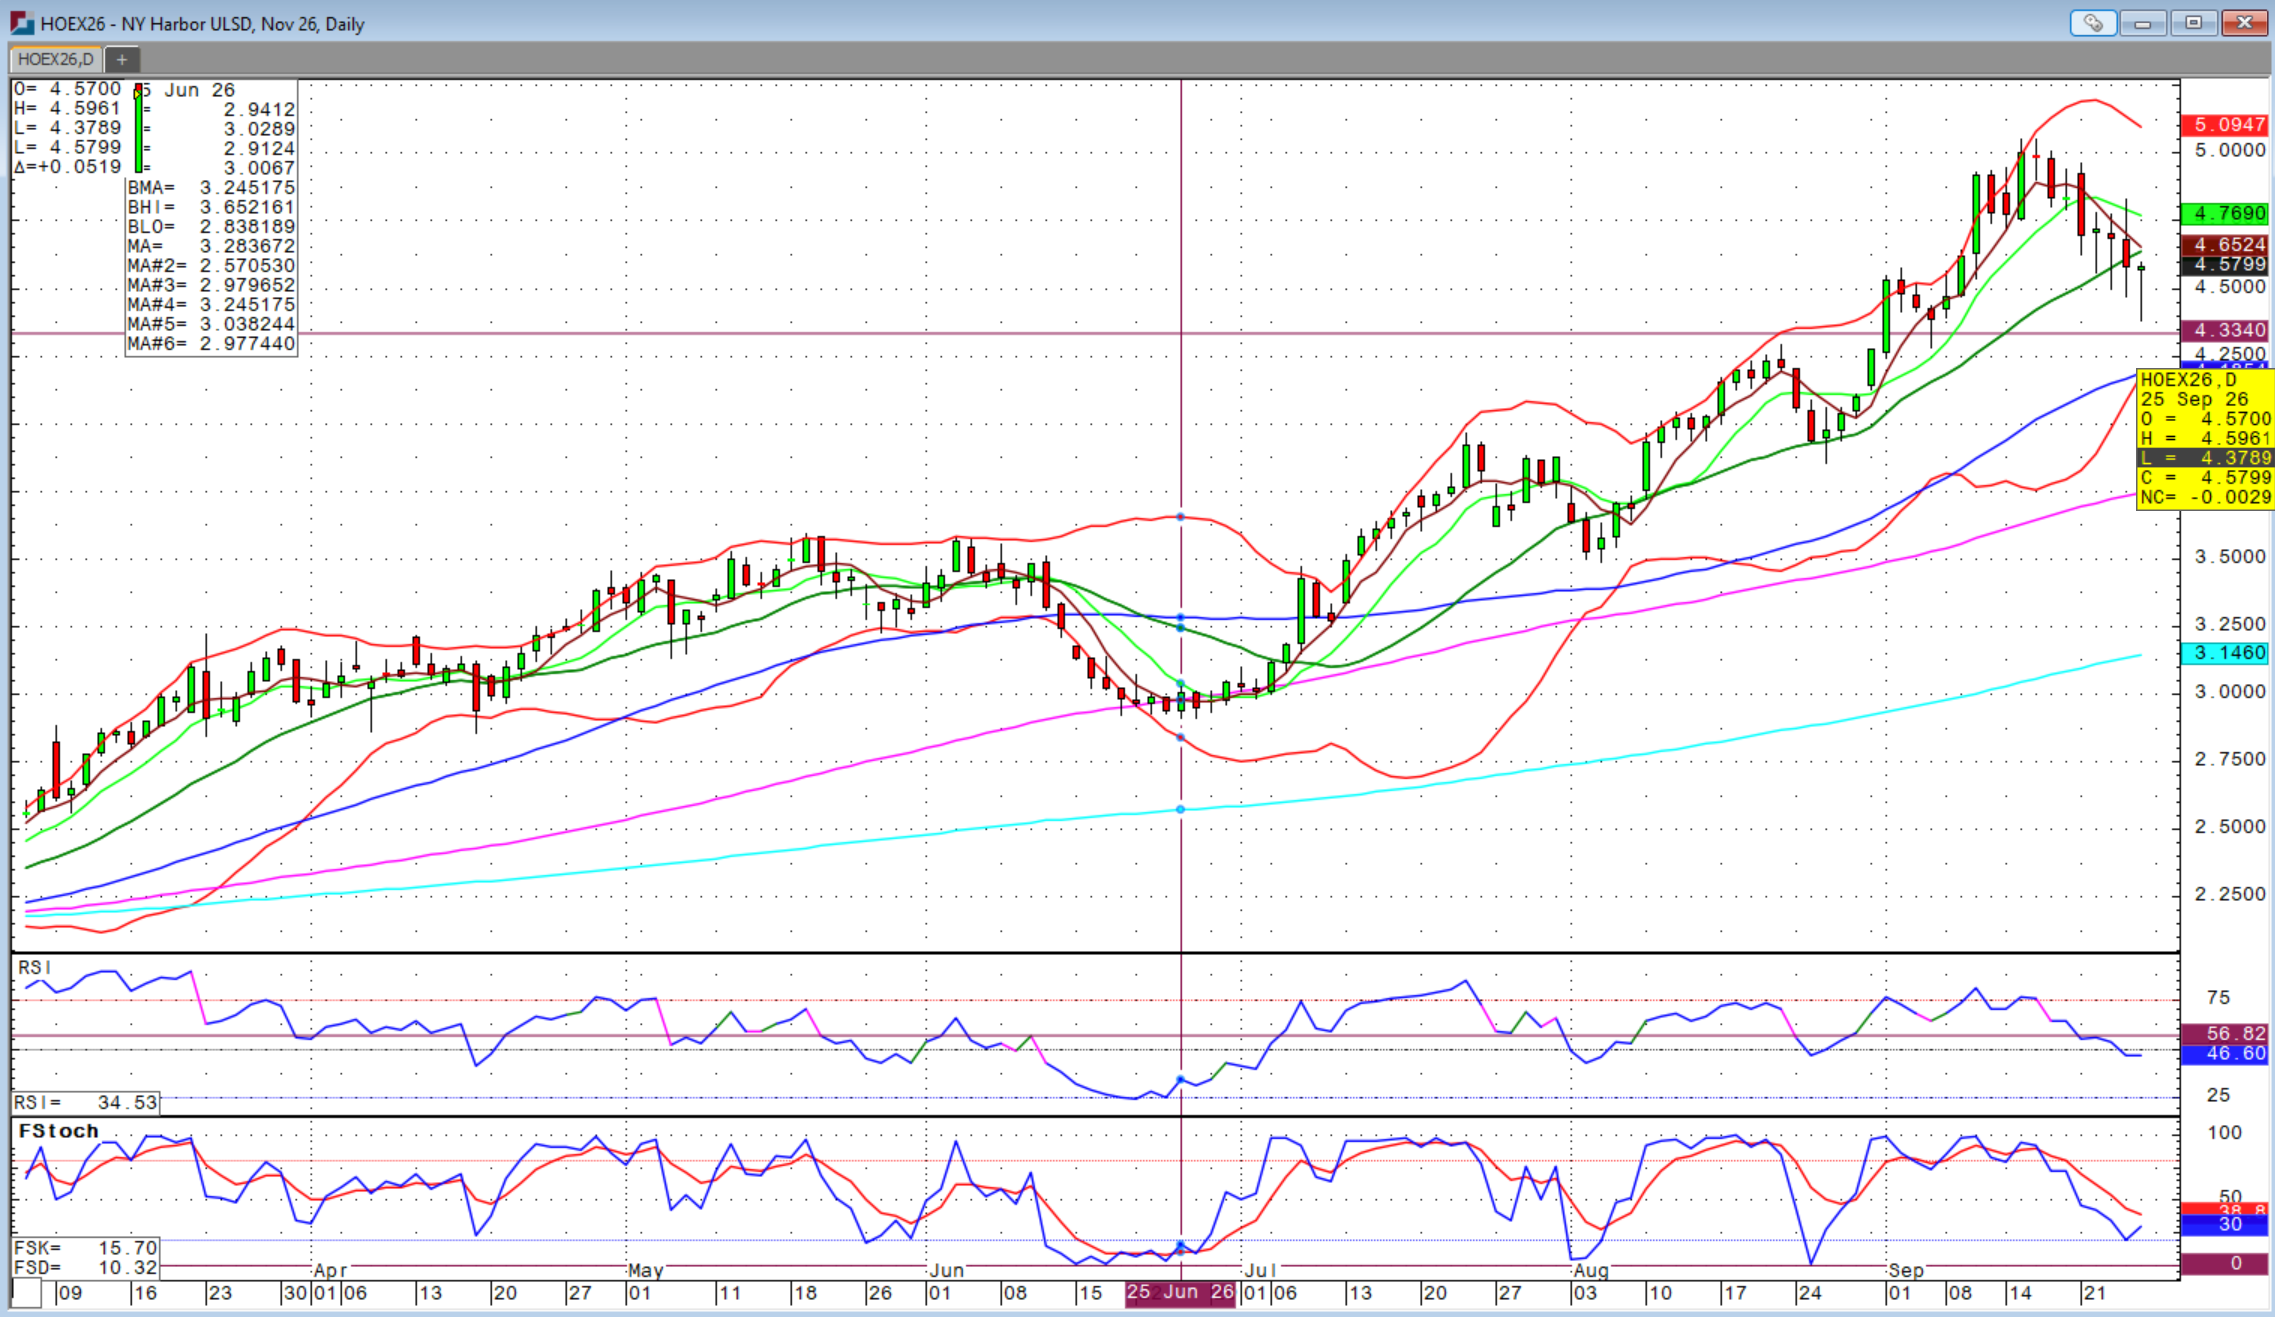
Diesel prices are surging due to higher oil prices, but more so due to Russia’s reduced exports that has talk of a US export ban seemingly imminent. Lobby as far as you can for this not to happen. While it is not only anti-free market, it will only serve to reduce prices for a very limited of time followed by the largest surge in prices that the market has ever seen.
Government interference in markets is always a bad idea, but they sometimes get away with it, but involvement in the fuel markets will be detrimental and only serve to increase inflation and the case for higher interest rates that will squeeze the economy into the unknown. I have witnessed this policy decision up close and personal while in Asia and it is not a solution for economies of Free Enterprise.
With higher input prices, there is need for higher output prices and that is where we should focus. Strengthening our export markets and creating more outlets for domestic value-added manufacturing is where we should all focus. Demand is the best way to fix a supply problem.
Speaking of, the cattle market has finally regained sanity in the structural supply and demand imbalance. The recovery of the cattle complex that began on August 26th has added nearly $30 per cwt back to the feeder cattle contract despite plenty of volatility in between. Bottomline, there are not enough cattle to meet demand regardless of US-Mexico border crossings reopening and Trump’s announcement of reduced restrictions on ground beef imports.
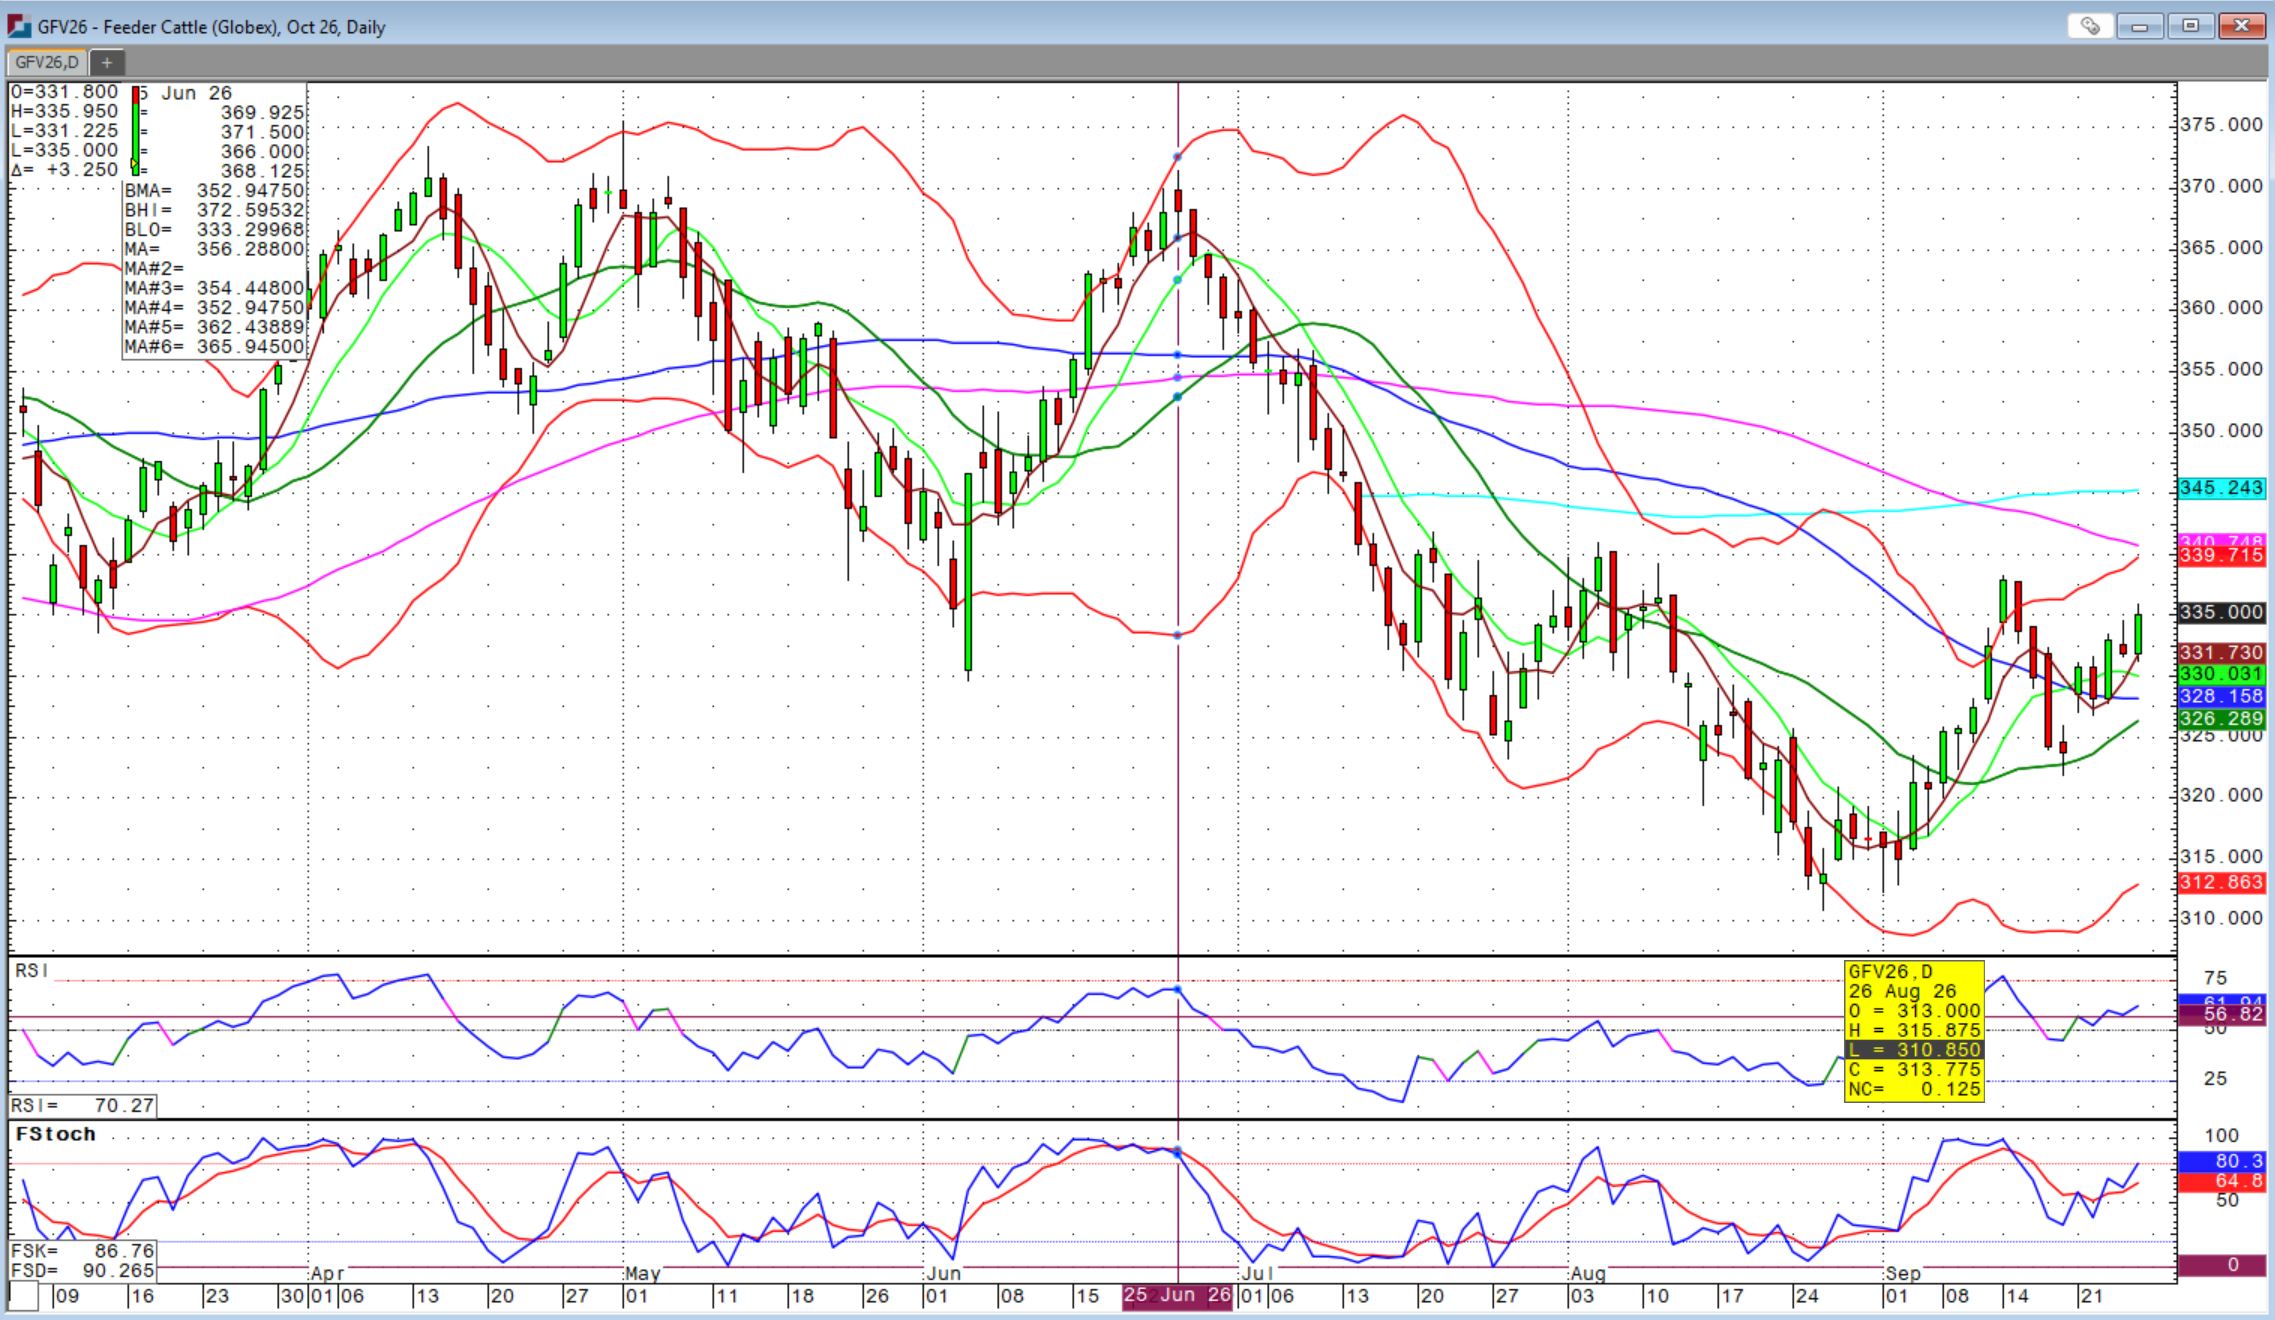
The political backlash from the ‘secret’ ground beef import deal from cattlemen and associations across the country has finally reached President Trump’s attention with talk that the deal may unwind, somewhat. That alone will add bullishness to the market after last week’s already much lower placement number in USDA’s September Cattle-on-Feed report bought buyers back to the table. I also heard that all of these efforts to reduce beef prices has only resulted in a $0.16 per pound decrease, which is irrelevant.
We are in a structural cycle of supply and demand imbalance, and I hope the government can stay out of the way to allow the market to incentivize rebuilding the herd and strengthen the bottom line of cattlemen. That’s the American way and what we need to see for our ranch families and communities even with some additional imports of lean trimmings.
September feeder futures contracts cash settled on Thursday at $337.500. October feeder futures are now the front-month and still trading at a discount to that level, even after Friday’s $3.00+ rally to close the week at $335.000. I believe we could see another $5-10 per cwt of upside in the feeder cattle complex.
December Live cattle futures put in an outside reversal higher day on Friday's chart with a higher high, lower low and higher close versus prior session action. Let's see how this trades out on Monday.
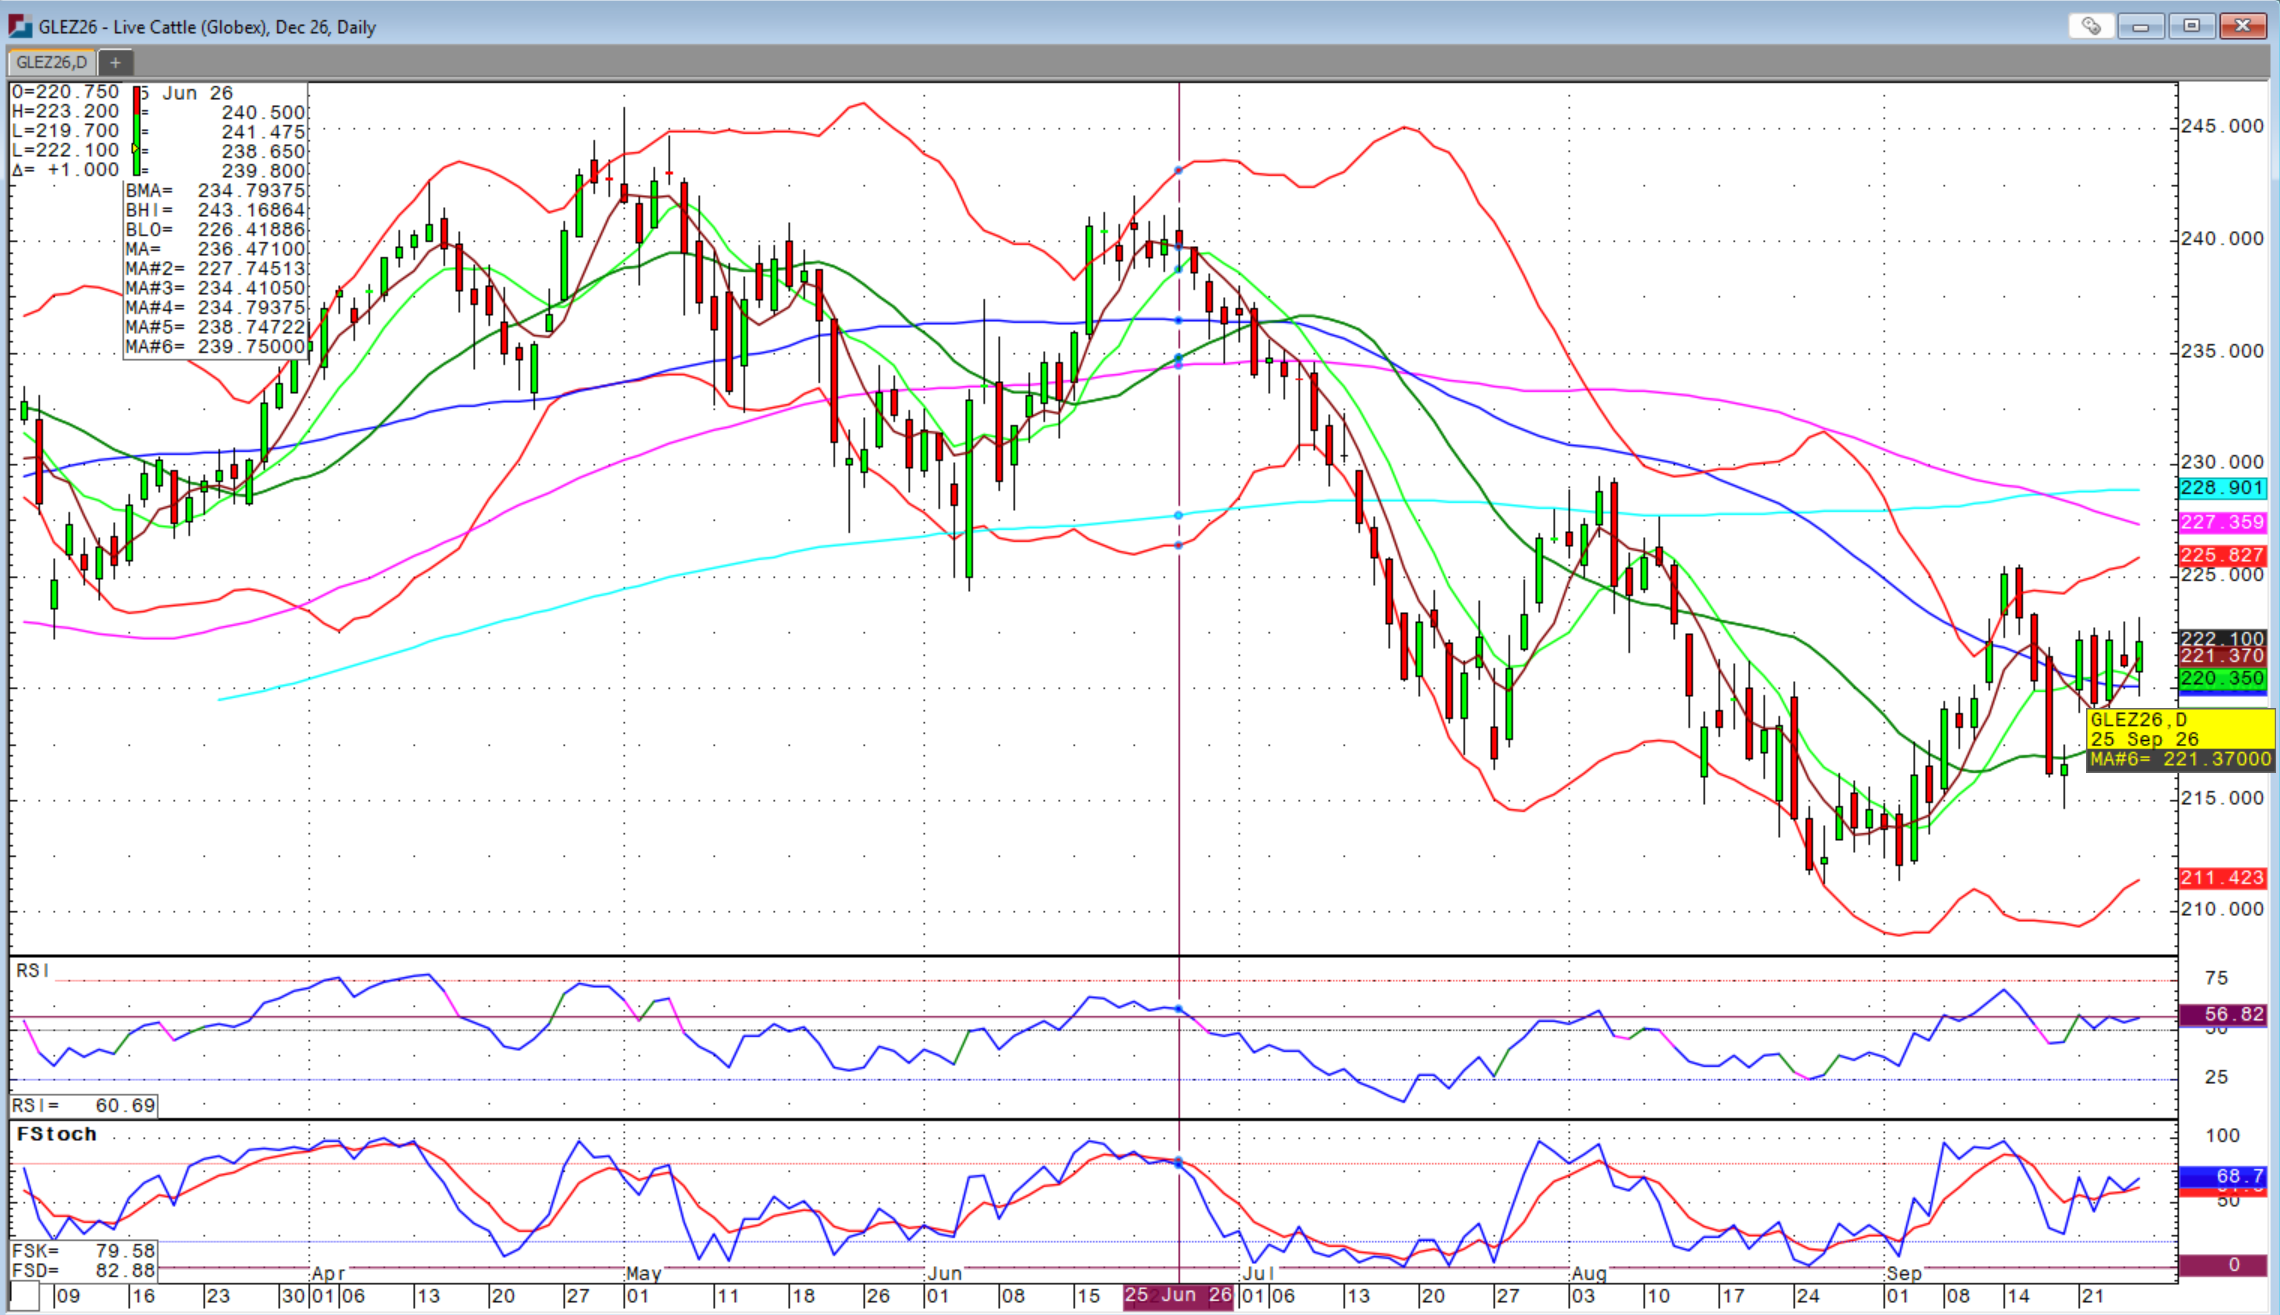
The China trade announcements on Monday will set the tone for the grain markets. If China does in fact purchase US corn as has been widely expected, we could see some headwind for cattle until we see higher cash trade develop.
The ICE raids on cattle facilities in Oklahoma, Kansas and Texas have only tightened the supply situation in the near term, but it is hard to see this alone impacting cash cattle prices much for an extended period.
Sidwell Strategies is the one-stop shop to protect cattle with futures, puts, LRP or a combination of all, which is probably the best strategy overall. If you’re ready to trade commodity markets, give me a call at (580) 232-2272 or stop by my office to get your account set up and discuss risk management and marketing solutions to pursue your objectives. Self-trading accounts are also available. It is never too late to start and there is no operation too small to get a risk management and marketing plan in place.
Wishing everyone a successful trading week! Let us know if you'd like to join our daily market price and commentary text messages to stay informed!
Brady Sidwell is a Series 3 Licensed Commodity Futures Broker and Principal of Sidwell Strategies. Open your Trading Account with Sidwell Strategies at https://portal.stonex.com/prefill/index/BradySidwellU52F112P. Contact us at (580) 232-2272 or at trade@sidwellstrategies.com.
Futures and Options trading involves the risk of loss and may not be suitable for all investors. Review full disclaimer at https://www.sidwellstrategies.com/fccp-disclaimer-21951.