
Dividend Hike Could Be A Game Changer For East West Bancorp (EWBC)
- East West Bancorp lifted its quarterly dividend by 33% this year after reporting strong profitability metrics, including a 1.75% return on average assets and a 16.88% return on average tangible common equity in the second quarter.
- The bank’s low payout ratio and solid capital position indicate that management is prioritizing sustainable shareholder distributions while still funding growth in its U.S. and Asia focused commercial and consumer franchises.
- Investors can now evaluate how East West Bancorp's higher dividend and recent returns may influence the bank's longer term investment narrative.
Compare East West Bancorp's dividend and return profile with a hand picked group of resilient income ideas in our 8 dividend fortresses.
East West Bancorp Investment Narrative Recap
For an investor to stay with East West Bancorp, the key belief is that its U.S. and Asia focused commercial and consumer banking engine keeps generating solid net interest income and healthy returns without stretching the balance sheet. The short term swing factor is how net interest margin holds up as funding costs react to competition for deposits and certificates of deposit.
The biggest risk right now is deposit pricing pressure and any hit to net interest income if East West Bancorp must keep rolling roughly US$13b of CDs at relatively high rates. Credit quality and fee income already show some sensitivity, so a sharp rise in provisions or a weak quarter for fees could quickly dilute returns.
The 33% dividend increase is the recent move that matters most for this story. It sits on top of a 1.75% return on average assets and 16.88% return on average tangible common equity, which signals that current profitability is supporting higher cash returns while the bank maintains what is described as a strong capital position.
For catalysts, that higher dividend interacts directly with the funding and growth debates. If East West Bancorp can keep growing loans in its cross border and California centric franchises while holding a low payout ratio and defending margins against CD repricing, the stock’s appeal will hinge on how investors weigh that income stream against the ongoing risks around deposit costs and future credit losses.
What The Current Forecasts Assume For East West Bancorp
Analysts framing East West Bancorp's outlook are working off a set of fairly specific numbers. The revenue line is assumed to grow by 10.3% a year over the next three years, while profit margins are expected to move from 50.1% today to 42.6% in that same period. On the earnings side, the consensus view looks for net income to reach US$1.7b by around 2029, compared with US$1.4b today, which points to an earnings increase of roughly US$300m from current levels.
Those estimates also bake in a modest decline in the share count, with the number of shares on issue expected to fall by about 0.42% a year for the next three years. For that earnings path to line up with current analyst targets, East West Bancorp would need to trade on a P/E of 15.1x its projected 2029 earnings, versus 11.9x today and above the 11.7x currently quoted for the broader US banks group.
East West Bancorp's narrative projects US$3.9b revenue and US$1.7b earnings by 2029. This requires 10.3% yearly revenue growth and an earnings increase of about US$300m from US$1.4b today.
Discover why East West Bancorp's fair value indicates an 18% potential upside to its current price that may not last much longer.
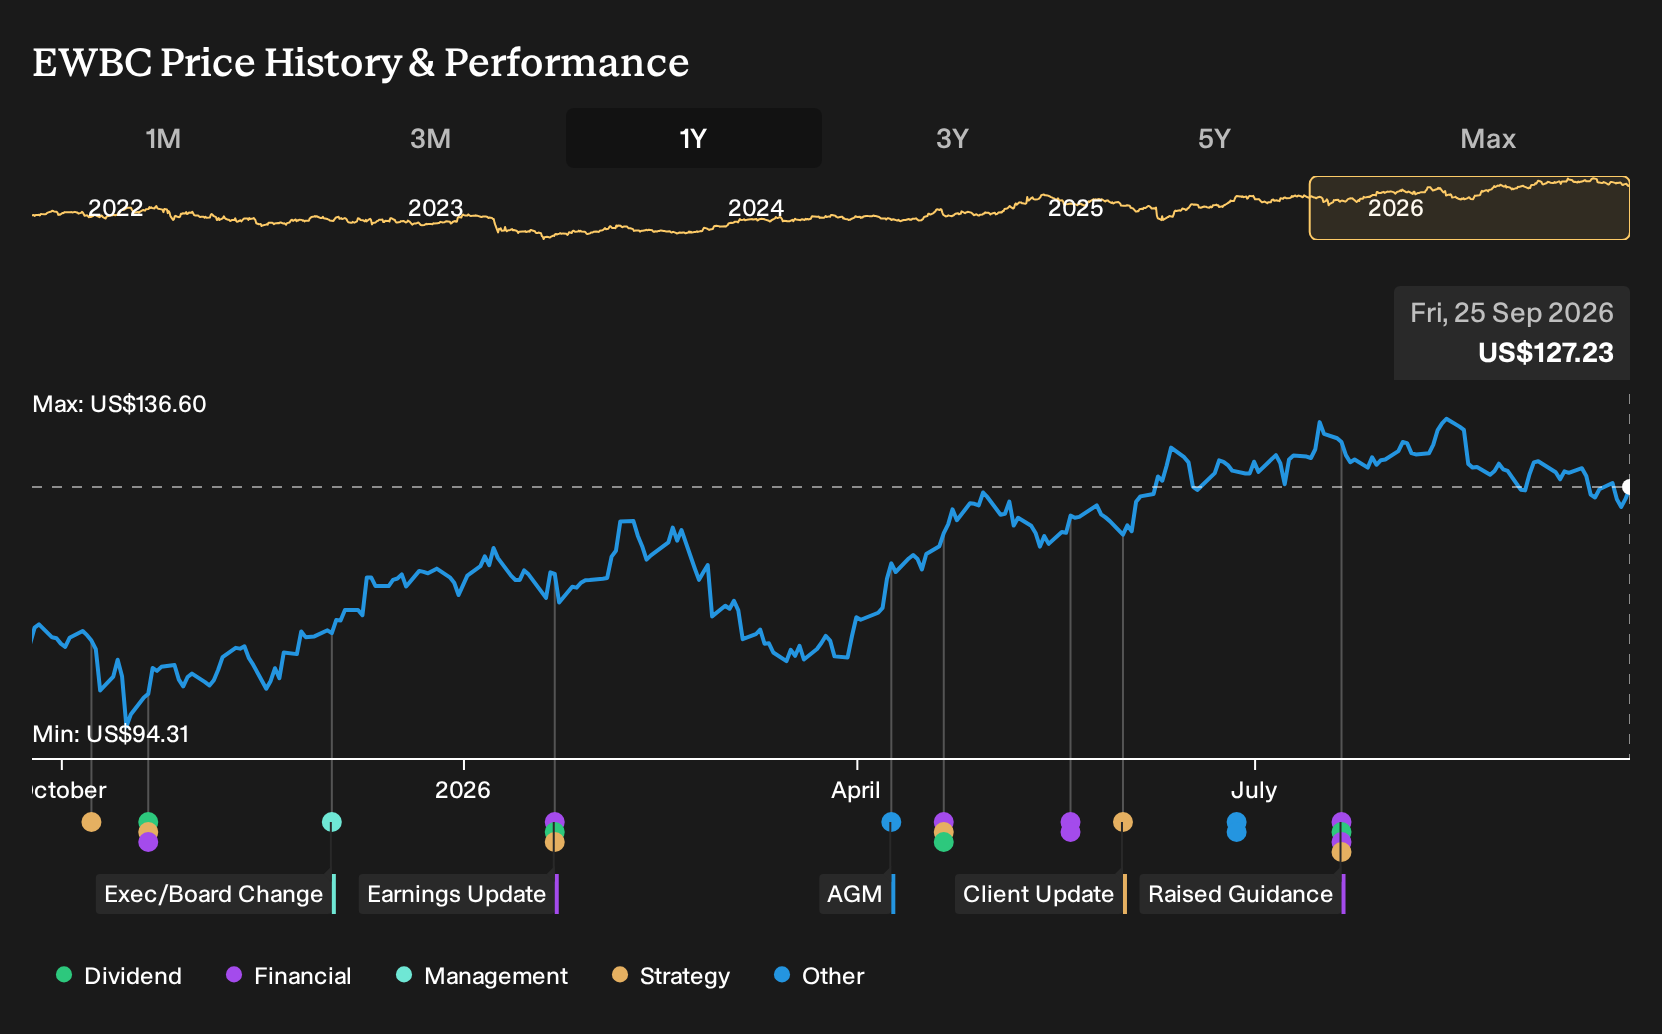
Exploring Other Perspectives
Fair value estimates for East West Bancorp from the Simply Wall St Community currently range from roughly US$150 to about US$258 per share across 2 separate views, a wide spread for a single bank. You are seeing retail investors weighing dividend growth and capital strength against risks from deposit pricing and potential net interest income deceleration.
Explore another East West Bancorp fair value estimate, including one that suggests it could be worth just $150.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your East West Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for East West Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate East West Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond East West Bancorp?
If you want to stress test what you think about East West Bancorp, it can help to line it up against other stocks with different income, quality, and risk profiles using the Simply Wall St Screener.
- For investors who want income without ignoring balance sheet strength, start with a 8 dividend fortresses that aims to pair higher yields with robust fundamentals.
- If capital preservation is your first filter, consider a 30 resilient stocks with low risk scores that focuses on resilient businesses with lower risk scores.
- When you are hunting for future watchlist candidates, scan a 16 high quality undiscovered gems that combines solid financials with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com