
Cronos Group Stock And 2 Canadian Penny Stocks To Watch
Global markets are adjusting to higher long term borrowing costs as government bond yields hover near multi decade highs. That type of backdrop often puts pressure on heavily indebted businesses and shines a light on balance sheets that look cleaner. For investors hunting Canadian low priced stocks with relatively healthier finances, this can be a useful moment. This article walks through 3 financially resilient penny stocks picked from that group.
The three stocks below are a small sample, drawn from a much bigger pool of financially solid penny shares. The wider screen surfaced 345 more companies with similarly robust stories that are not covered here. To see that full list and quickly sort, compare, and analyze potential ideas, head straight to the Financially Fit Penny Stocks screener.
Cronos Group (TSX:CRON)
Cronos Group is a cannabinoid-focused business built around branded consumer cannabis products such as Spinach, Lord Jones, Lit and Peace Naturals, with all of its roughly $179 million in revenue coming from cultivation, manufacturing and marketing of cannabis and derived products and a market cap of about $1.75b.
Cronos Group fits the Financially Fit Penny Stocks theme through its branded cannabis portfolio and a balance sheet that gives it room to fund growth without stretching risk too far. This is exactly where the next quote starts to matter for investors watching the sector.
"Expanded access to high-growth international medical cannabis markets, such as Israel, Germany, and Switzerland, positions Cronos to benefit from ongoing regulatory reforms and rising global acceptance of cannabinoid-based wellness products, boosting both top-line revenue and long-term market diversification."
The real swing factor is how one pressure on future profitability resolves once today’s expansion spending meets tomorrow’s pricing and demand reality.
That pressure point is exactly what the full narrative for Cronos Group unpacks in detail, showing where Cronos Group’s expansion spending could be masking a stronger long term opportunity.

Omai Gold Mines (TSXV:OMG)
Omai Gold Mines is a Toronto based explorer focused on acquiring, evaluating and developing gold deposits in Guyana, anchored by 100% ownership of the 4,590 acre Omai prospecting license, with a market cap of about CA$1.71b.
For investors using the Financially Fit Penny Stocks lens, Omai Gold Mines offers focused exposure to a single gold project with early stage economics, including a PEA outlining large scale production potential. At the same time, the company carries the funding strain and share dilution risk that comes with a short cash runway and no meaningful current income, raising the question of how shareholder returns could be affected if that funding gap widens before the next milestone.
If that funding gap is what you are weighing, the 1 key reward and 5 important warning signs (3 are major!) shows how Omai Gold Mines’ upside story compares with its dilution risk.

McChip Resources (TSXV:MCS)
McChip Resources is a Toronto based resource investor focused on petroleum interests and mineral exposure tied to its Saskatchewan potash project, placing it squarely in the Financially Fit Penny Stocks theme. It generated about CA$3.6 million from oil and gas exploration and production in Canada and has a market cap of roughly CA$4 million.
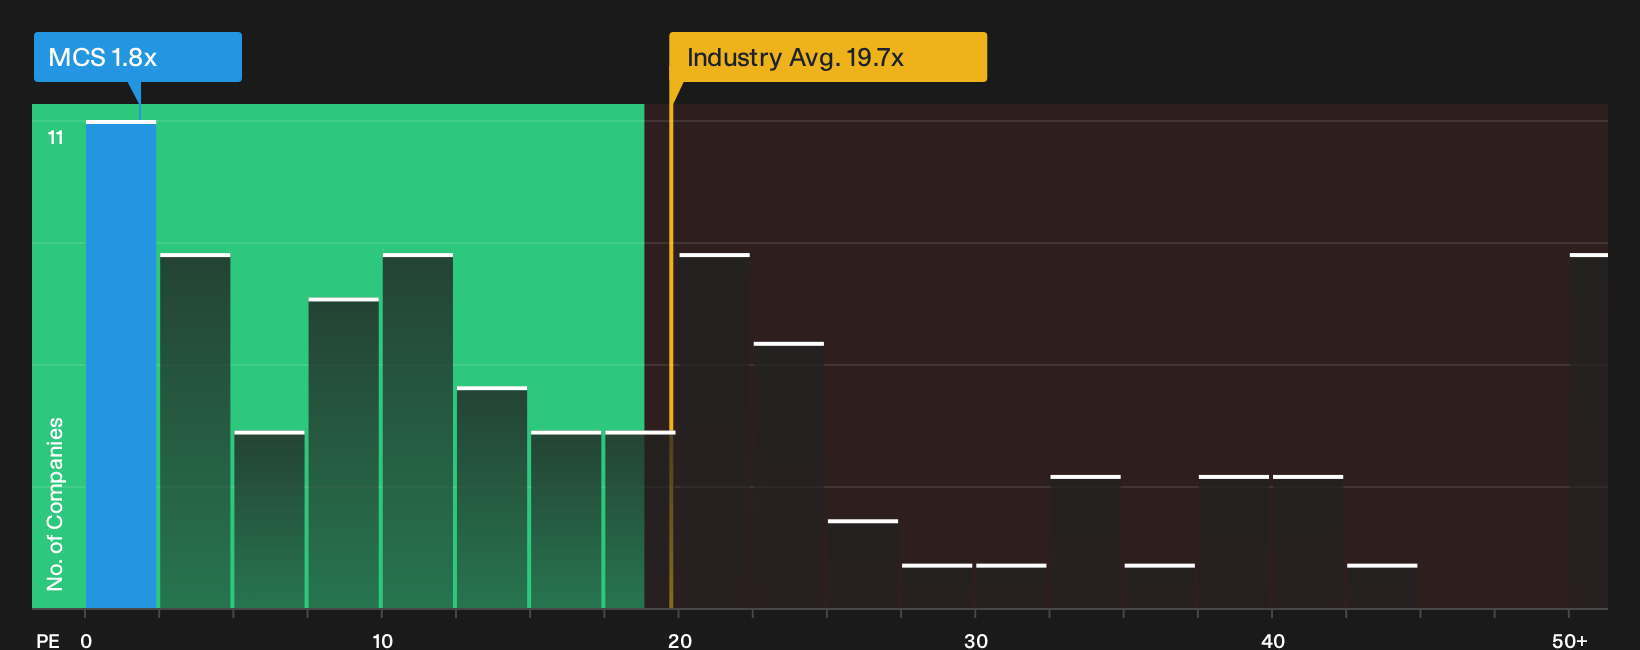
For a low priced resource play, McChip Resources combines exposure to petroleum and potash assets with earnings growth of 80.9% and a P/E of 1.8x, while also reporting losses and fragile cash flows recently. The balance between strong margins and that funding strain depends on how one pressure on future returns is resolved.
That tipping point on future returns is exactly what the 2 key rewards and 3 important warning signs unpacks, showing where McChip Resources’ valuation could be decoupling from its earnings power.
Seeking Fresh Alternatives With Real Momentum
Fresh ideas do not stay under the radar for long. When momentum builds, entries get crowded and pricing moves fast. Scan these curated shortlists before the crowd and consider acting promptly.
- Catch early movers in resilient sectors by screening for 8 resilient stocks with low risk scores, which are designed to hold up when volatility picks up and sentiment starts dropping.
- Target potential income workhorses using the 1 dividend fortresses and focus on businesses where higher payouts are supported by balance sheets built to handle pressure.
- Track emerging themes in resource demand with the 17 top copper producer stocks and follow producers positioned to respond if long term infrastructure spending continues to build momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com