
Is Westlake (WLK) Undervalued After Expanding Its BlueLinx Partnership?
Westlake (WLK) is back in focus after Westlake Royal Building Products expanded its partnership with distributor BlueLinx, making Westlake the exclusive PVC trim supplier and widening access to Kleer and TruExterior lines across key U.S. markets.
Recent trading tells a mixed story for Westlake. The 1-day share price return of 1.42% sits against a 30-day share price decline of 9.25%, while the 3-year total shareholder return is down 42.17%. This suggests momentum has been fading despite the BlueLinx distribution expansion headline.
Scan beyond Westlake and compare this distribution-driven story with a curated set of building and materials players by checking our list of solid balance sheet and fundamentals (24 results).
Westlake’s shares have slid over the past year even as reported annual revenue and net income growth turned positive. Is that a signal about the underlying business, or mainly a reset in sentiment that the valuation now reflects?
Most Popular Narrative: 28% Undervalued
On the most followed narrative, Westlake screens as undervalued, with a fair value of $93.73 against the recent $67.71 close. This puts the focus squarely on how its end markets and cost base evolve from here.
The multi-year increase in municipal infrastructure spending in the U.S., fueled by the Infrastructure Act and ongoing underspend in water infrastructure, is structurally supporting long-term demand for Westlake's HIP (Housing and Infrastructure Products) segment, particularly for PVC pipes and fittings. This is creating a reliable revenue and volume growth driver unaffected by near-term housing volatility.
See why 9 investors see Westlake as 28% undervalued.
Result: Fair Value of $93.73 (UNDERVALUED)
Still, the narrative can crack if global chemical oversupply keeps pressure on Westlake’s Performance and Essential Materials pricing or if higher North American energy costs persist.
Find out about the key risks to this Westlake narrative.
Another View On Westlake’s Value
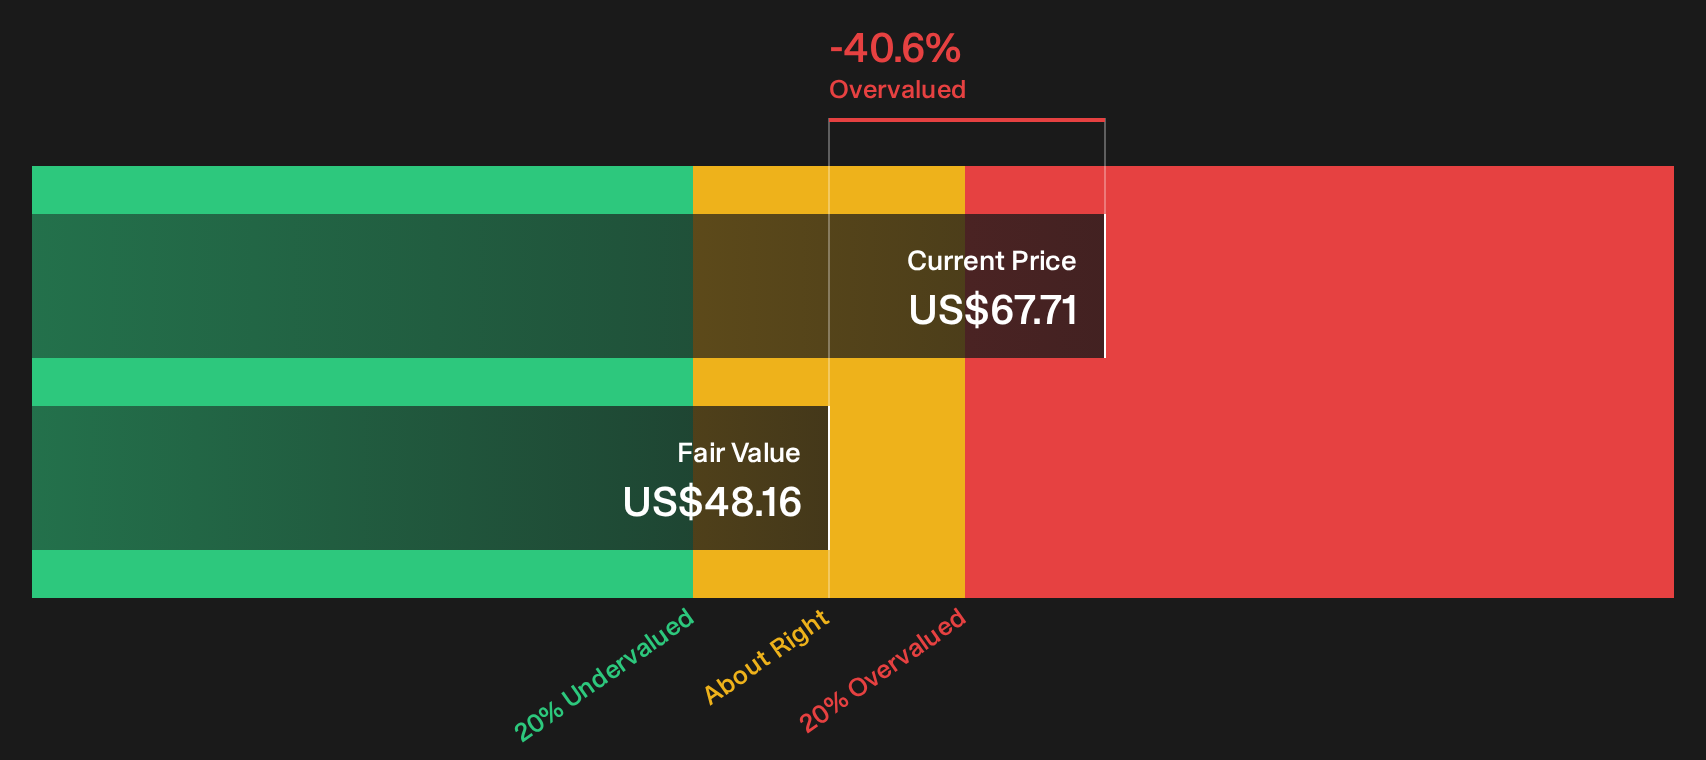
There is a second lens on Westlake that pushes against the 28% undervalued story. The SWS DCF model, which values the business on projected future cash flows, points to a fair value of $48.16. That sits below the recent $67.71 share price, so on this measure the stock screens as overvalued.
The gap between a $93.73 fair value from the narrative and $48.16 from our DCF model is wide enough to make any investor pause. It raises a simple question: Which set of assumptions about future cash generation do you trust more, and what does that mean for the margin of safety you really have here?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westlake for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Westlake can pull you in both directions, so move quickly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Westlake?
If Westlake has sharpened your focus on valuation and risk, do not stop here. Use the screener to surface fresh ideas that fit your style.
- Target potential mispricing and shortlist companies that combine quality fundamentals with attractive valuations through our 32 high quality undervalued stocks.
- Build a more resilient portfolio by filtering for businesses with robust financial footing using the 30 resilient stocks with low risk scores.
- Spot future candidates early by scanning financially solid yet less-followed opportunities via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com