
How Investors May Respond To Future (TSE:4722) After Index Removal
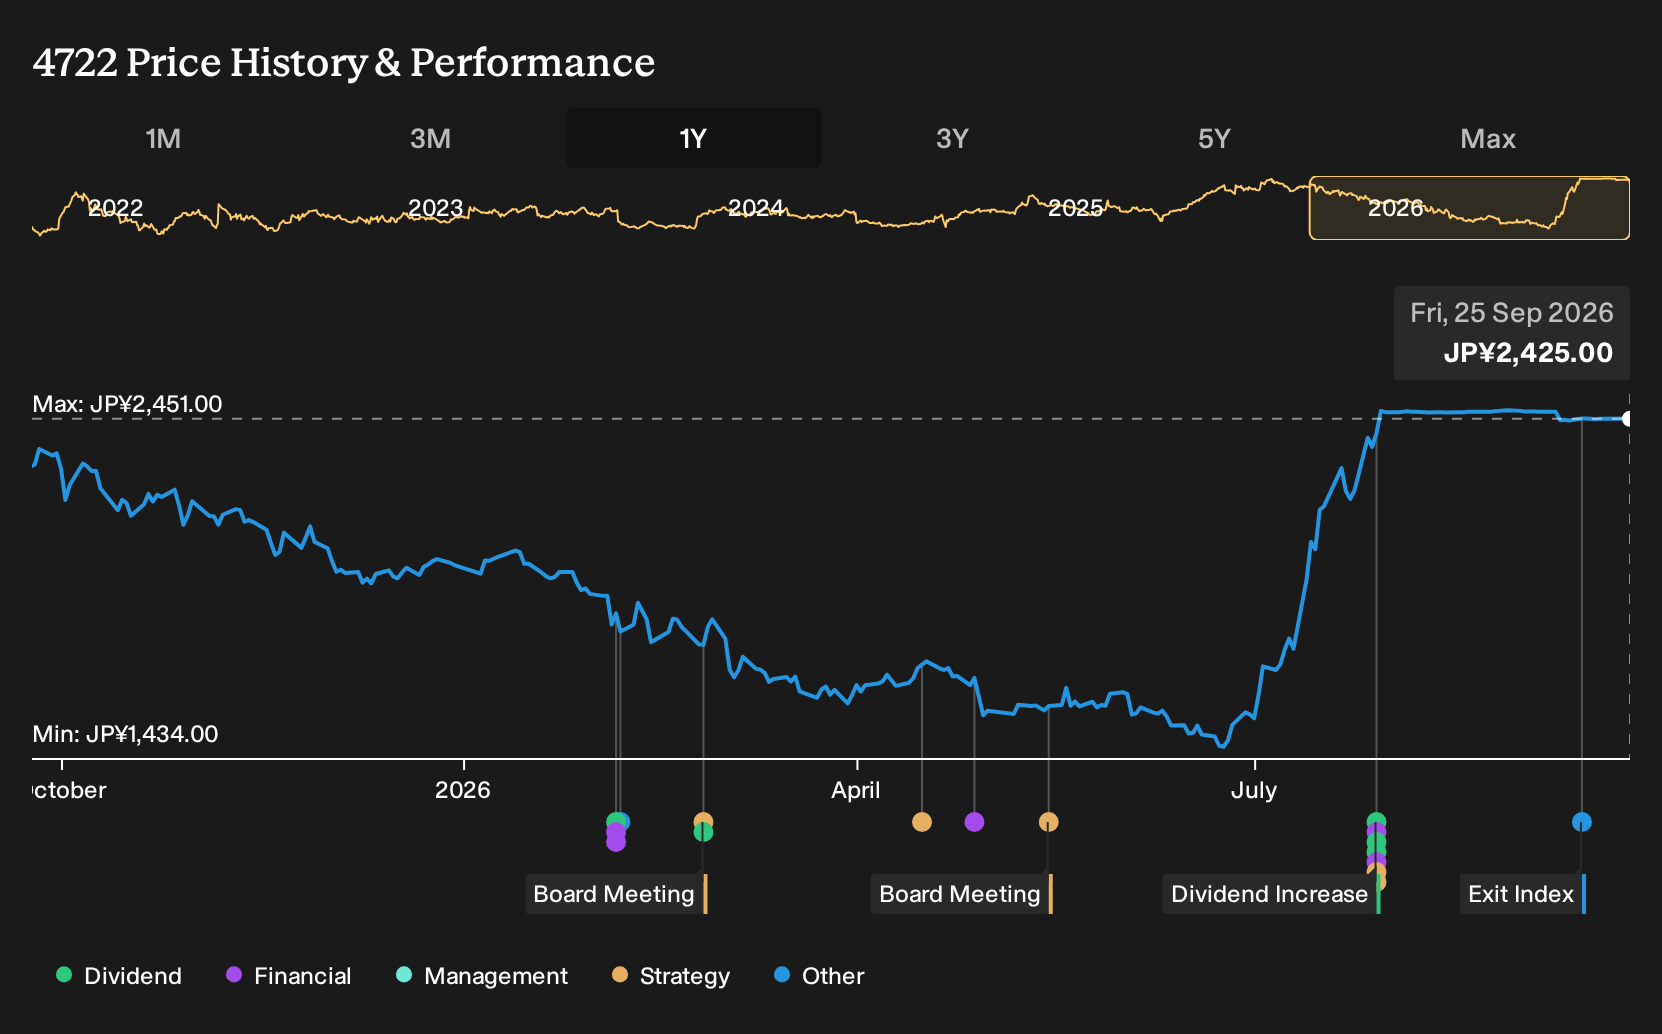
- Future Corporation held a board meeting on 24 September 2026 to consider setting a record date for an extraordinary shareholders' meeting, following its recent removal from the S&P Global BMI Index.
- The index exit could reshape who holds Future Corporation shares, as passive and index-linked investors reassess exposure while active holders weigh the governance steps signaled by the planned extraordinary meeting.
- We will look at how Future Corporation's investment narrative is affected by the index removal and the planned extraordinary shareholder meeting.
Scan opportunities that could benefit as index reshuffles prompt investors to reassess positions. Start with our hand picked 74 high quality undiscovered gems alongside Future.
What Is Future's Investment Narrative?
To own Future, you need to buy into a consulting and IT services story where consistent execution matters more than index membership. The group earns most of its ¥78,670 revenue base from IT consulting and services in Japan, with business innovation as a smaller add on. That kind of work depends on winning projects, delivering on time and keeping utilisation high, not on whether it sits inside the S&P Global BMI Index.
The index removal and the board meeting on 24 September 2026, focused on setting a record date for an extraordinary shareholders' meeting, mainly influence who holds the stock and how governance might evolve. Core drivers still look rooted in earnings quality, mid single digit to low double digit type growth expectations and relatively modest capital intensity. The bigger watchpoints sit around valuation at a 17.5x P/E, forecast growth that is solid but not explosive, and a balance sheet funded entirely by higher risk sources.
Yet there is a less obvious pressure point that could matter far more for Future if conditions change...
There's only one way to know the right time to buy, sell or hold Future. Head to Simply Wall St's company report for the latest analysis of Future's Fair Value.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between ¥2,466.67 and ¥2,588.87, so you are looking at a very narrow band of opinions on Future Corporation. That snapshot predates both the index exit and the planned extraordinary meeting, which could reshape how you and other holders think about risk, governance and long term performance.
Explore another Future fair value estimate, including one that suggests up to 7% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Future research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Future. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Future's overall financial health at a glance.
Looking For More Ideas Beyond Future?
If the Future Corporation story has you reassessing where you want your capital working, it can help to line it up against a wider set of candidates that match your risk and income preferences.
- For investors who care most about durable cash flows and balance sheet strength, start with a list of solid balance sheet and fundamentals (22 results) that can sit alongside Future in a more resilient core portfolio.
- If your priority is limiting downside while staying invested in equities, compare Future with a 21 resilient stocks with low risk scores that may better match your tolerance for drawdowns.
- For those hunting for mispriced opportunities with quality foundations, broaden your watchlist with a 18 high quality undervalued stocks that could complement or compete with Future in your ideas list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com