
Ryder System (R), What Is Behind The Fresh Attention Now?
Ryder System (R) has drawn renewed attention after recent share price moves left the stock down about 6% over the past month and roughly 10% in the past 3 months. Investors are reassessing the logistics provider’s valuation and return profile.
Recent trading suggests that momentum in Ryder System’s share price is fading in the short term. The 30 day share price return is down 5.6% and the 90 day share price return is down 9.7%, even as the 1 year total shareholder return of 27.7% and 5 year total shareholder return of 219.0% point to a much stronger longer term performance backdrop relative to the latest pullback.
Compare Ryder System’s recent pullback with other transport and logistics stocks that screen well on quality and valuation using our curated list of 32 high quality undervalued stocks.
Ryder System has pulled back after a strong multi year run, yet analyst targets and intrinsic value estimates remain well above the current US$235.57 price. How wide is that gap, and what appears reasonable for fair value at this point?
Most Popular Narrative: 21% Undervalued
Ryder System’s most followed valuation narrative points to a fair value of $298.44, which sits well above the recent $235.57 share price and frames the recent pullback as a gap between price and expectations.
A transformed business model built on high-margin, multi-year contracts and disciplined pricing, combined with significant operating cash flow and a strong balance sheet, provides Ryder with the capital flexibility to fund organic growth, strategic acquisitions, and shareholder returns, creating long-term earnings growth potential.
See why 7 investors see Ryder System as 21% undervalued.
Result: Fair Value of $298.44 (UNDERVALUED)
Still, this fair value story can falter if freight markets stay weak for longer and used vehicle pricing continues to pressure Ryder System’s margins and cash generation.
Find out about the key risks to this Ryder System narrative.
Another View On Ryder System’s Valuation
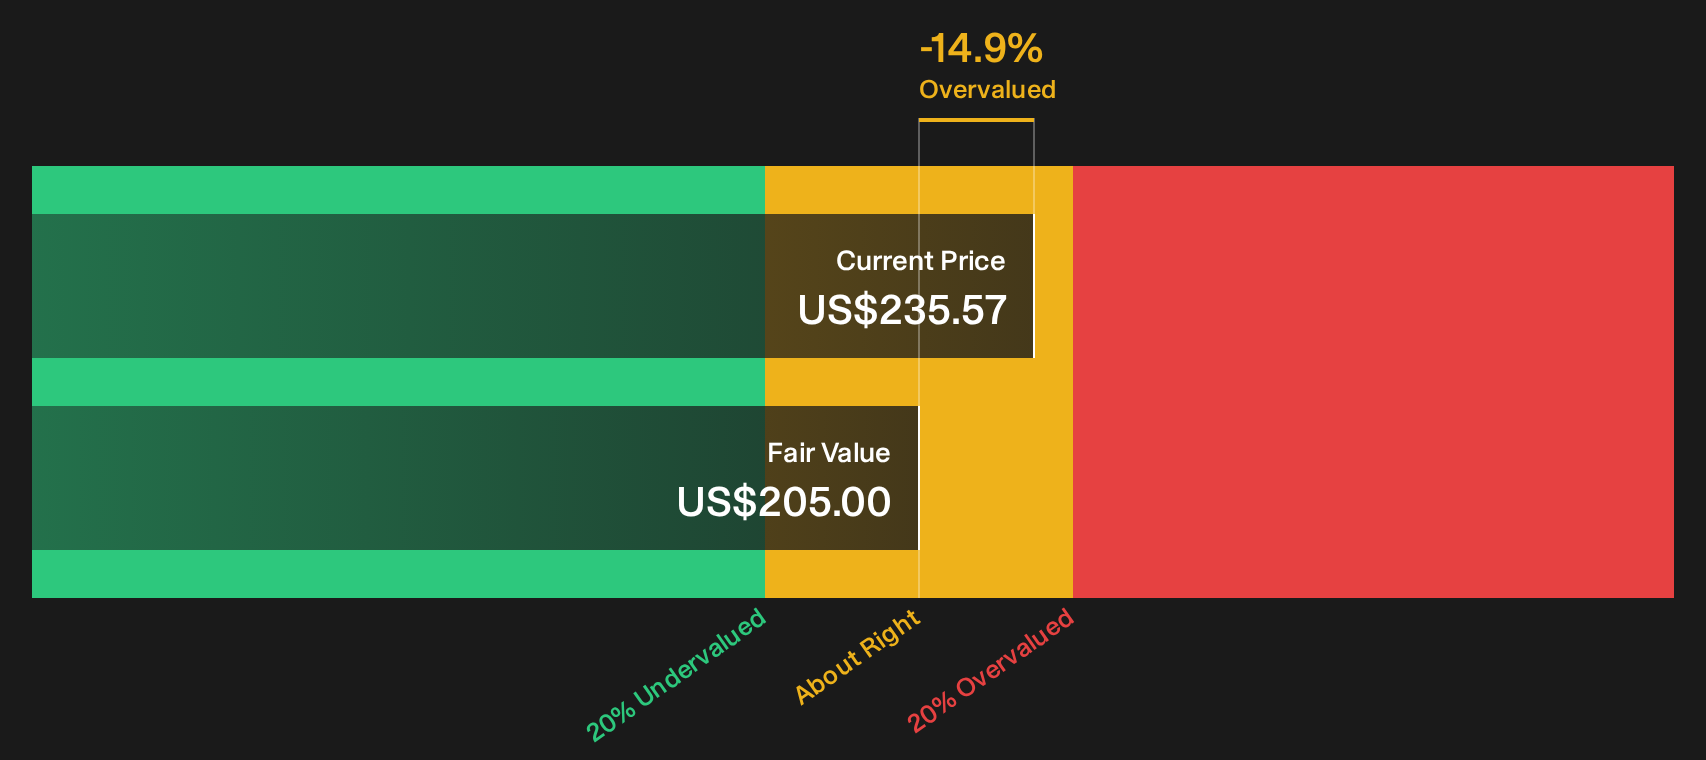
The fair value narrative for Ryder System leans heavily on analyst earnings projections and target prices. A different lens comes from the SWS DCF model, which values the stock at $205, compared with the current $235.57 share price, pointing to a premium rather than a discount.
That DCF result classifies Ryder System as trading above its estimated future cash flow value, so anyone leaning on this framework is looking at less margin for error than the narrative fair value suggests. Which yardstick do you trust more when cash generation and freight conditions are both in focus?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ryder System for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ryder System so far. If you want to move quickly and shape your own view, consider its balance between risks and potential upsides by checking the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ryder System?
If Ryder System has you thinking more broadly about opportunities, do not stop here. Fresh ideas often come from comparing a few very different setups.
- Target potential mispricing by scanning companies that pair solid fundamentals with appealing valuations through our curated list of 32 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on businesses that offer higher yields and robust payout profiles using the 8 dividend fortresses.
- Focus on durability by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you avoid fragile stories and keep your portfolio on stronger footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com