
3 Canadian Undervalued Stocks To Watch In September 2026
US 10 year Treasury yields recently moved above 5%, which lifts borrowing costs far beyond government debt and into mortgages, corporate loans and commercial real estate. Higher discount rates can weigh on market valuations, yet they also expose Canadian companies whose future cash flows still look attractive relative to their share prices. This article highlights three Canadian stocks that screen as undervalued on cash flows today.
The three Canadian stocks covered below are only a small sample of the opportunities that screen as undervalued on cash flows. The full Simply Wall St screen surfaces 1 more company with a similarly interesting cash flow story that is not included here. To identify and analyze the highest conviction ideas from this wider group, go straight to the Undervalued Stocks Based On Cash Flows screener.
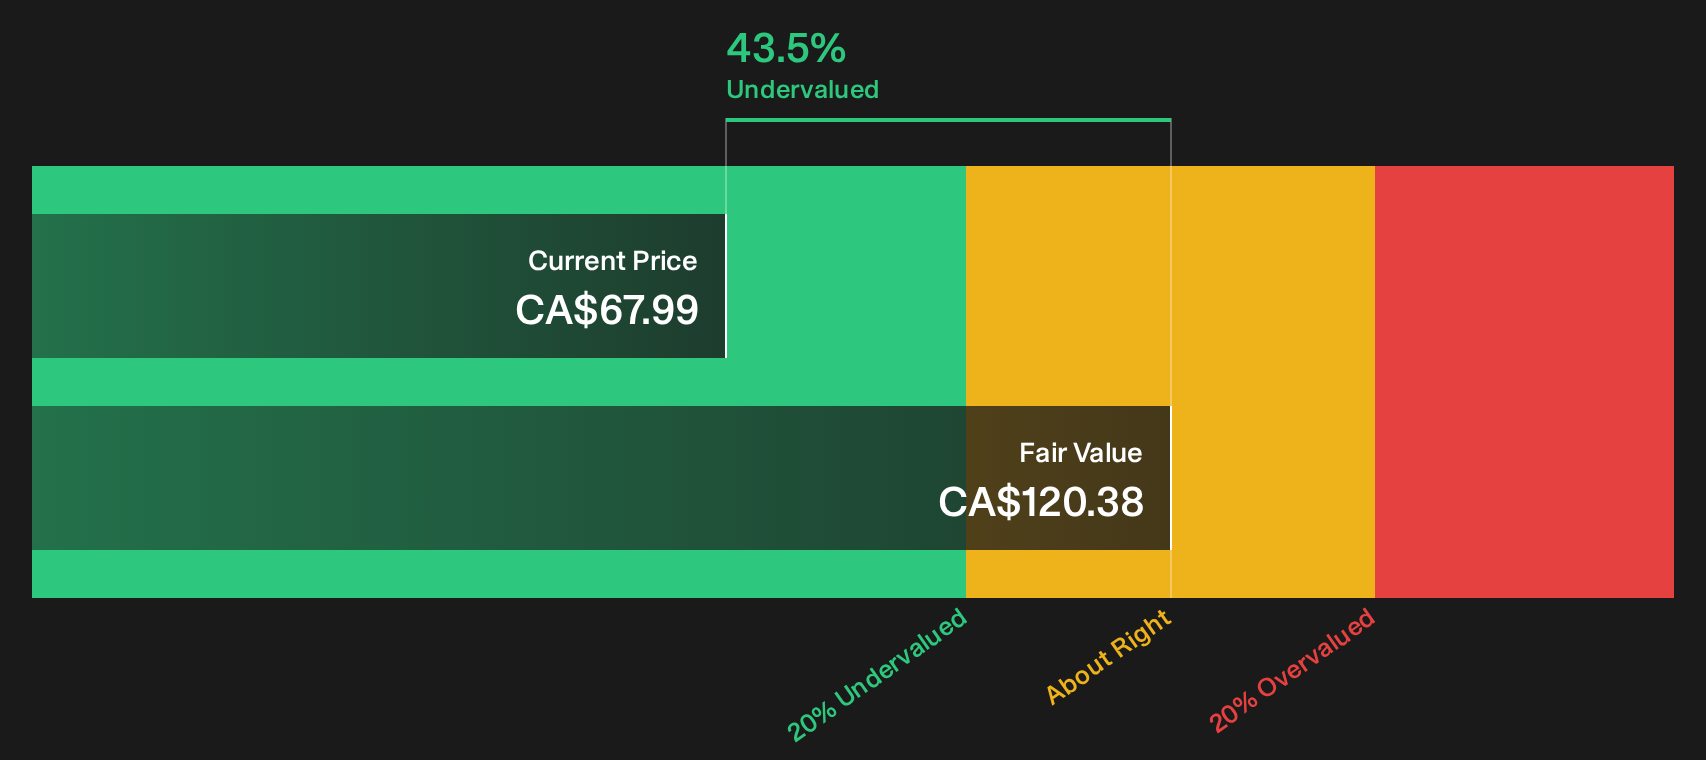
Pan American Silver (TSX:PAAS)
Pan American Silver is a precious metals producer whose silver mines generate the free cash flows that put it firmly in this cash flow undervaluation screen. Most revenue comes from gold rich operations in Brazil, Chile and Peru, alongside key silver sites in Mexico and Argentina, and a market value around CA$28.4b.
For investors focused on cash flow, Pan American Silver offers a mix of established assets and active projects that directly feed into discounted cash flow models. This makes how management improves costs and scale a key part of the story ahead.
"Integration of Juanicipio, with its low cash costs and contribution to attributable silver production and income, refines the cost base and can support higher segment margins and free cash flow generation."
The real swing factor is how one large development decision eventually filters through to unit costs and to the durability of those improving margins.
That cost inflection point is where the story gets interesting, and the full narrative for Pan American Silver explains how capital decisions, jurisdiction mix and silver exposure could reshape Pan American Silver's cash profile.
OceanaGold (TSX:OGC)
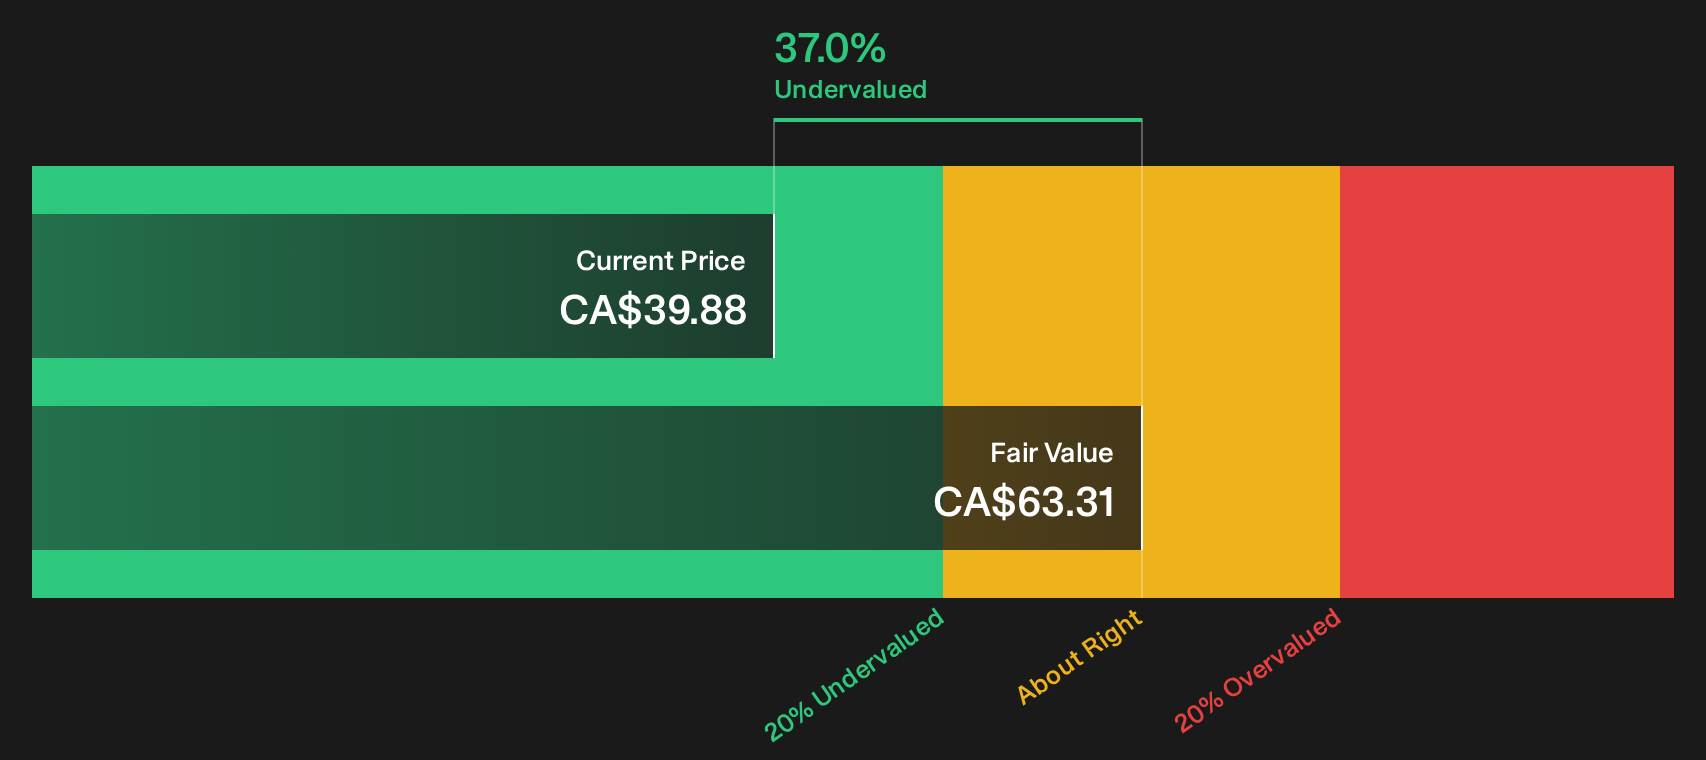
OceanaGold is a Vancouver based gold and copper producer whose operating mines supply the cash flows that anchor its discounted cash flow valuation, with revenue drawn mainly from Haile at about $796 million, Macraes at $781 million, Didipio at $549 million, Waihi at $338 million and a market value near CA$8.9b.
OceanaGold gives investors exposure to a portfolio of producing assets where current operations already underpin the cash flow story. A series of expansion projects could reshape that profile over time.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
What really moves the needle for OceanaGold is how one future decision around growth spending versus capital returns ultimately filters through to those cash flow driven margins.
That trade off is where things start to accelerate, and the full narrative for OceanaGold unpacks how OceanaGold weighs growth, cash returns and risk across its portfolio.
Suncor Energy (TSX:SU)
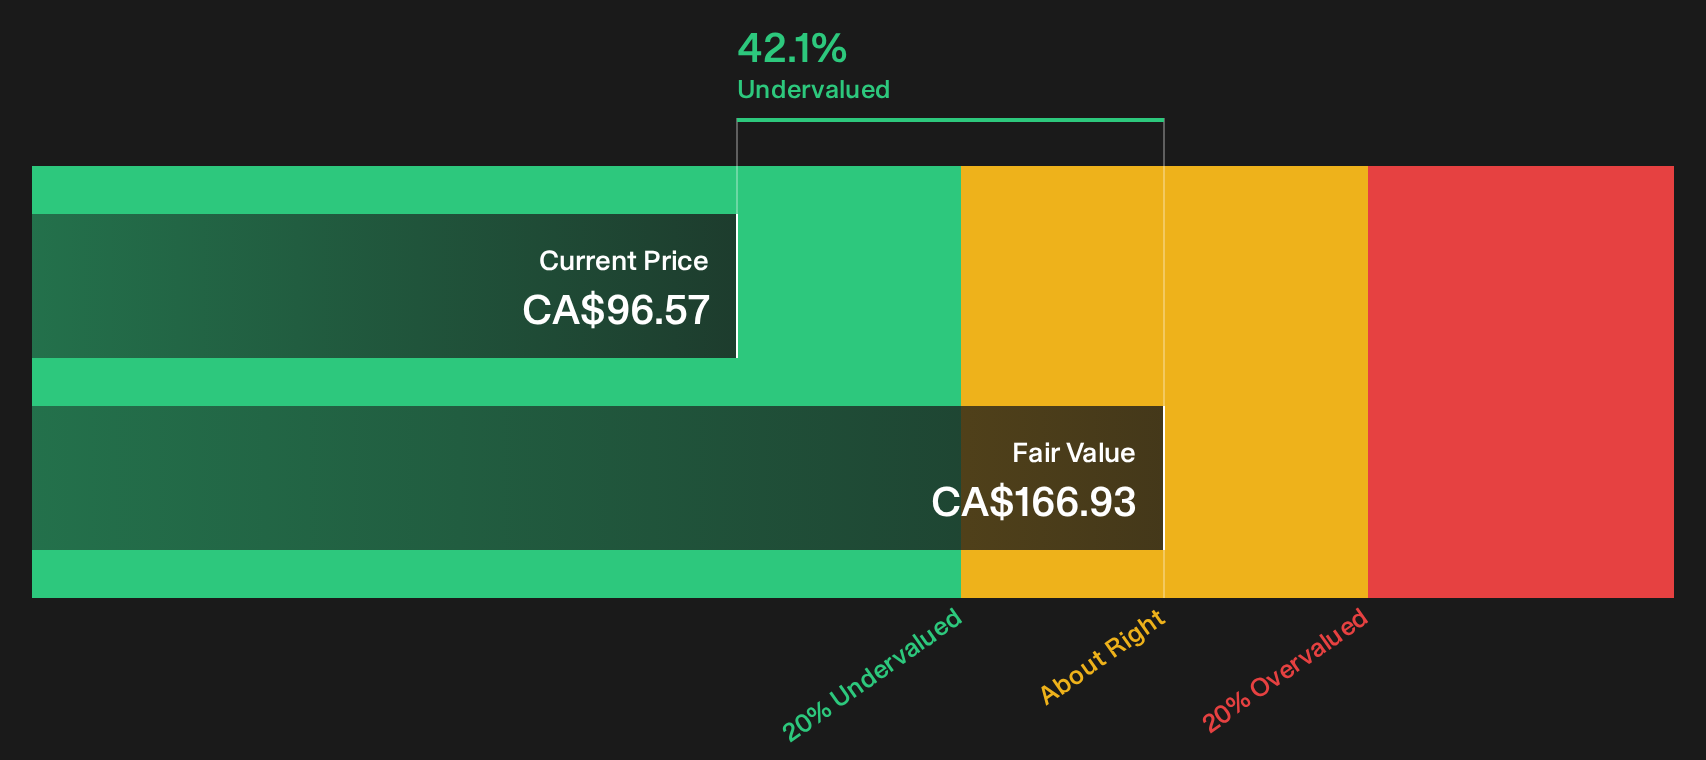
Suncor Energy is an integrated energy producer where long lived Oil Sands operations anchor the cash flow story, supported by Exploration and Production plus Refining and Marketing. Refining and Marketing contributes about CA$36.8b of revenue, Oil Sands about CA$26.9b, Exploration and Production CA$2.5b, with a market value near CA$113b.
Suncor Energy brings something different to this cash flow focused list by pairing its long life Oil Sands assets with refining and retail operations that can turn heavy crude into steady cash generation across the cycle.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages. This could pressure volumes and compress margins if reliability slips from current record levels."
For investors watching Suncor Energy, the real test is how one pressure on this high throughput model ultimately shapes future cash flow resilience.
That pressure point is exactly what the full narrative for Suncor Energy unpacks, separating temporary noise from cash flow trends that could be quietly accelerating beneath headline utilization risk.
Seeking Fresh Alternatives Beyond These Three?
Fresh ideas move first. By the time momentum screens show every breakout, the best entry points can be gone. Scan under the radar for now, act now.
- Target income that keeps working while you sleep by reviewing the 1 dividend fortresses before yields get caught dropping as prices move higher.
- Hunt for early movers in automation and factory efficiency by checking the curated 93 robotics and automation stocks while those stories are still under the radar for now.
- Position ahead of the next infrastructure build out by scanning the selected 40 power grid technology and infrastructure stocks before attention and capital start flying into the sector.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com