
BeOne Medicines (ONC) Rebrand Puts Its Growth Story In Focus On A Higher Fair Value
BeOne Medicines (ONC) has drawn fresh attention after formally adopting its new name and structure, shifting from BeiGene, Ltd. to BeOne Medicines AG in May 2025 while keeping a broad oncology focus across regions.
Recent trading suggests momentum is still positive for BeOne Medicines, with a 90 day share price return of 28.93% and a year to date share price gain of 16.02%. The 3 year total shareholder return of 100.62% points to a much stronger long run outcome than the most recent 30 day pullback of 3.98% in the share price might suggest.
Scan beyond BeOne Medicines and compare its recent momentum with a curated group of oncology and healthcare peers using our 38 healthcare AI stocks.
The recent jump in BeOne Medicines after the rebrand could echo confidence in its oncology portfolio, or simply reflect shifting mood around the ticker. The valuation numbers now need to do the talking.
Most Popular Narrative: 17% Undervalued
Against BeOne Medicines' last close of $360.85, the most followed narrative points to a fair value of $433.02 using a 7.28% discount rate.
BeOne's strong revenue growth (41% YoY in Q2; updated full-year guidance of $5 to $5.3b) is underpinned by rapid demand expansion for differentiated, best-in-class oncology therapies like BRUKINSA, supported by a growing, aging population and increased global healthcare spending, both of which point to a sustainably expanding addressable market and future revenue growth.
See why 20 investors see BeOne Medicines as 17% undervalued.
Result: Fair Value of $433.02 (UNDERVALUED)
Still, BeOne Medicines relies heavily on BRUKINSA and faces rising competition and policy pressure on drug pricing, which could significantly weaken the upbeat valuation case.
Find out about the key risks to this BeOne Medicines narrative.
Another View: What BeOne Medicines' P/E Is Saying
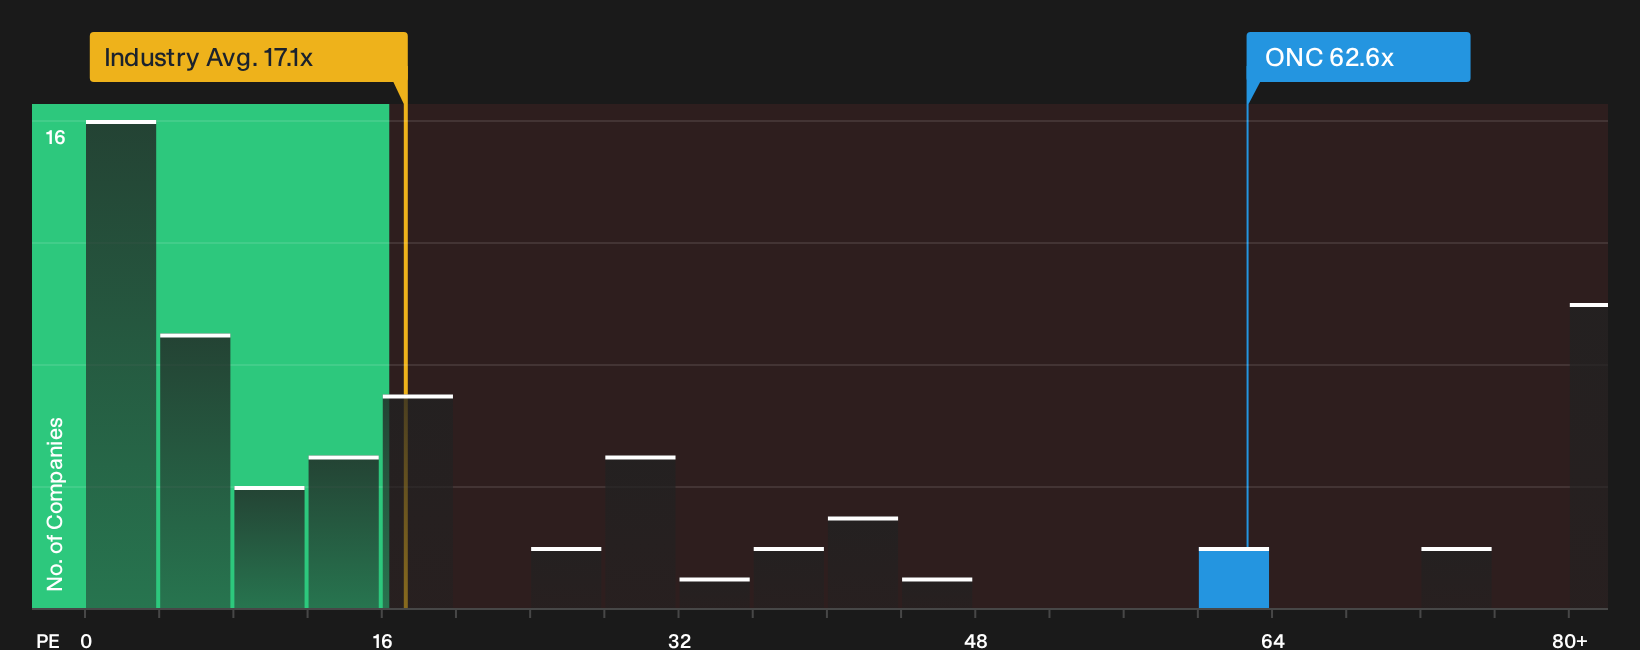
On a simple earnings multiple, BeOne Medicines tells a very different story. The stock trades on a P/E of 62.6x, which is far above the US Biotechs industry at 17.3x, the peer average at 28.9x, and even the fair ratio estimate of 33.3x that the market could move toward.
That gap points to meaningful valuation risk if sentiment cools, since a move closer to the fair ratio would mean a much lower implied price even if earnings forecasts stay intact. The question for you is whether the growth case and pipeline justify paying more than industry, peers and the fair ratio at the same time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around BeOne Medicines is clearly split, so treat this as a starting point and move fast to test the data yourself and stress test the upside case by reviewing the 3 key rewards.
Looking for more BeOne Medicines style ideas?
If BeOne Medicines has you thinking bigger about your portfolio, do not stop here. The real edge often comes from comparing a few focused shortlists side by side.
- Target resilient compounding by checking companies that screen as 30 resilient stocks with low risk scores where business quality and stability sit front and center.
- Hunt for potential bargains by reviewing our curated set of 32 high quality undervalued stocks that pair solid fundamentals with pricing that may look appealing.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (24 results) so you are not caught out when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com