
Learn Why The Bull Case For Scotiabank (TSX:BNS) Could Change Following ETF Portfolio Revamp
- Scotia Global Asset Management has announced changes to its Scotia Essentials Portfolios, increasing ETF exposure to at least 51% of net assets by March 31, 2027, cutting management fees on select series from November 1, 2026, and renaming the range Scotia Essentials ETF Portfolios while closing Scotia Partners Portfolios to new investors.
- The shift toward ETF-led portfolios with lower fees suggests Bank of Nova Scotia is leaning harder into scalable, cost-focused wealth products that can influence how its fee-based business evolves over time.
- Next, the focus turns to how this larger tilt toward ETF-based portfolio construction could reshape Bank of Nova Scotia's investment narrative.
Scan how Bank of Nova Scotia's fee-first tilt compares with other wealth-focused players by reviewing the hand picked list of solid balance sheet and fundamentals (7 results) in the current market.
Bank of Nova Scotia Investment Narrative Recap
To own Bank of Nova Scotia, you need to be comfortable with a large North American bank that leans heavily on Canada and the Pacific Alliance countries for growth, while carrying exposure to housing and Latin American volatility. The key short term swing factor remains credit quality, especially in international markets and Canadian mortgages.
The recent euro and US dollar fixed income offerings appear incremental rather than transformative for that near term story. They add to funding flexibility but do not directly change loan demand, digital execution, or competitive pressure from fintechs, which still sit beside credit costs as the biggest operational risks right now.
The €600 million floating rate notes due 2038 are particularly relevant in this context. They extend Bank of Nova Scotia funding in Europe and introduce variable coupons that can move with interest benchmarks, which can help the bank align liabilities with floating rate assets in its loan books and markets business.
For you as a shareholder, this relates to the same core catalysts already in play. Balance sheet optimization, funding mix, and fee based expansion through wealth and ETF products all influence how efficiently Bank of Nova Scotia can support loan growth across Canada and the Pacific Alliance without stretching its allowance for bad loans or compressing returns further.
Bank of Nova Scotia's current analyst story points to forecast revenue of CA$48.6b and projected earnings of CA$12.3b by 2029. This implies revenue growth of 11.3% per year and an earnings increase of about CA$2.8b from CA$9.5b today.
Discover why the forecast for Bank of Nova Scotia's fair value is essentially consistent with its current price.
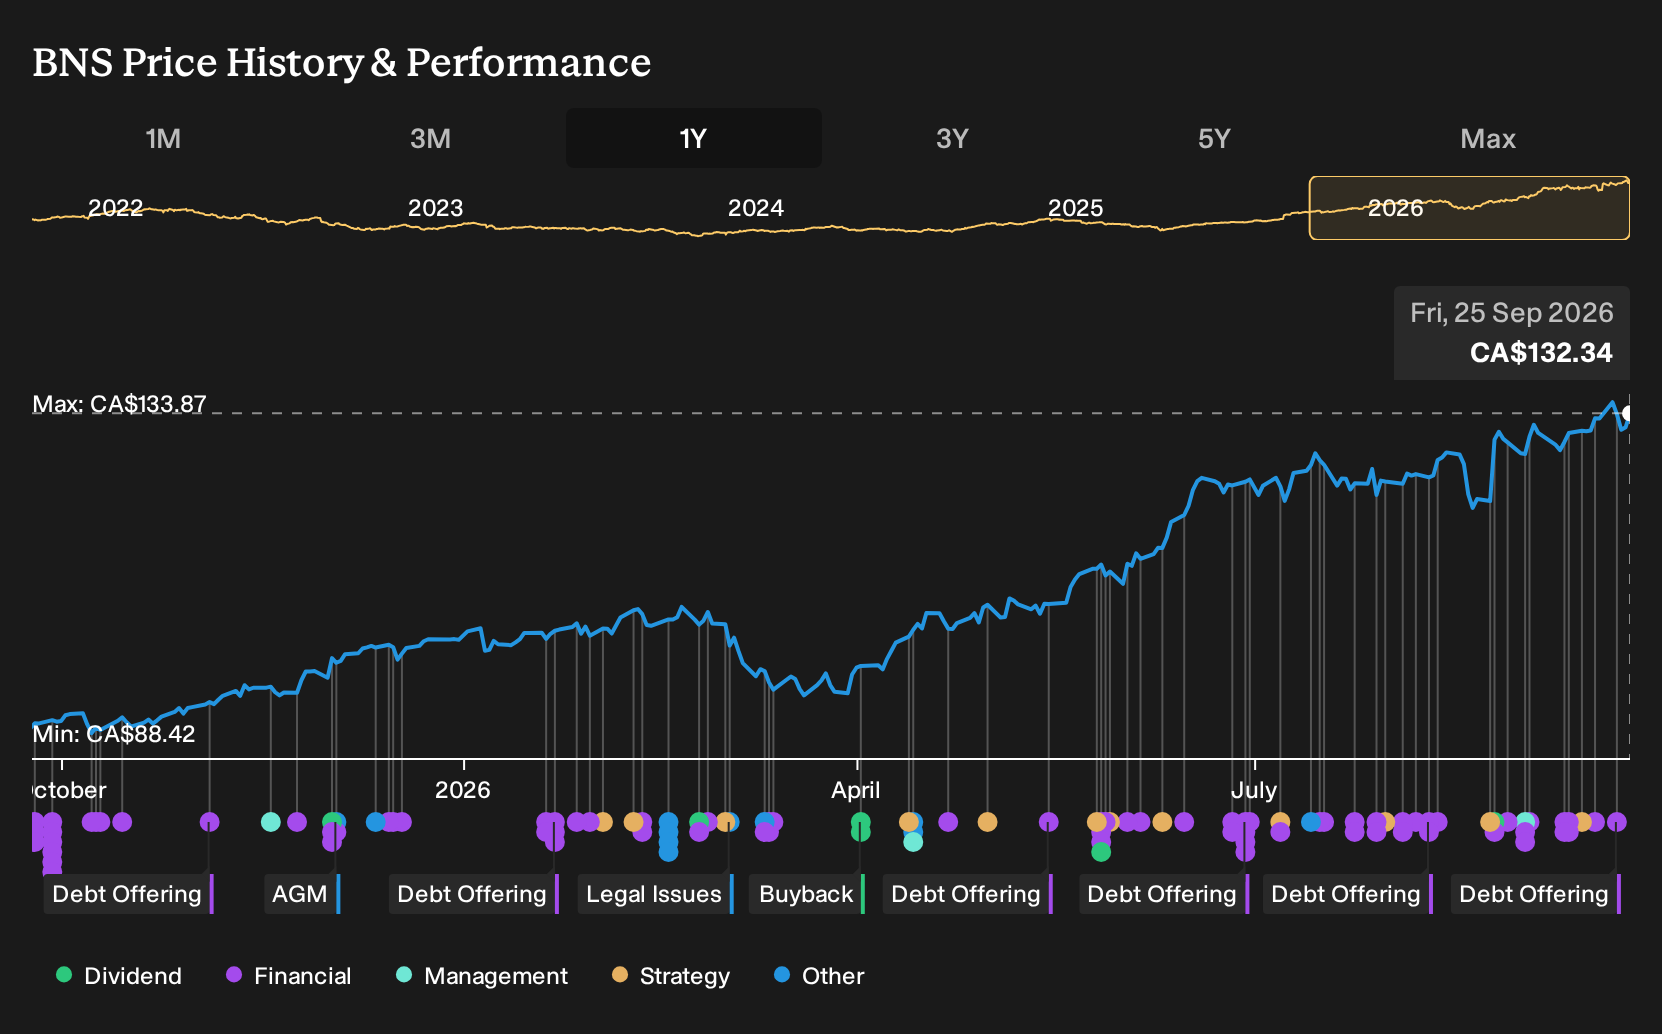
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly CA$132.7 to CA$181.9, so you are looking at a wide gap between the most cautious and most optimistic views on Bank of Nova Scotia. Set that against Latin America and Canadian housing risks, plus new fixed income funding and the Scotia Growth Institute, and you get sharply different narratives. Opinions clearly diverge, so explore several community viewpoints before deciding how this fits your own thesis.
Explore 2 other Bank of Nova Scotia fair value estimates, including one that suggests up to 37% higher than the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Nova Scotia research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Nova Scotia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Nova Scotia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank of Nova Scotia?
If you want to stress test your view on Bank of Nova Scotia, it helps to compare it with other businesses that share some of the same traits, whether that is income strength, balance sheet quality, or potential mispricing.
- For income focused investors who care about steady payouts, scan a curated set of companies with attractive yields through the 1 dividend fortresses.
- If capital preservation and resilience matter most to you, weigh Bank of Nova Scotia against a 8 resilient stocks with low risk scores that has been filtered for sturdier risk profiles.
- When you want to focus on quality at a reasonable price, broaden your watchlist with a 5 high quality undervalued stocks that pairs solid business fundamentals with discounted valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com