
Subaru (TSE:7270) Looks Fully Valued After Its U.S. Fleet Data Deal
Subaru (TSE:7270) just moved its connected vehicle ambitions into the spotlight. A new deal with Motorq will send embedded telematics from 2027 Subaru models directly to U.S. fleet operators.
The Subaru share price has climbed 10.79% over the past 90 days but is still down 22.79% year to date, while the 1 year total shareholder return shows an 11.19% decline and the 5 year total shareholder return sits at 53.08%. This suggests long term holders have fared better than recent buyers as connected vehicle news feeds into a recovering but still uneven price trend.
Scan beyond Subaru and see which auto and mobility players our analysts flagged as potential connected vehicle winners in the 87 AI infrastructure stocks list.
Subaru now trades only slightly below analyst targets, despite a sharp recent rebound and weaker one year returns. Is that a cautious market finally catching up, or still reluctant for good reason?
Price-to-Earnings of 22x: Is Subaru's Premium Justified?
Subaru trades on a P/E of 22x, which is higher than both its Asian auto peers and its closer-listed comparables. That premium sits on top of a ¥2,660 last close and asks investors to accept richer pricing for the earnings on offer.
The P/E ratio compares what you pay per share to the profits that Subaru generates per share. For a cyclical sector like autos, a higher multiple often signals that the market is willing to pay up for perceived quality of earnings, steadier profitability, or a clearer earnings path than rivals.
Here, the market price looks demanding. Subaru is described as expensive versus the Asian auto industry average P/E of 13.3x and also above the peer group average of 17.7x. It is trading ahead of an estimated fair P/E of 17.1x. This is a level that the valuation work suggests the multiple could reasonably gravitate toward if sentiment cools or earnings delivery disappoints.
Explore the SWS fair ratio for Subaru.
Result: Price-to-Earnings of 22x (OVERVALUED)
Still, the rich P/E leaves Subaru exposed if earnings growth slows or if adoption of connected vehicles by U.S. fleets proves lumpier than investors currently expect.
Find out about the key risks to this Subaru narrative.
Another View On Subaru's Value
Subaru looks expensive on a P/E of 22x, yet the SWS DCF model tells a slightly different story. On that framework, the current ¥2,660 quote sits above an estimated future cash flow value of ¥2,532.2, which points to the shares being overvalued rather than underpriced on cash generation.
That gap is not huge in yen terms, but it still raises a practical question for you as an investor: is it worth paying above a cash flow based estimate when the market already assigns a premium multiple and profit growth is forecast, not guaranteed?
Look into how the SWS DCF model arrives at its fair value.
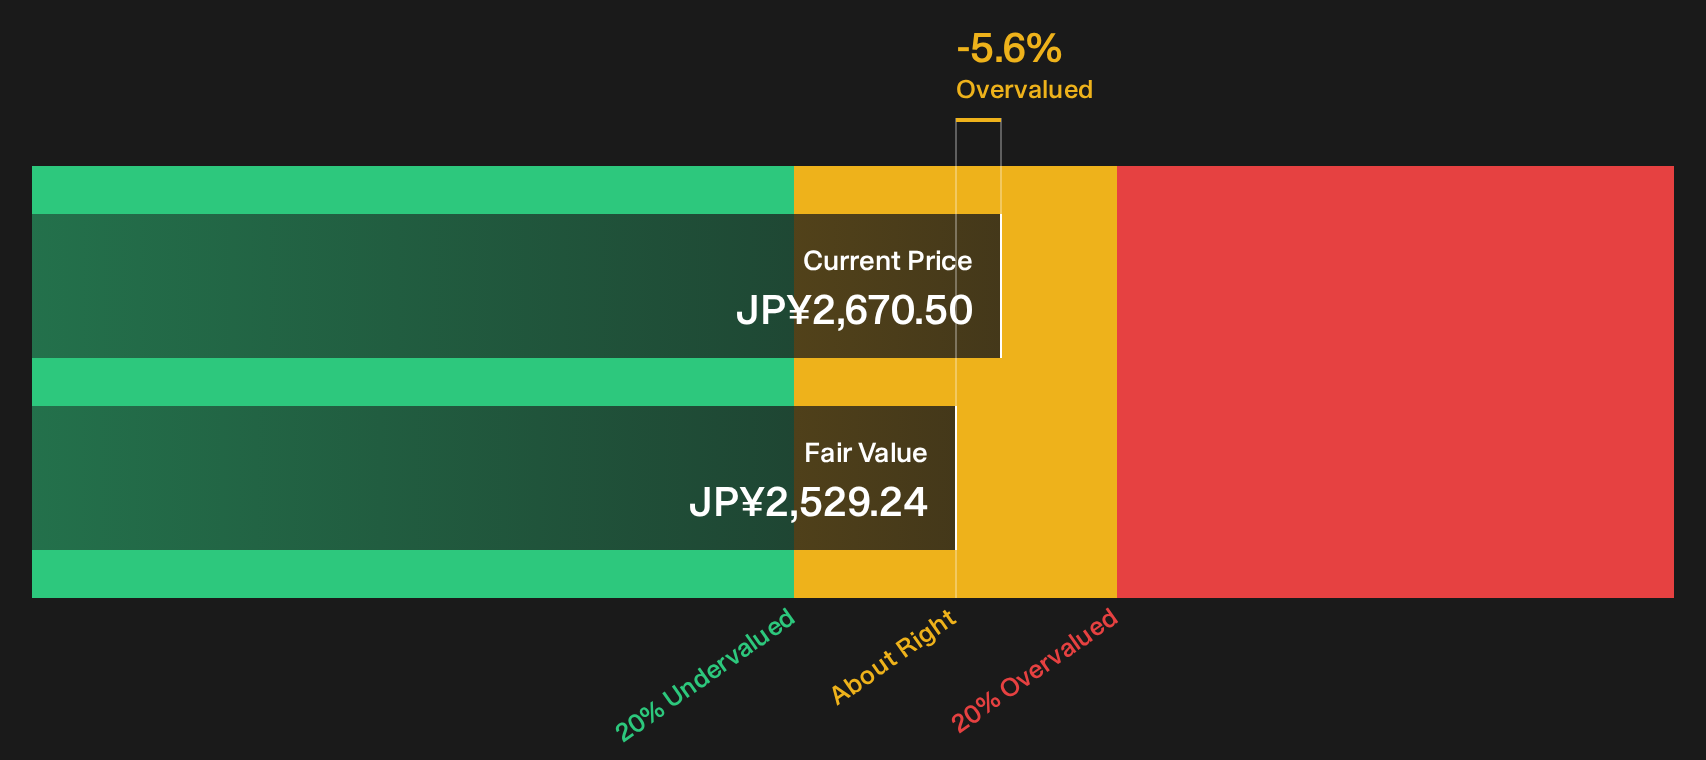
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Subaru for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Subaru so far. If you want to move quickly and build your own view using the same toolkit, start with the 1 key reward and 2 important warning signs.
Looking For More Ideas Beyond Subaru?
If Subaru has you thinking harder about where to put fresh capital, do not stop with a single ticker. Cast a wider net with focused stock lists built on hard data.
- Spot potential mispriced opportunities early and sift through companies that screen as high quality yet underappreciated via the 18 high quality undervalued stocks.
- Secure more predictable cash returns by reviewing businesses that feature in the 14 dividend fortresses and offer stronger yield profiles than the market average.
- Prioritise resilience and capital protection by scanning companies that pass tough risk filters in the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com