
Raised Guidance Might Change The Case For Investing In CECO Environmental Stock (CECO)
- CECO Environmental recently raised the lower end of its 2026 revenue guidance after reporting 8.4% year over year revenue growth and an 81% jump in orders in its Industrial Process Solutions unit, supported by a strong backlog tied to environmental regulation projects.
- The same update highlighted a tension in the CECO Environmental story, with record demand and a growing project pipeline arriving alongside shrinking adjusted operating margins and a high net-debt-to-EBITDA ratio that elevates financial risk.
- We will now see how CECO Environmental's investment narrative could shift given raised revenue guidance driven by Industrial Process Solutions orders.
Compare CECO Environmental's risk and reward trade off with a curated group of industrials that have stronger balance sheets and cleaner profitability in our 30 resilient stocks with low risk scores.
CECO Environmental Investment Narrative Recap
For CECO Environmental, the big-picture belief hinges on demand for industrial air, water, and energy transition solutions staying healthy enough to support its backlog and order pipeline. The recent guidance lift, driven by Industrial Process Solutions orders, supports that demand story. The near-term catalyst remains execution on this record backlog without further strain on costs.
The main risk has not changed. Shrinking adjusted operating margins and a high net-debt-to-EBITDA ratio leave little room for missteps if bookings slow or project delays emerge. Elevated leverage keeps financing costs and refinancing risk front of mind, especially while the business is still unprofitable.
The clearest recent development tied to this story is management raising the lower end of 2026 revenue guidance after 8.4% revenue growth and a very large jump in Industrial Process Solutions orders. That update indicates the order book is still filling, particularly in areas like power generation, industrial water, and natural gas infrastructure.
For catalysts, the key question is whether CECO Environmental can convert that backlog into cash flow while stabilizing margins. Potential upside is tied to smooth project delivery, acquisition integration, and cost discipline. On the risk side, high leverage and shareholder dilution over the past year leave less cushion if project timing or pricing turns against the company.
CECO Environmental's current analyst narrative points to revenues of US$2.3b and earnings of US$260.7m by 2029, based on forecast revenue growth of 42.4% per year and an earnings increase of roughly 19x from US$13.7m today.
Uncover why CECO Environmental's fair value points to a 47% potential upside to its current price, which could narrow quickly.
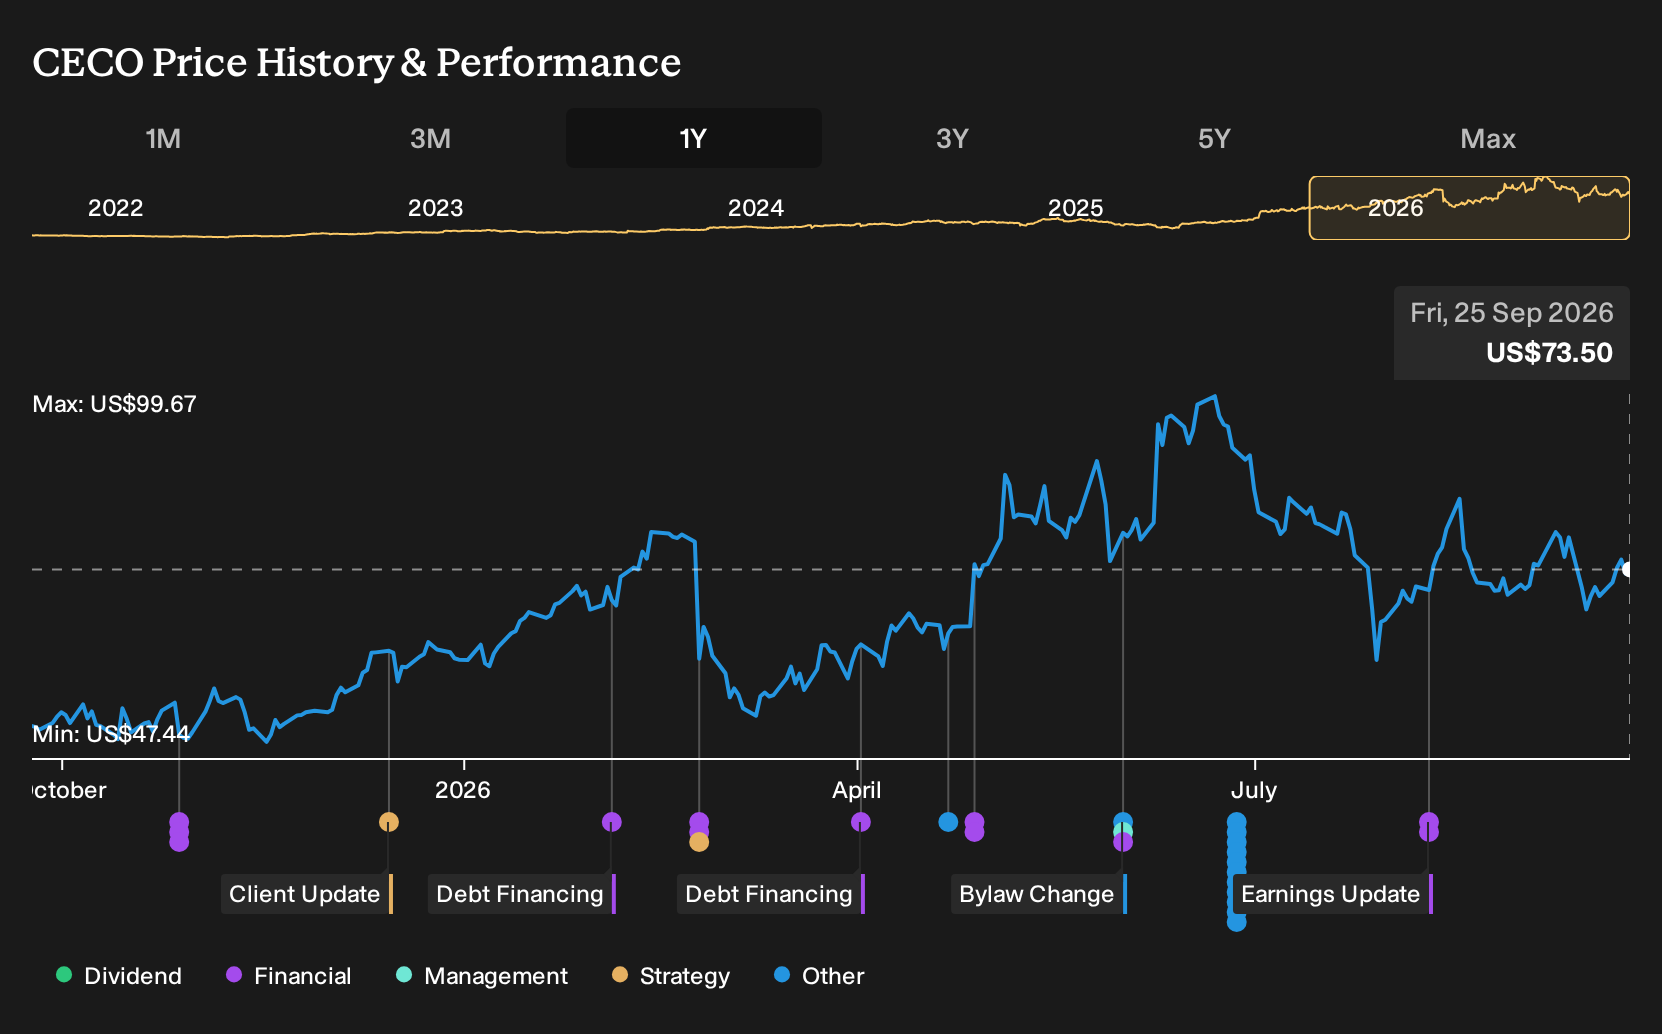
Exploring Other Perspectives
One big swing factor in the more optimistic CECO Environmental story is the Thermon deal. Bullish analysts were already penciling in revenue of about US$2.3b and earnings near US$284.1m by 2029, compared with US$260.7m in the baseline view. With today’s backlog news, those opposing opinions could shift further.
Explore 3 other CECO Environmental fair value estimates, including one that suggests up to 77% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking for more investment ideas beyond CECO Environmental?
Once you have a view on CECO Environmental, it can help to compare that thesis with other opportunities that share similar qualities or offer a very different risk profile. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or upside potential in a few clicks.
- If capital preservation is a priority, start with a curated set of businesses that pair lower risk scores with resilient fundamentals using the 30 resilient stocks with low risk scores.
- For investors hunting for value, consider stocks that combine quality fundamentals with the potential for mispriced upside through the 32 high quality undervalued stocks.
- If dependable income streams matter most, focus on companies offering higher yields and stronger payout profiles via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com