
Why Moody's Stock Matters When 10 Year Treasury Yields Stay Above 5%
When the US 10-year Treasury sits above 5%, the rules of the game start to feel different for both bond buyers and equity holders. Income from fixed income looks more appealing, and that can pull attention away from stocks that once thrived on cheap money. This article shows how that shift filters through to three specific ETF and index providers exposed to this rate shock, and what their stories might mean for your portfolio choices.
The stocks profiled below are only a starter set, and the full screen surfaced 32 more listed ETF and index providers with equally compelling fixed income stories that are not covered here. To go broader than this shortlist and identify, compare, and analyze the highest conviction ideas in this niche, head straight into the Global Fixed-Income ETF and Index-Tracking Providers screener.
M&G (LSE:MNG)
Overview: M&G is a London based savings and investment group that runs large fixed-income, multi-asset and pension products for clients worldwide.
Operations: M&G generates about £4.6b from Asset Management and £1.2b from Life, with fixed-income and multi-asset mandates central to both segments.
Market Cap: £7.8b
For investors hunting for bond heavy ETF and index exposure, M&G offers a direct link into fixed-income mandates wrapped inside a broader savings franchise, which is where the real story starts to get interesting.
"The shift of Life new business to fee based With-Profits products, including BPA, PruFund and retail annuities, is expected to increase the share of capital light, fee related earnings, which should support operating profit quality and net margins over time. Ongoing AI driven productivity gains, cost transformation and a targeted 70% Asset Management cost to income ratio are aimed at keeping expense growth below revenue growth, which, if achieved, would support operating leverage, capital generation and earnings per share."
What happens if a single assumption in that plan for leaner costs and richer fee income proves either too cautious or too bold?
If that question is on your mind, the full narrative for M&G shows how M&G’s cost reset, fee mix and rate sensitivity could be quietly reshaping its return profile.

Apollo Global Management (APO)
Overview: Apollo Global Management is a New York based alternative investment group focused on credit, private equity and income oriented fixed-income strategies.
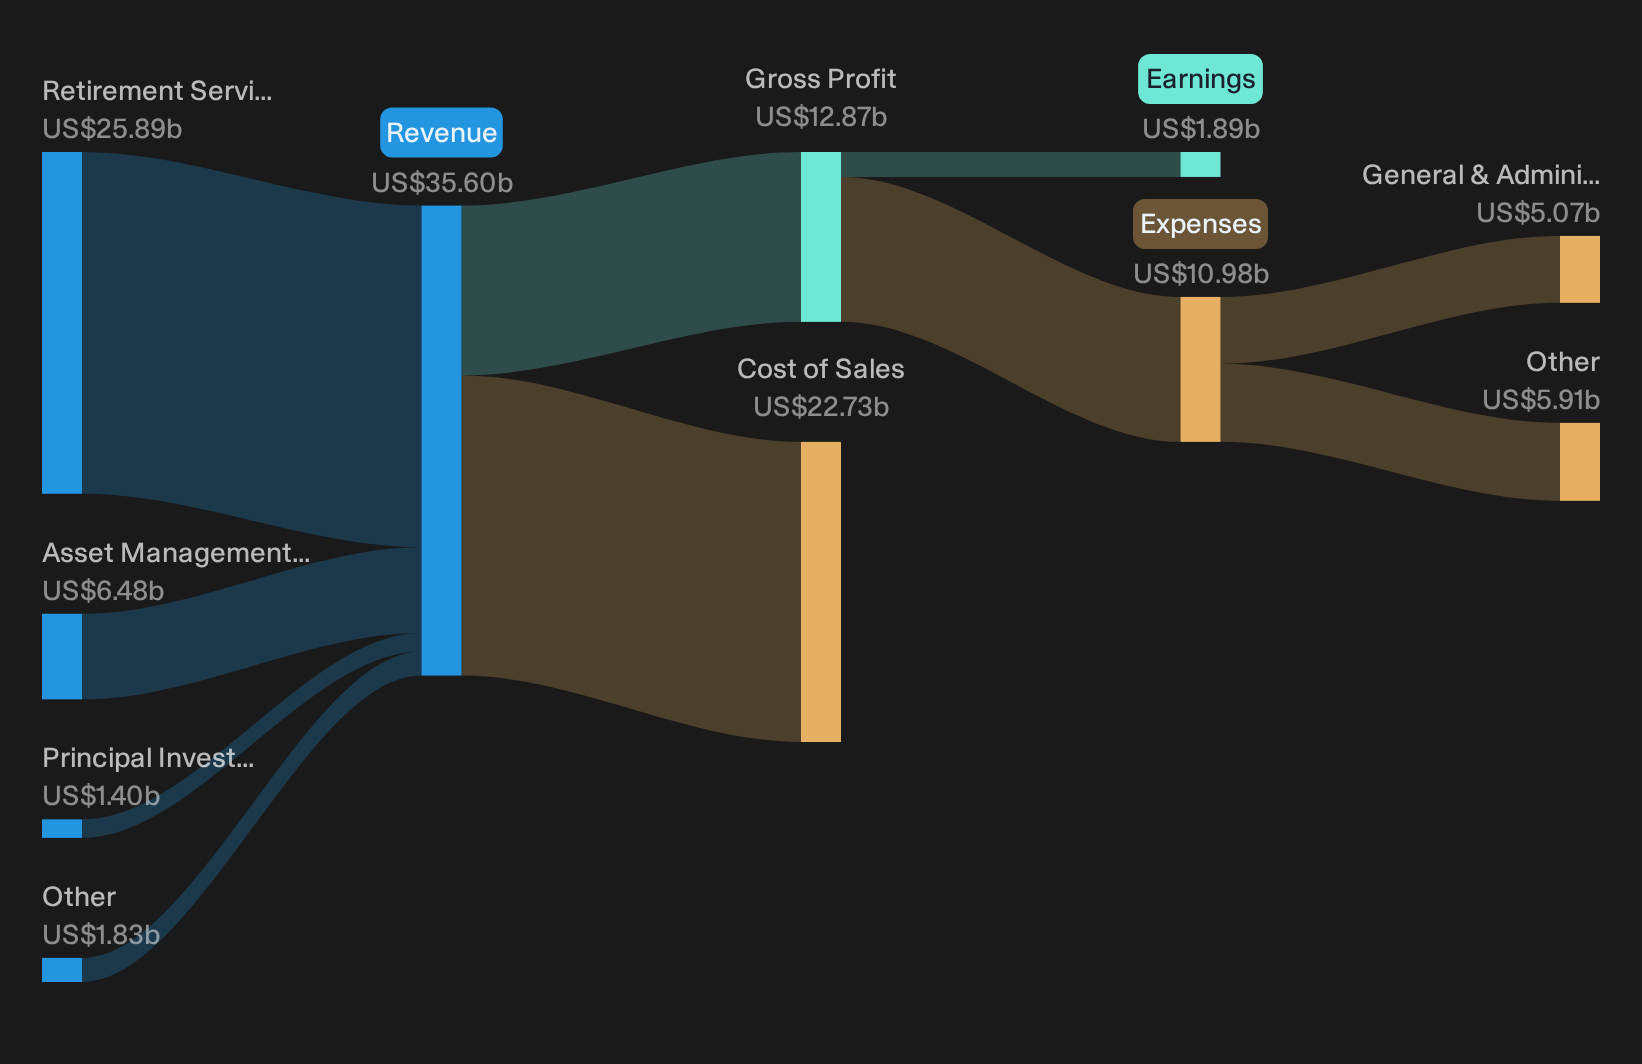
Operations: Apollo generates about US$6.5b from Asset Management, US$1.4b from Principal Investing and US$25.9b from Retirement Services.
Market Cap: US$71.9b
Apollo Global Management plugs into this fixed-income and ETF themed screen through its credit heavy business model, giving investors access to yield oriented strategies that sit alongside more traditional bond and index fund providers.
"Apollo's inclusion in the S&P 500 is expected to broaden its shareholder base, leading to potential growth in public market exposure and thus possibly driving future revenue increases."
The real hinge for Apollo Global Management in a higher rate world is how one unresolved funding pressure interacts with that broader reach.
That tension around funding is exactly where the story gets interesting, and the full narrative for Apollo Global Management explores how Apollo Global Management’s funding mix could either accelerate its next phase of growth or limit it.
Moody's (MCO)
Overview: Moody's is a global risk assessment group that provides credit ratings, financial data and analytics to banks, investors, companies and governments.
Operations: Moody's generates US$4.7b from Moody's Investors Service and US$3.7b from Moody's Analytics, after a US$214 million eliminations adjustment.
Market Cap: US$81.2b
Moody's matters to this fixed-income focused screen because every spike in bond issuance and credit risk tends to pull more investors, banks and ETF providers toward its ratings, data and analytics toolkit.
"What makes the story even stronger today is that Moody’s is no longer only a ratings company. Over the past decade, management has steadily built Moody’s Analytics (MA) into a major recurring-revenue software and data business."
What happens to Moody's earnings power if one quiet shift in how institutions manage debt refinancing risk persists in a higher rate world?
If that shift is on your radar, the full narrative for Moody's illustrates how Moody's earnings engine could be moving away from traditional credit cycle assumptions.

Curious About What You Might Be Missing?
Fresh ideas often move first. Once momentum builds, prices can rise quickly before you even spot them. Scan these under the radar lists while it matters and consider getting in at an earlier stage.
- Identify steadier compounders before they attract wider institutional attention by reviewing a curated list of solid balance sheet and fundamentals (10 results) that filters for financial strength and cleaner fundamentals.
- Explore potential income opportunities from companies screened for robust payouts with a focused 1 dividend fortresses that emphasizes yield quality and resilience.
- Review companies positioned for infrastructure and electrification themes by assessing a hand picked 40 power grid technology and infrastructure stocks tuned to grid upgrades and supporting technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com